- EUR/USD outlook has not changed because US data delays/shutdown
- Fed speakers and ISM services in focus, but AI-driven tech rally dominates sentiment
- Euro benefits from softer energy prices, while ECB maintains cautious stance
Financial markets are experiencing one of their quieter patches, with volatility ebbing away across asset classes – an in particular, the FX markets. This is all thanks to postponement of US government data due to the ongoing shutdown. Still, we have had and will get to see the release of more private sector data, with the ISM services PMI today being the main focal point. We will also get to hear from a few Fed officials today. From the eurozone, the latest data outside of services PMIs from Spain and Italy were far from great. This kept the EUR/USD in a holding pattern in what otherwise should be a mildly positive backdrop. For indeed, drivers outside of US data have been euro-supportive, with lower oil and gas prices helping currencies that rely on energy imports. Also aiding the FX markets is the equity markets, where an extraordinary rally in AI-focused mega cap tech stocks is keeping risk sensitive currencies supported. Added to this, the signs from private US data this week have pointed to further weakness in labour market. All told, the EUR/USD forecast remains mildly bullish, and the path to 1.20 handle still open.
US dollar remains under pressure ahead of ISM PMI
The mild US dollar recovered has stalled this week, with the DXY index falling back below 98.00 and threatening to go lower. A mix of factors explains this trend. Markets are increasingly convinced the Federal Reserve will cut rates twice more this year and by another 50bp in 2026, reducing the scope for further dollar upside. At the same time, the delayed jobs data removes a key reference point for the inflation–labour market debate.
The ISM services release and speeches from Fed officials, including John Williams and Stephen Miran, are on the radar today. Yet, barring a major surprise, these are unlikely to jolt the dollar meaningfully. The ISM PMI is expected to print 51.8 on the headline front, but do watch out for the employment component which is what everyone is focused on.
EUR/USD outlook boosted by energy prices weakening
The euro, meanwhile, has drawn some quiet support from softer energy prices. Lower oil and natural gas costs means it is cheaper to import, making the single currency more attractive at the margin. This is a helpful offset given the subdued domestic picture – as we found out again today with the release of weak final PMIs from Germany and France.
The ECB remains cautious, with Christine Lagarde and fellow policymakers signalling that the deposit rate at 2.00% is “in a good place.” However, the willingness to cut again if inflation undershoots cannot be dismissed yet, although that will be a good problem to have. No more rate cuts are likely for 2025 as things stand, although there is an outside chance for another 25bp reduction in the coming months should the macro situation deteriorate further.
Technical EUR/USD Outlook: consolidation with bullish bias
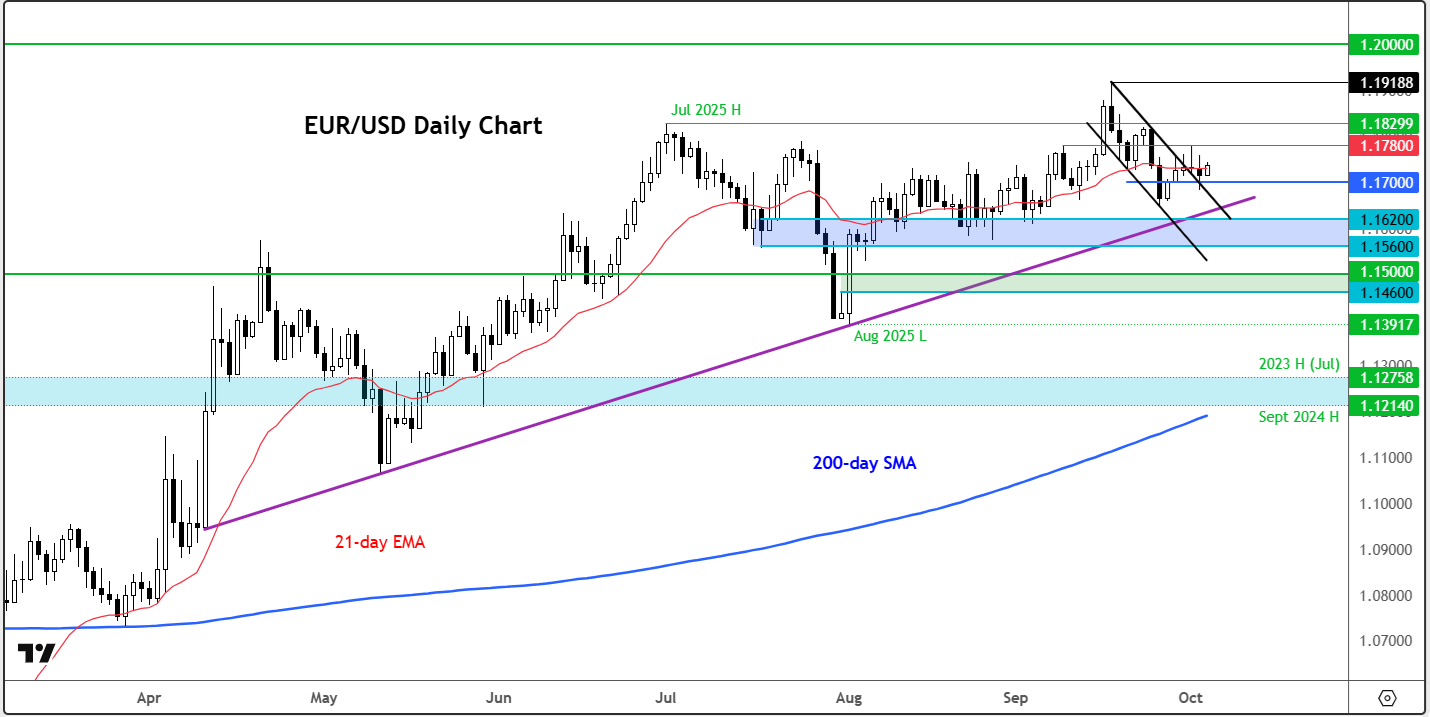
All told, the EUR/USD outlook points to more consolidation rather than a decisive breakout. The dollar is capped by falling yields and a lack of fresh catalysts, while the euro is propped up by weaker oil prices but constrained by a soft growth backdrop. This is reflected in price action with the EUR/USD stuck around 1.1700 to 1.1800 area. Support below this range is at 1.1670 then 1.1600. Resistance above 1.1800 comes in at 1.1850, 1.1900 and then 1.200 is the next major psychological hurdle should we get there.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R