- Chinese steel output slumps to a 21-month low
- Urban investment falls for first time since 2020
- Price repeatedly tested 200DMA without breaking
- Momentum signals favour downside
Summary
Chinese crude steel output cratered in September while fixed asset investment in urban areas declined for the first time since the pandemic, providing a troubling fundamental picture for iron ore demand. With the price now resting on a key technical level, movements in the short term could prove influential on the longer-term trajectory for prices.
Iron ore testing key 200DMA
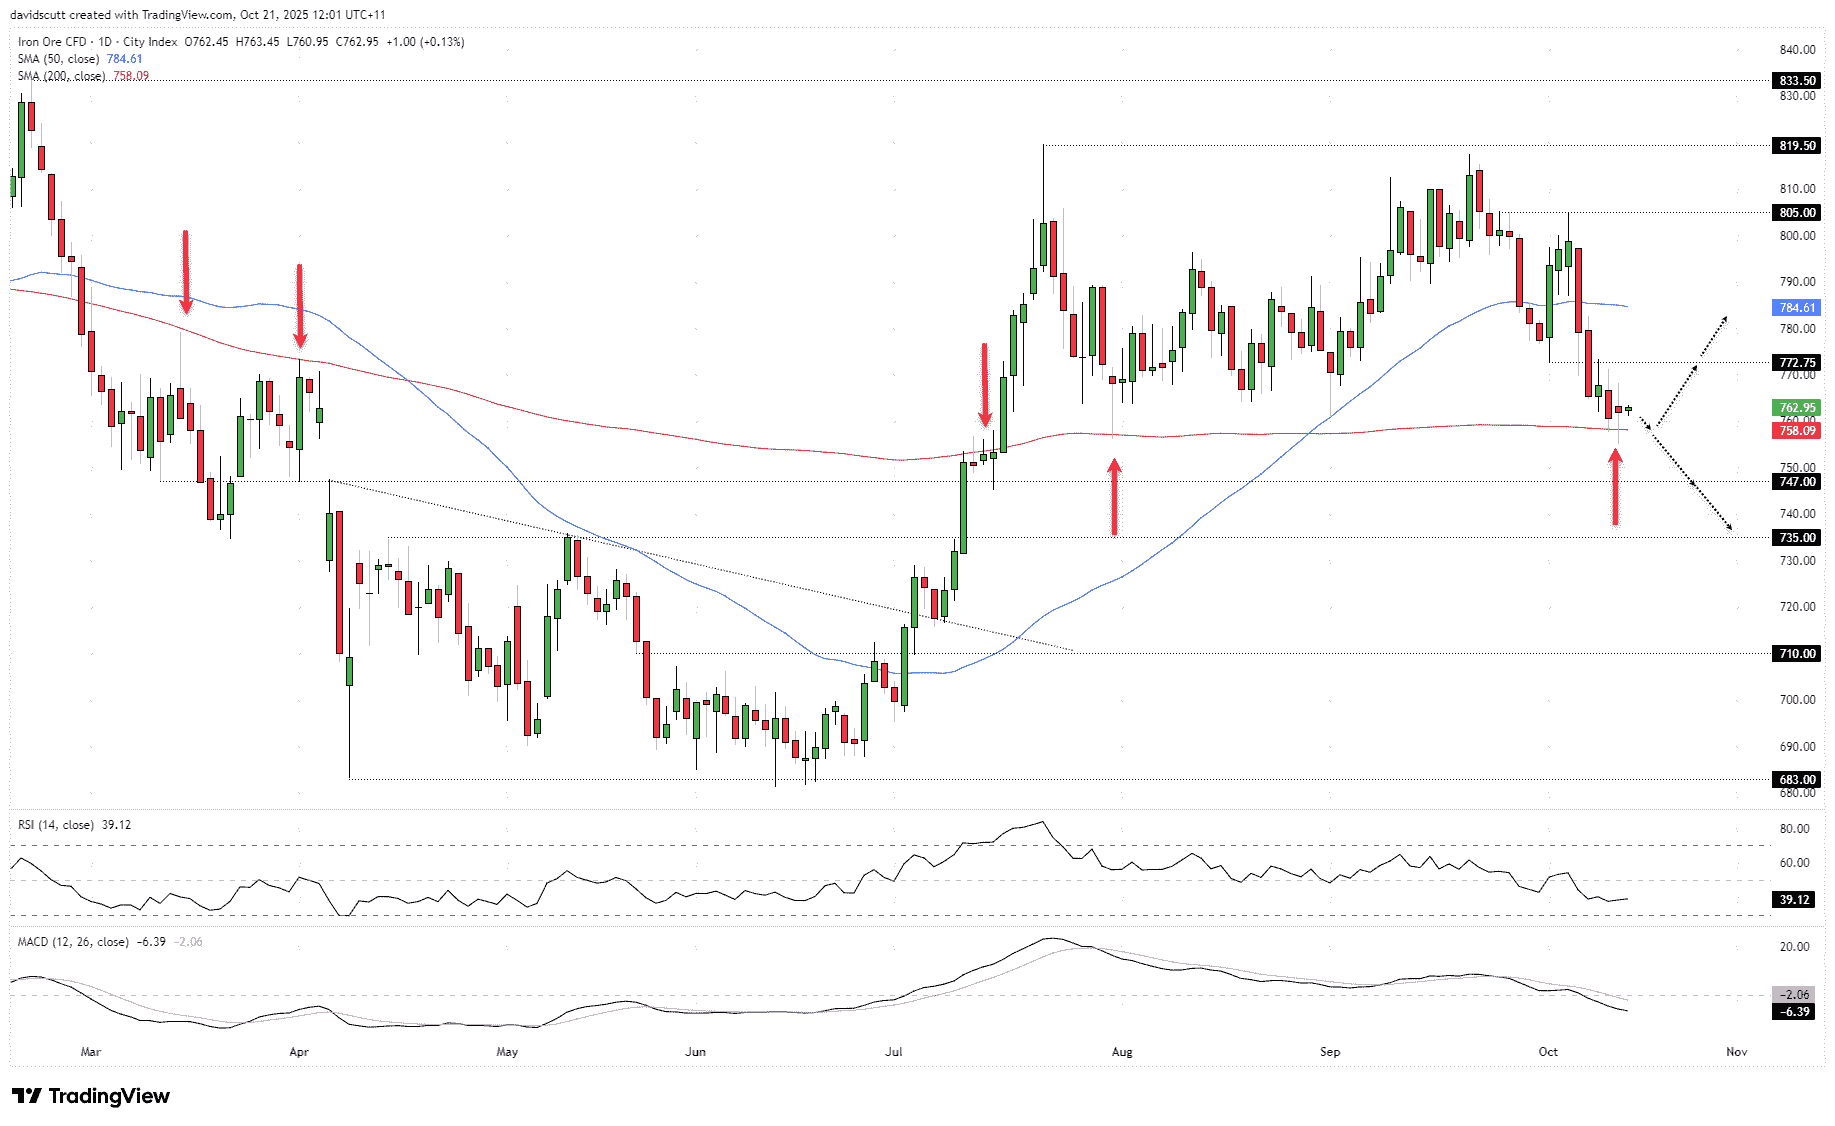
Before looking at potential trade ideas, it’s worthwhile pointing out just how respectful the iron ore contract has been of the 200-day moving average so far in 2025, often testing the level but rarely breaking sustainably through it.
Given that historic relationship, it suggests the level could be a good one to build setups around, allowing for entry on one side with a stop on the other to protect against reversal.
Source: TradingView
The price has traded through the 200DMA in each of the past two sessions only to reverse back higher, reinforcing its importance. Signals from RSI (14) and MACD reveal a picture of strengthening bearish momentum, with the former trending lower beneath 50 while the latter has pushed into negative territory having already crossed over from above earlier this month. The overall backdrop therefore favours downside over upside near term.
Should those downside risks materialise with the price breaking and closing beneath the 200DMA, shorts could be established beneath the level with a stop above for protection, targeting either ¥747 or ¥735, two levels that provided both support and resistance earlier this year.
However, if the price continues to bounce from the 200DMA as has been the case on the last three times of testing, it may provide enough confidence to initiate countertrend long trades, allowing for positions to be established above the level with a stop below for protection. ¥772.75 is a minor level above that could act as an initial target. Beyond, the 50DMA screens as another option along with ¥790 which saw plenty of price action either side of it during August and September.

Fundamental backdrop deteriorates
As mentioned in the summary, the fundamental backdrop appears anything but bullish for iron ore given recent news flow. Urban fixed asset investment—which measures spending on buildings, structures and equipment designed to last two years or more—contracted 0.5% between January to September relative to the same period a year earlier. It was the first decline since the pandemic shutdowns in early 2020. That’s clearly not good news for industrial commodities like iron ore. Nor was data showing crude steel output—of which iron ore is a key ingredient in conventional steelmaking—slumped to 73.49 million tonnes in September, a 21-month low and 4.6% below the levels of a year earlier.
Adding to the bearish demand picture, there remains no signs of an easing in China’s property market slump with data released on Monday revealing new and existing prices nationwide fell 0.4% and 0.6% respectively last month, accelerating on the pace seen in August. Once the single largest source of steel demand globally, declining construction activity, negative population growth and continued price weakness remains a clear negative for the iron ore price outlook.