




060720 Us Pre Open
The S&P 500 Futures are bouncing after U.S. markets were closed on Friday
Share this:

The S&P 500 Futures are bouncing after U.S. markets were closed on Friday in observance of Independence Day.
European indices are sharply up, gaining more than 1.5% on average. On the statistical front, in the euro-zone, retail sales rebounded in May by 17.8%, more than expected, after falling by 12.1% the previous month (revised from -11.7%). On the other hand, the Sentix Euro-Zone Investor Sentiment Index rose less than expected from -24.8 in June to -18.2 in July. In Germany, industrial orders rebounded by 10.4% in May (less than the +15% expected), after a 26.2% drop in April (revised from -25.8%). On the other hand, the PMI construction index rose to 41.3 in June from 40.1 in May. In Great Britain, the PMI Construction Index rebounded to 55.3 in June after reaching 28.9 in May. It was expected to reach 46.0.
Asian indices traded significantly higher except the Australian ASX 200 losing 0.71 % as the most-populous states decided to close their borders from Tuesday night as authorities take measures to control a coronavirus outbreak in the city of Melbourne. On the other side, the China Mainland CSI 300 recorded its biggest rally since 2015, rocketing 5.67% after closing on Friday at a 5-year high. The Chinese index is now up 14% year to date. The Japanese Nikkei added 1.83% and Hong Kong HSI rose 3.81%.
WTI Crude Oil futures rose during Asian trading hours. Kazakhstan's Energy Ministry said the country produced 5.3M tons of oil in June, with output cut compliance reaching 105%.
Gold remains firms on COVID-19 fears. Gold rose 5.27 dollars (+0.3%) to 1777.32 dollars.
Risk currencies gain ground on rallying equities. EUR/USD gained 66pips to 1.1314 while GBP/USD rose 24pips to 1.2507.
US Equity Snapshot
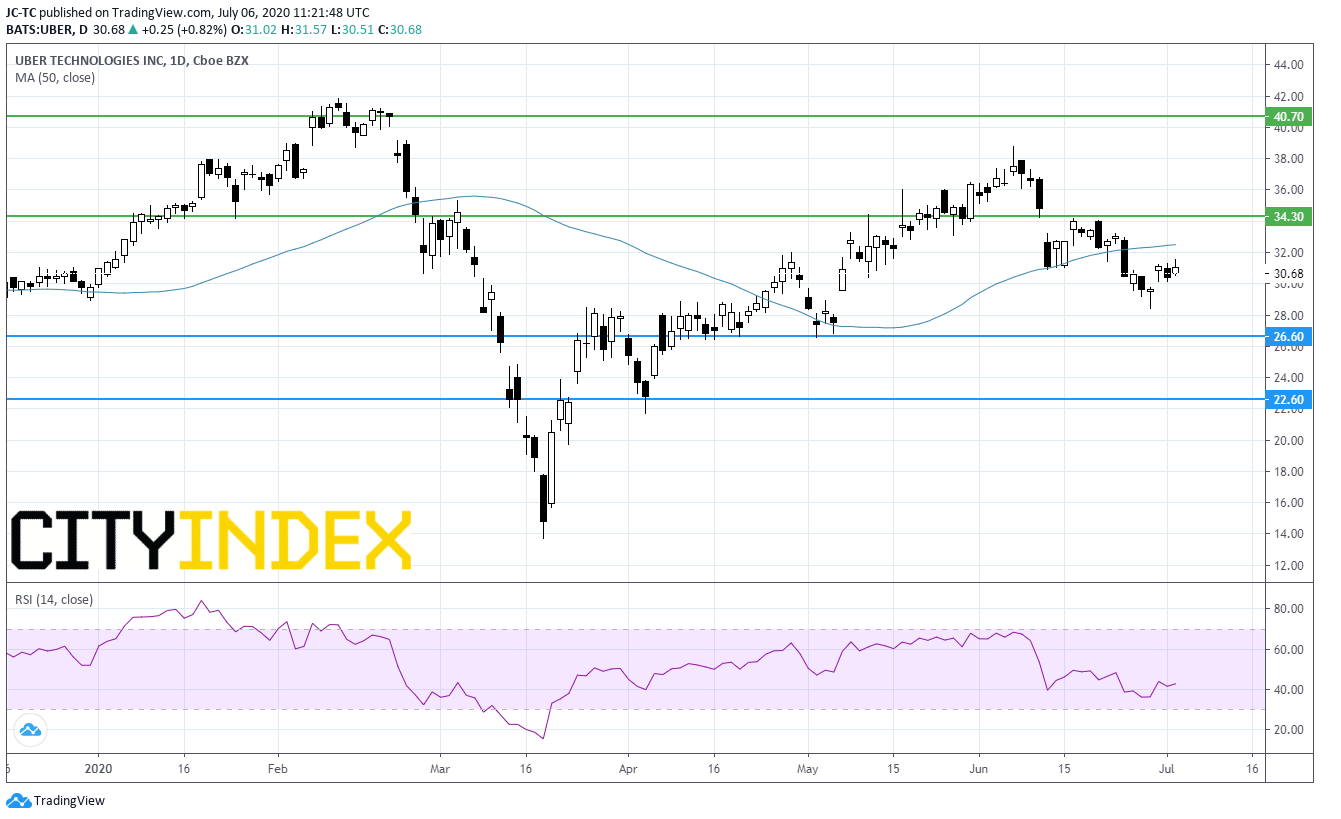
Uber Technologies (UBER), a ride-hailing company, has agreed to buy American food delivery company Postmates in a 2.65 billion dollars deal, reported Bloomberg citing people familiar with the matter.
Dominion Energy (D), an electricity and natural gas supplier, announced that it has agreed to sell all of its Gas Transmission & Storage segment assets to Berkshire Hathaway (BRK-A) in a transaction valued at 9.7 billion dollars. The company said it has authorized a share repurchase of up to 3 billion dollars using after-tax adjusted transaction proceeds. Separately, the company and Duke Energy (DUK) announced the cancellation of the Atlantic Coast Pipeline "due to ongoing delays and increasing cost uncertainty which threaten the economic viability of the project". Separately, Duke Energy announced a 56 billion dollars 5-year capital investment plan, "advancing its ambitious clean energy goals without the Atlantic Coast Pipeline by investing in renewables, battery storage, energy efficiency programs and grid projects".
Intel (INTC), a designer and manufacturer of microprocessors, was downgraded to "sell" from "neutral" at Goldman Sachs.
Netflix (NFLX), the video streaming service, was downgraded to "in-line" from "outperform" at Imperial Capital.
Spotify (SPOT), the music streaming specialist, was downgraded to "underperform" from "market perform" at Bernstein.
Tesla (TSLA)'s, the electric-vehicle maker, price target was raised to 1,500 dollars from 1,050 dollars at JMP Securities.
Source : TradingVIEW, Gain Capital
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.