



16 10 EU PRE OPEN
European stocks report | Rio Tinto | LVMH | Nestle | Volvo...
Share this:

INDICES
Yesterday, European stocks remained under pressure. The Stoxx Europe 600 Index slumped 2.08%, Germany's DAX 30 shed 2.49%, France's CAC 40 sank 2.11%, and the U.K.'s FTSE 100 was down 1.73%.
EUROPE ADVANCE/DECLINE
92% of STOXX 600 constituents traded lower or unchanged yesterday.
53% of the shares trade above their 20D MA vs 72% Wednesday (above the 20D moving average).
58% of the shares trade above their 200D MA vs 62% Wednesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 3.6pts to 26.84, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Industrial
3mths relative low: Insurance
Europe Best 3 sectors
real estate, travel & leisure, banks
Europe worst 3 sectors
energy, insurance, utilities
INTEREST RATE
The 10yr Bund yield fell 2bps to -0.58% (below its 20D MA). The 2yr-10yr yield spread rose 1bp to -16bps (above its 20D MA).
ECONOMIC DATA
EC 10:00: Aug Balance of Trade, exp.: E27.9B
EC 10:00: Sep Core Inflation Rate YoY final, exp.: 0.4%
EC 10:00: Sep Inflation Rate MoM final, exp.: -0.4%
EC 10:00: Sep Inflation Rate YoY final, exp.: -0.2%
MORNING TRADING
In Asian trading hours, EUR/USD remained subdued at 1.1703 and GBP/USD extended its decline to 1.2888. USD/JPY retreated to 105.26.
Spot gold slipped to $1,906 an ounce.
#UK - IRELAND#
Rio Tinto, a giant metals miner, released a 3Q production report: "Pilbara operations produced 86.4 million tonnes (Rio Tinto share 71.4 million tonnes) in the third quarter of 2020, 1% lower than the same period of 2019, and 4% higher than the previous quarter. (...) Third quarter shipments of 82.1 million tonnes (Rio Tinto share 67.6 million tonnes) were 5% lower than the third quarter of 2019 with significant planned maintenance activity affecting the port during the period."
J D Wetherspoon, a pub company, posted full-year results: "Total sales in the financial year were £1,262.0m, a decrease of 30.6%. Like-for-like sales decreased by 29.5%, having increased by 5.9% in the first half. (...) Earnings per share, including shares held in trust by the employee share scheme, before exceptional items, were -27.6p (2019: 75.5p). (...) The board is not proposing a final dividend payment for the year."
#FRANCE#
LVMH, a luxury goods conglomerate, announced that 3Q revenue dropped 10% on year (-7% organic growth) to 11.96 billion euros and 9-month revenue was down 21% (-21% organic growth) to 30.35 billion euros. The company said 3Q sales reflected "a marked improvement in trends compared to the first half, notably a return to growth in Cognac and Fashion & Leather Goods (+12% organic growth)". It also added that "the decision to pay an interim dividend will be discussed".
Eurofins Scientific, a bioanalytical testing company, announced a ten-for-one stock split, effective upon the listing on Euronext Paris of the new shares expected to occur on November 19.
Saint-Gobain, a building materials supplier, was downgraded to "neutral" from "buy" at Goldman Sachs.
#BENELUX#
Just Eat Takeaway, an online food order and delivery service provider, was upgraded to "buy" from "hold" at HSBC.
#SWITZERLAND#
Nestle, a food and drink processing conglomerate, has initiated the sale process for its 5 billion dollars North American water brands, reported Bloomberg citing people familiar with the matter.
#SWEDEN#
Volvo, a vehicle manufacturer, announced that 3Q net income declined 23% on year to 5.72 billion Swedish krona and adjusted operating income dropped 34% to 7.22 billion Swedish krona on net sales of 76.85 billion Swedish krona, down 22% (-16% currency adjusted). The company said: "Towards the end of the quarter transport activity was back on roughly the same level as a year ago in most markets. This led to an improved sentiment among our customers, which is reflected in increased order intake for trucks, engines and construction equipment as well as a gradually improving service business."
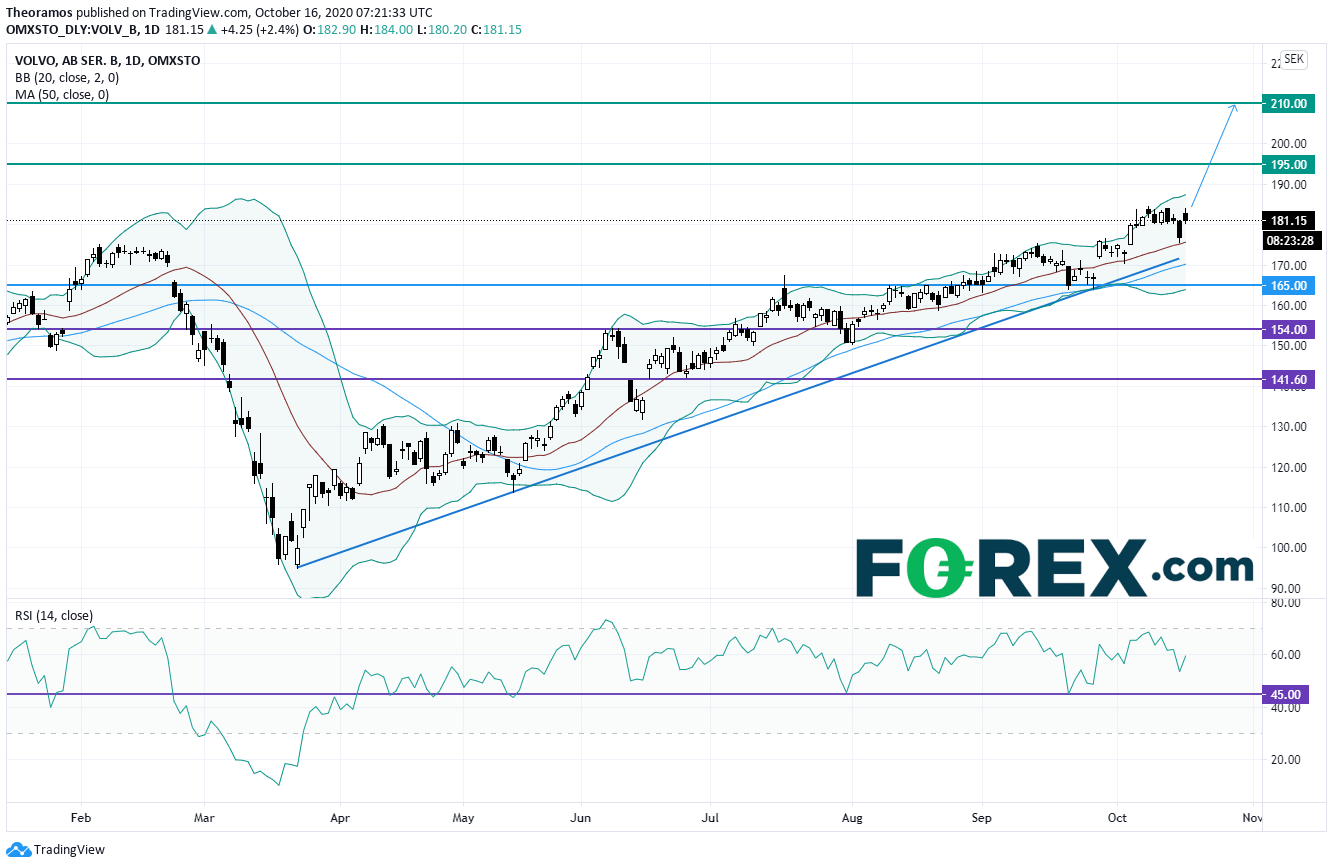
From a daily point of view, the stock is trading above a rising trend line drawn since March 2020. Furthermore, the 50 DMA is playing a support role, while the Relative Strenght Index is carried by the key support at 45%. Above 165SEK, targets are set at 195SEK and 210SEK in extension.
Source: TradingView, GAIN Capital
INDICES
Yesterday, European stocks remained under pressure. The Stoxx Europe 600 Index slumped 2.08%, Germany's DAX 30 shed 2.49%, France's CAC 40 sank 2.11%, and the U.K.'s FTSE 100 was down 1.73%.
EUROPE ADVANCE/DECLINE
92% of STOXX 600 constituents traded lower or unchanged yesterday.
53% of the shares trade above their 20D MA vs 72% Wednesday (above the 20D moving average).
58% of the shares trade above their 200D MA vs 62% Wednesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 3.6pts to 26.84, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Industrial
3mths relative low: Insurance
Europe Best 3 sectors
real estate, travel & leisure, banks
Europe worst 3 sectors
energy, insurance, utilities
INTEREST RATE
The 10yr Bund yield fell 2bps to -0.58% (below its 20D MA). The 2yr-10yr yield spread rose 1bp to -16bps (above its 20D MA).
ECONOMIC DATA
EC 10:00: Aug Balance of Trade, exp.: E27.9B
EC 10:00: Sep Core Inflation Rate YoY final, exp.: 0.4%
EC 10:00: Sep Inflation Rate MoM final, exp.: -0.4%
EC 10:00: Sep Inflation Rate YoY final, exp.: -0.2%
MORNING TRADING
In Asian trading hours, EUR/USD remained subdued at 1.1703 and GBP/USD extended its decline to 1.2888. USD/JPY retreated to 105.26.
Spot gold slipped to $1,906 an ounce.
#UK - IRELAND#
Rio Tinto, a giant metals miner, released a 3Q production report: "Pilbara operations produced 86.4 million tonnes (Rio Tinto share 71.4 million tonnes) in the third quarter of 2020, 1% lower than the same period of 2019, and 4% higher than the previous quarter. (...) Third quarter shipments of 82.1 million tonnes (Rio Tinto share 67.6 million tonnes) were 5% lower than the third quarter of 2019 with significant planned maintenance activity affecting the port during the period."
J D Wetherspoon, a pub company, posted full-year results: "Total sales in the financial year were £1,262.0m, a decrease of 30.6%. Like-for-like sales decreased by 29.5%, having increased by 5.9% in the first half. (...) Earnings per share, including shares held in trust by the employee share scheme, before exceptional items, were -27.6p (2019: 75.5p). (...) The board is not proposing a final dividend payment for the year."
#FRANCE#
LVMH, a luxury goods conglomerate, announced that 3Q revenue dropped 10% on year (-7% organic growth) to 11.96 billion euros and 9-month revenue was down 21% (-21% organic growth) to 30.35 billion euros. The company said 3Q sales reflected "a marked improvement in trends compared to the first half, notably a return to growth in Cognac and Fashion & Leather Goods (+12% organic growth)". It also added that "the decision to pay an interim dividend will be discussed".
Eurofins Scientific, a bioanalytical testing company, announced a ten-for-one stock split, effective upon the listing on Euronext Paris of the new shares expected to occur on November 19.
Saint-Gobain, a building materials supplier, was downgraded to "neutral" from "buy" at Goldman Sachs.
#BENELUX#
Just Eat Takeaway, an online food order and delivery service provider, was upgraded to "buy" from "hold" at HSBC.
#SWITZERLAND#
Nestle, a food and drink processing conglomerate, has initiated the sale process for its 5 billion dollars North American water brands, reported Bloomberg citing people familiar with the matter.
#SWEDEN#
Volvo, a vehicle manufacturer, announced that 3Q net income declined 23% on year to 5.72 billion Swedish krona and adjusted operating income dropped 34% to 7.22 billion Swedish krona on net sales of 76.85 billion Swedish krona, down 22% (-16% currency adjusted). The company said: "Towards the end of the quarter transport activity was back on roughly the same level as a year ago in most markets. This led to an improved sentiment among our customers, which is reflected in increased order intake for trucks, engines and construction equipment as well as a gradually improving service business."
From a daily point of view, the stock is trading above a rising trend line drawn since March 2020. Furthermore, the 50 DMA is playing a support role, while the Relative Strenght Index is carried by the key support at 45%. Above 165SEK, targets are set at 195SEK and 210SEK in extension.
Yesterday, European stocks remained under pressure. The Stoxx Europe 600 Index slumped 2.08%, Germany's DAX 30 shed 2.49%, France's CAC 40 sank 2.11%, and the U.K.'s FTSE 100 was down 1.73%.
EUROPE ADVANCE/DECLINE
92% of STOXX 600 constituents traded lower or unchanged yesterday.
53% of the shares trade above their 20D MA vs 72% Wednesday (above the 20D moving average).
58% of the shares trade above their 200D MA vs 62% Wednesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 3.6pts to 26.84, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Industrial
3mths relative low: Insurance
Europe Best 3 sectors
real estate, travel & leisure, banks
Europe worst 3 sectors
energy, insurance, utilities
INTEREST RATE
The 10yr Bund yield fell 2bps to -0.58% (below its 20D MA). The 2yr-10yr yield spread rose 1bp to -16bps (above its 20D MA).
ECONOMIC DATA
EC 10:00: Aug Balance of Trade, exp.: E27.9B
EC 10:00: Sep Core Inflation Rate YoY final, exp.: 0.4%
EC 10:00: Sep Inflation Rate MoM final, exp.: -0.4%
EC 10:00: Sep Inflation Rate YoY final, exp.: -0.2%
MORNING TRADING
In Asian trading hours, EUR/USD remained subdued at 1.1703 and GBP/USD extended its decline to 1.2888. USD/JPY retreated to 105.26.
Spot gold slipped to $1,906 an ounce.
#UK - IRELAND#
Rio Tinto, a giant metals miner, released a 3Q production report: "Pilbara operations produced 86.4 million tonnes (Rio Tinto share 71.4 million tonnes) in the third quarter of 2020, 1% lower than the same period of 2019, and 4% higher than the previous quarter. (...) Third quarter shipments of 82.1 million tonnes (Rio Tinto share 67.6 million tonnes) were 5% lower than the third quarter of 2019 with significant planned maintenance activity affecting the port during the period."
J D Wetherspoon, a pub company, posted full-year results: "Total sales in the financial year were £1,262.0m, a decrease of 30.6%. Like-for-like sales decreased by 29.5%, having increased by 5.9% in the first half. (...) Earnings per share, including shares held in trust by the employee share scheme, before exceptional items, were -27.6p (2019: 75.5p). (...) The board is not proposing a final dividend payment for the year."
#FRANCE#
LVMH, a luxury goods conglomerate, announced that 3Q revenue dropped 10% on year (-7% organic growth) to 11.96 billion euros and 9-month revenue was down 21% (-21% organic growth) to 30.35 billion euros. The company said 3Q sales reflected "a marked improvement in trends compared to the first half, notably a return to growth in Cognac and Fashion & Leather Goods (+12% organic growth)". It also added that "the decision to pay an interim dividend will be discussed".
Eurofins Scientific, a bioanalytical testing company, announced a ten-for-one stock split, effective upon the listing on Euronext Paris of the new shares expected to occur on November 19.
Saint-Gobain, a building materials supplier, was downgraded to "neutral" from "buy" at Goldman Sachs.
#BENELUX#
Just Eat Takeaway, an online food order and delivery service provider, was upgraded to "buy" from "hold" at HSBC.
#SWITZERLAND#
Nestle, a food and drink processing conglomerate, has initiated the sale process for its 5 billion dollars North American water brands, reported Bloomberg citing people familiar with the matter.
#SWEDEN#
Volvo, a vehicle manufacturer, announced that 3Q net income declined 23% on year to 5.72 billion Swedish krona and adjusted operating income dropped 34% to 7.22 billion Swedish krona on net sales of 76.85 billion Swedish krona, down 22% (-16% currency adjusted). The company said: "Towards the end of the quarter transport activity was back on roughly the same level as a year ago in most markets. This led to an improved sentiment among our customers, which is reflected in increased order intake for trucks, engines and construction equipment as well as a gradually improving service business."
From a daily point of view, the stock is trading above a rising trend line drawn since March 2020. Furthermore, the 50 DMA is playing a support role, while the Relative Strenght Index is carried by the key support at 45%. Above 165SEK, targets are set at 195SEK and 210SEK in extension.
Source: TradingView, GAIN Capital
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.