



Asia Morning US Indexes Dragged by Tech Giants
On Friday major U.S. stock indexes slid for a second session, pressured by lower share prices of technology giants...
Share this:

On Friday major U.S. stock indexes slid for a second session, pressured by lower share prices of technology giants.
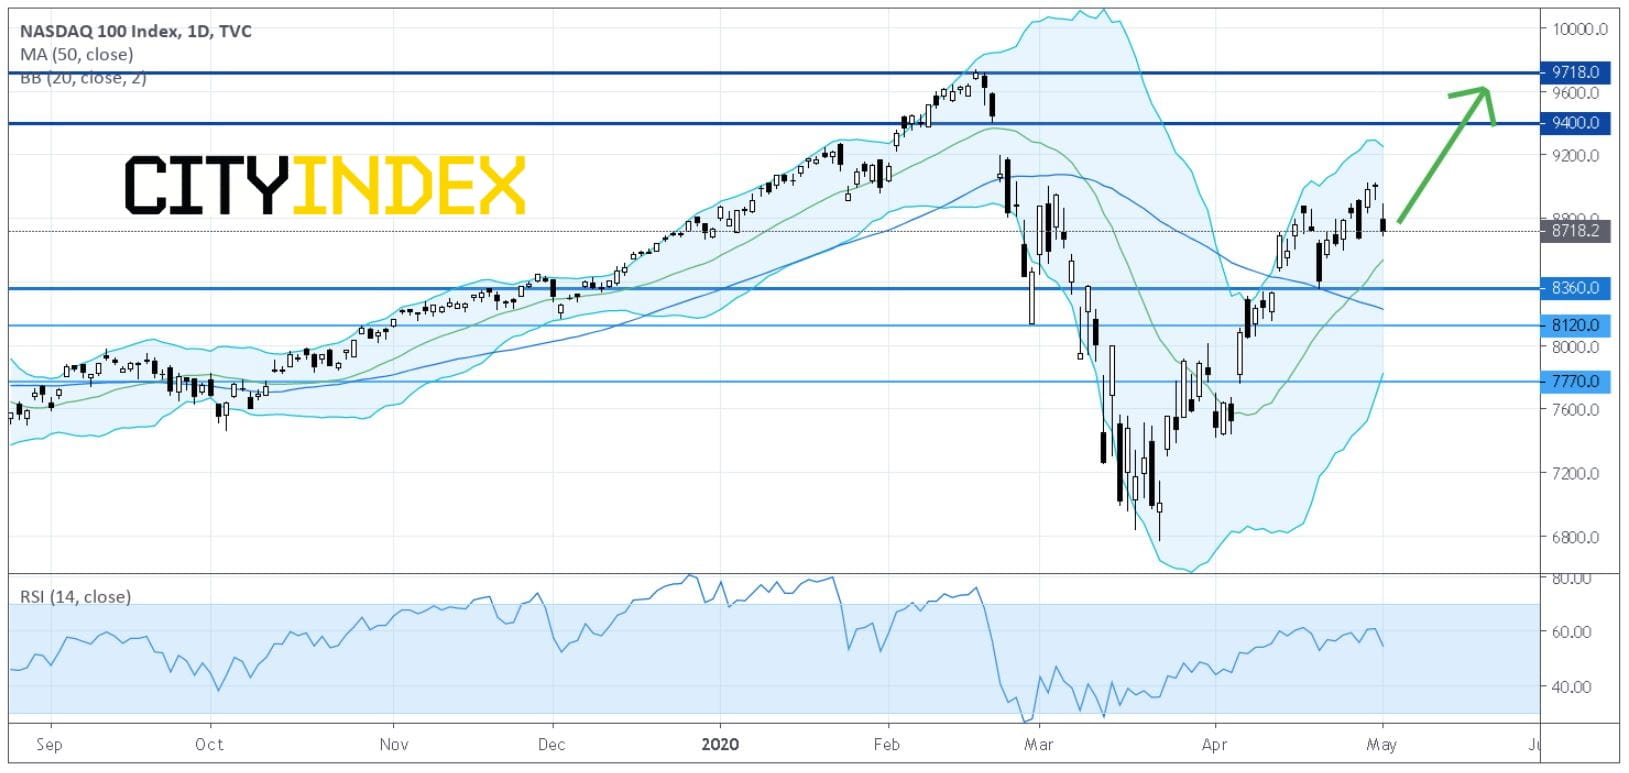
The Dow Jones Industrial Average fell 622 points (-2.6%) to 24,723, the S&P 500 dropped 81 points (-2.8%) to 2,830, and the Nasdaq 100 tumbled 282 points (-3.1%) to 8,718.
Energy (-6%), Automobiles & Components (-5.2%) and Retailing (-4.96%) sectors suffered the most significant losses.
Tesla (TSLA -10.3%), Amazon.com (AMZN -7.6%), Alphabet (GOOGL -2.2%) and Apple (AAPL -1.6%) showed weakness.
Berkshire Hathaway (BRKA -2.7%) reported a net loss of $49.7 billion in the first quarter. The Company's CEO and Chairman Warren Buffett said it has sold its entire stakes in the four major U.S. airlines - Delta Air Lines (DAL -6.9%), Southwest Airlines (LUV -6.5%), American Airlines (AAL -11.4%), and United Airlines (UAL -10.0%) - at a loss.
On the technical side, about 25.8% (31.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 83.2% (90.9% in the prior session) were above their 20-day moving average.
Regarding U.S. economic data, the Markit U.S. Manufacturing Purchasing Managers' Index (final reading) fell to 36.1 in April (36.7 expected), the lowest level on record. The Institute for Supply Management (ISM) Manufacturing PMI posted 41.5 for April (36.0 expected).
Construction Spending rose 0.9% on month in March (-3.5% expected).
Later today, U.S. official data on March Factory Orders (-9.2% on month expected) and Durable Goods Orders (final reading, -14.4% on month expected) will be reported.
European stocks remained heavy, with the Stoxx Europe 600 Index dropping 0.8%. Germany's DAX fell 2.2%, France's CAC lost 2.1%, and the U.K.'s FTSE 100 was down 2.3%.
U.S. Treasury prices eased, as the benchmark 10-year U.S. Treasury yield stepped up to 0.641% from 0.619% Thursday.
Spot gold rebounded 12 dollars or 0.7% to $1,698 an ounce.
Oil prices bounced further on expectations that demand would rebound sharply as global economies reopen from coronavirus-induced lockdowns. U.S. WTI crude oil futures (June) rose 5.0% to $19.78 a barrel, and Brent crude oil futures added 4.6% to $26.44 a barrel.
The Dow Jones Industrial Average fell 622 points (-2.6%) to 24,723, the S&P 500 dropped 81 points (-2.8%) to 2,830, and the Nasdaq 100 tumbled 282 points (-3.1%) to 8,718.
Source: GAIN Capital, TradingView
Energy (-6%), Automobiles & Components (-5.2%) and Retailing (-4.96%) sectors suffered the most significant losses.
Tesla (TSLA -10.3%), Amazon.com (AMZN -7.6%), Alphabet (GOOGL -2.2%) and Apple (AAPL -1.6%) showed weakness.
Berkshire Hathaway (BRKA -2.7%) reported a net loss of $49.7 billion in the first quarter. The Company's CEO and Chairman Warren Buffett said it has sold its entire stakes in the four major U.S. airlines - Delta Air Lines (DAL -6.9%), Southwest Airlines (LUV -6.5%), American Airlines (AAL -11.4%), and United Airlines (UAL -10.0%) - at a loss.
On the technical side, about 25.8% (31.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 83.2% (90.9% in the prior session) were above their 20-day moving average.
Regarding U.S. economic data, the Markit U.S. Manufacturing Purchasing Managers' Index (final reading) fell to 36.1 in April (36.7 expected), the lowest level on record. The Institute for Supply Management (ISM) Manufacturing PMI posted 41.5 for April (36.0 expected).
Construction Spending rose 0.9% on month in March (-3.5% expected).
Later today, U.S. official data on March Factory Orders (-9.2% on month expected) and Durable Goods Orders (final reading, -14.4% on month expected) will be reported.
European stocks remained heavy, with the Stoxx Europe 600 Index dropping 0.8%. Germany's DAX fell 2.2%, France's CAC lost 2.1%, and the U.K.'s FTSE 100 was down 2.3%.
U.S. Treasury prices eased, as the benchmark 10-year U.S. Treasury yield stepped up to 0.641% from 0.619% Thursday.
Spot gold rebounded 12 dollars or 0.7% to $1,698 an ounce.
Oil prices bounced further on expectations that demand would rebound sharply as global economies reopen from coronavirus-induced lockdowns. U.S. WTI crude oil futures (June) rose 5.0% to $19.78 a barrel, and Brent crude oil futures added 4.6% to $26.44 a barrel.
On Friday major U.S. stock indexes slid for a second session, pressured by lower share prices of technology giants.
The Dow Jones Industrial Average fell 622 points (-2.6%) to 24,723, the S&P 500 dropped 81 points (-2.8%) to 2,830, and the Nasdaq 100 tumbled 282 points (-3.1%) to 8,718.

Energy (-6%), Automobiles & Components (-5.2%) and Retailing (-4.96%) sectors suffered the most significant losses.
Tesla (TSLA -10.3%), Amazon.com (AMZN -7.6%), Alphabet (GOOGL -2.2%) and Apple (AAPL -1.6%) showed weakness.
Berkshire Hathaway (BRKA -2.7%) reported a net loss of $49.7 billion in the first quarter. The Company's CEO and Chairman Warren Buffett said it has sold its entire stakes in the four major U.S. airlines - Delta Air Lines (DAL -6.9%), Southwest Airlines (LUV -6.5%), American Airlines (AAL -11.4%), and United Airlines (UAL -10.0%) - at a loss.
On the technical side, about 25.8% (31.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 83.2% (90.9% in the prior session) were above their 20-day moving average.
Regarding U.S. economic data, the Markit U.S. Manufacturing Purchasing Managers' Index (final reading) fell to 36.1 in April (36.7 expected), the lowest level on record. The Institute for Supply Management (ISM) Manufacturing PMI posted 41.5 for April (36.0 expected).
Construction Spending rose 0.9% on month in March (-3.5% expected).
Later today, U.S. official data on March Factory Orders (-9.2% on month expected) and Durable Goods Orders (final reading, -14.4% on month expected) will be reported.
European stocks remained heavy, with the Stoxx Europe 600 Index dropping 0.8%. Germany's DAX fell 2.2%, France's CAC lost 2.1%, and the U.K.'s FTSE 100 was down 2.3%.
U.S. Treasury prices eased, as the benchmark 10-year U.S. Treasury yield stepped up to 0.641% from 0.619% Thursday.
Spot gold rebounded 12 dollars or 0.7% to $1,698 an ounce.
Oil prices bounced further on expectations that demand would rebound sharply as global economies reopen from coronavirus-induced lockdowns. U.S. WTI crude oil futures (June) rose 5.0% to $19.78 a barrel, and Brent crude oil futures added 4.6% to $26.44 a barrel.
The Dow Jones Industrial Average fell 622 points (-2.6%) to 24,723, the S&P 500 dropped 81 points (-2.8%) to 2,830, and the Nasdaq 100 tumbled 282 points (-3.1%) to 8,718.
Source: GAIN Capital, TradingView
Energy (-6%), Automobiles & Components (-5.2%) and Retailing (-4.96%) sectors suffered the most significant losses.
Tesla (TSLA -10.3%), Amazon.com (AMZN -7.6%), Alphabet (GOOGL -2.2%) and Apple (AAPL -1.6%) showed weakness.
Berkshire Hathaway (BRKA -2.7%) reported a net loss of $49.7 billion in the first quarter. The Company's CEO and Chairman Warren Buffett said it has sold its entire stakes in the four major U.S. airlines - Delta Air Lines (DAL -6.9%), Southwest Airlines (LUV -6.5%), American Airlines (AAL -11.4%), and United Airlines (UAL -10.0%) - at a loss.
On the technical side, about 25.8% (31.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 83.2% (90.9% in the prior session) were above their 20-day moving average.
Regarding U.S. economic data, the Markit U.S. Manufacturing Purchasing Managers' Index (final reading) fell to 36.1 in April (36.7 expected), the lowest level on record. The Institute for Supply Management (ISM) Manufacturing PMI posted 41.5 for April (36.0 expected).
Construction Spending rose 0.9% on month in March (-3.5% expected).
Later today, U.S. official data on March Factory Orders (-9.2% on month expected) and Durable Goods Orders (final reading, -14.4% on month expected) will be reported.
European stocks remained heavy, with the Stoxx Europe 600 Index dropping 0.8%. Germany's DAX fell 2.2%, France's CAC lost 2.1%, and the U.K.'s FTSE 100 was down 2.3%.
U.S. Treasury prices eased, as the benchmark 10-year U.S. Treasury yield stepped up to 0.641% from 0.619% Thursday.
Spot gold rebounded 12 dollars or 0.7% to $1,698 an ounce.
Oil prices bounced further on expectations that demand would rebound sharply as global economies reopen from coronavirus-induced lockdowns. U.S. WTI crude oil futures (June) rose 5.0% to $19.78 a barrel, and Brent crude oil futures added 4.6% to $26.44 a barrel.
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.