




AUD/USD, ASX 200 Analysis: Asian Open – 21st June 2023
Share this:

Market summary
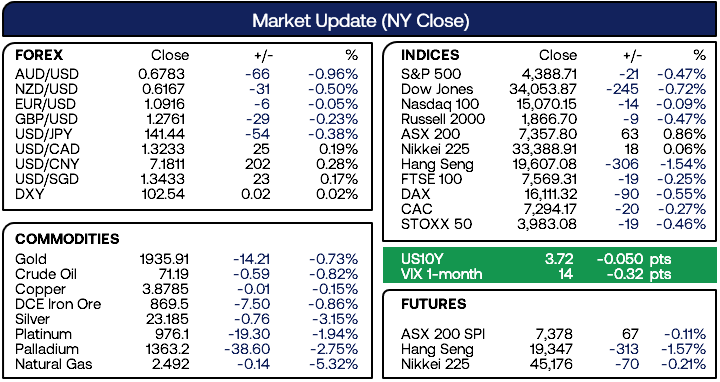
- The RBA released the minutes of the meeting from their June hike, with traders latching on to the debate between a pause or a hike being ‘finely balanced’ (as opposed to an outright hike), sending AUD pairs and AU bond yields broadly lower
- AUD/USD beneath 68c (and the ‘RBA-pause highs) and the ASX 200 rose for a seventh day
- Yet the threat of further hikes seem apparent to my eyes, with Westpac, NAB and ANZ on par with a July hike – which makes next week’s inflation data the more important
- RBA assistant governor Bullock sounded hawkish overall, saying employment is too tight for their inflation target, economy would be more ‘balanced’ with 4.5% unemployment (currently 3.6%), economy needs to grow below trend for a while, need to slow demand (which migration is adding to) and higher rates are the only tool the RBA has to curb inflation
- US housing data is surpassing expectations with builders confidence moving into positive territory in June ad housing starts rising 21.7% m/m (or 5.7% y/y), which is good news for those hoping for a soft landing (although it is also inflationary)
- The PBOC provided further stimulus for China’s economy by cutting the 1-year prime loan rate by 10bp
- South Korean producer prices contracted -0.3% in May for its second month of deflation (good news for trade partners and consumers)
- The S&P 500 retraced for a second day as investors booked profits after a strong run, ahead of Jerome Powell’s testimony to congress
Events in focus (AEDT):
- 09:50 – BOJ minutes of the meeting
- 16:00 – UK inflation report
- 00:00 – Jerome Powell testifies to congress (prepared remarks are usually released ahead of the event, which then leaves the Q+A as another potential market driver

ASX 200 at a glance:
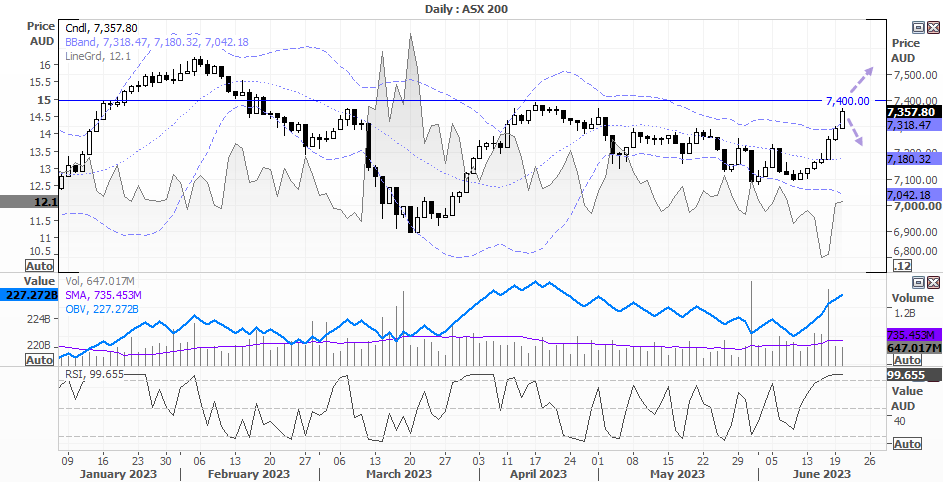
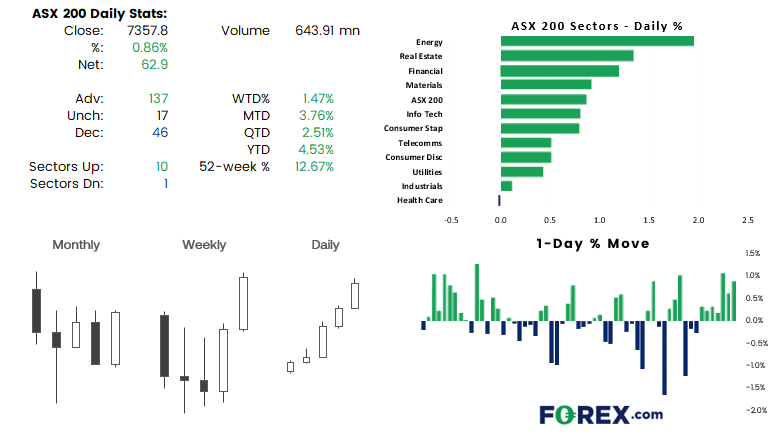
- The ASX 200 rallied for a seventh consecutive day
- 10 of its 11 sectors were higher on the day
- However, RSI (2) has been overbought for four days
- And 7400 / April high overhead, the index appears likely headed for a pause in trend or a retracement
- Beyond that, OBV (on balance volume) shows support for the rally overall

AUD/USD 1-hour chart:
Clearly, AUD/USD did not provide any meaningful technical bounce from the 68c support zone, as prices broke through the key support area as it tracked bond yields lower. But it has rebounded from prior cycle lows just above 0.6750 and now hovers just beneath the daily pivot point and 68c handle whilst sitting in between the ‘RBA-pause’ daily high and open. We now need to see the market tip its hand, with a break beneath 0.6778 suggesting another crack at 0.6750, but we’d prefer to wait for a break above 0.6805 before assuming a move higher towards the daily R1 resistance zone.


-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.