



Asian Open: Commodities weigh on commodity FX, ASX set to mean revert?
Commodities were broadly lower overnight ahead of highly anticipated peace talks between Ukraine and Russia, dragging NZD and AUD lower along the way.
Share this:

Monday US cash market close:
- The Dow Jones Industrial rose 233.09 points (0.27%) to close at 34,955.89
- The S&P 500 index rose 32.46 points (2.51%) to close at 34,058.75
- The Nasdaq 100 index rose 233.094 points (1.58%) to close at 14,987.40
Asian futures:
- Australia's ASX 200 futures are down 0 points (-0.07%), the cash market is currently estimated to open at 7,412.40
- Japan's Nikkei 225 futures are up 310 points (1.12%), the cash market is currently estimated to open at 28,253.89
- Hong Kong's Hang Seng futures are up 48 points (0.22%), the cash market is currently estimated to open at 21,732.97
- China's A50 Index futures are up 59 points (0.44%), the cash market is currently estimated to open at 13,479.67
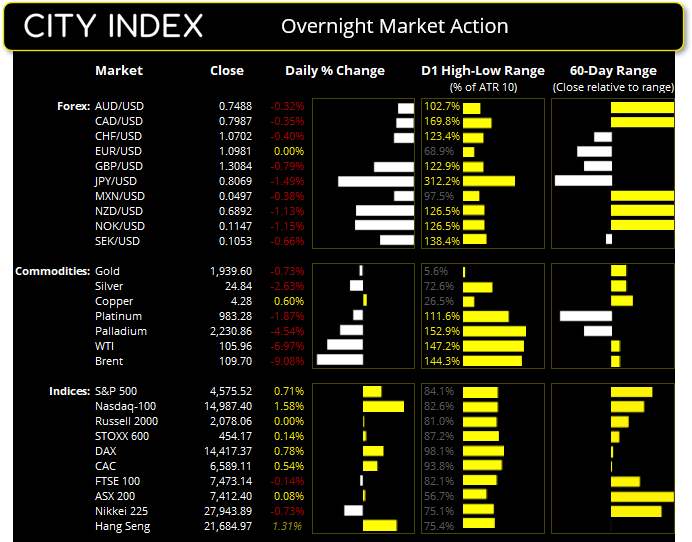
Wall Street continued to climb despite higher interest rates. Yet dwindling volume with higher prices suggests the rally could be related to short covering as opposed to the initiation of fresh bullish bets. The S&P 500 is not less than a day’s trade from out 4600 target. Tech stocks led the advance and the Nasdaq 100 rose 1.6% to close just shy of 15,000.
ASX 200:


The ASX 200 is grinding higher but a bit of mean reversion almost seems inevitable. Yesterday’s bearish pinbar closed within the upper keltner band following a failed break above it earlier in the session. And half of Friday’s bullish session was the upper wick, which ultimately shows a change in mind at the high of the day. Whether that merits a countertrend trade is up for debate, but we would urge caution at these levels for bulls. And there would be nothing wrong with stepping aside and waiting to see if mean reversion kicks in, then seeking fresh longs around support zones such as 7340/58.
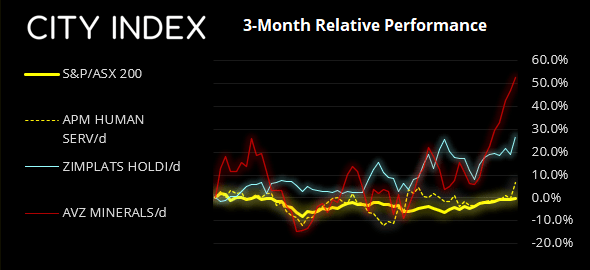
ASX 200: 7412.4 (0.08%), 28 March 2022
- Materials (1.29%) was the strongest sector and Info Tech (-2.67%) was the weakest
- 4 out of the 11 sectors closed higher
- 7 out of the 11 sectors closed lower
- 4 out of the 11 sectors outperformed the index
- 79 (39.50%) stocks advanced, 110 (55.00%) stocks declined
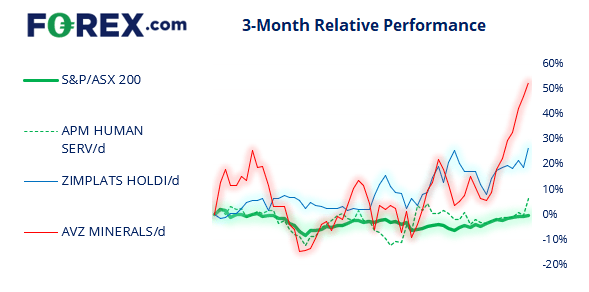
Outperformers:
- +7.04% - APM Human Services International Ltd (APM.AX)
- +6.58% - Zimplats Holdings Ltd (ZIM.AX)
- +3.95% - AVZ Minerals Ltd (AVZ.AX)
Underperformers:
- -6.02% - Paladin Energy Ltd (PDN.AX)
- -5.35% - Lake Resources NL (LKE.AX)
- -5.16% - Xero Ltd (XRO.AX)
Gold-demand dented ahead of peace talks
Currently down around -2%, its has been gold’s worst day in two weeks. Safe-haven demand has taken a knock ahead of peace talks which will be the first in two weeks. And it is worth noting that gold hit a low two weeks ago when it became apparent that peace talks did not live up to expectations. Given that Putin seems unwilling to compromise to end the war, we may find gold hits bid again if peace talks fail to live up to their name. Prices are holding above the June 2021 high of 1916 and it remains a key level to watch today. A daily close below 1900 would be constructive for a bear case.
WTI falls to a 5-day low
Oil prices fell over -8% yesterday during its worst day in 13. And that day would take some beating, given prices plunged up to -22% in a single session. And such levels of volatility may help explain why net-long exposure on WTI futures has fallen for a third week as it wreaks havoc on portfolios which just seek nice and steady returns.
BOE and BOJ send their currencies lower
The yen continued to fall in spectacular fashion after the BOJ announced they’ll buy an “unlimited” amount of bonds to maintain their yield curve control. This only further widened yield differentials and allowed USD/JPY to rise above 123 to a fresh 6-year high. It seems only a matter of time before we hear thinly veiled threats of FX intervention fore the yen.
The British pound was lower against the euro and US dollar as BOE governor reiterated their less-hawkish stance presented at their last meeting. GBP/USD fell to an 8-day low and suggests a corrective high was seen on Wednesday. EUR/GBP also broke above Friday’s bearish hammer which has invalidated our bearish bias outlined in Friday’s and yesterday’s report.
Weak commodity markets weighed on commodity FX but, in particular, the New Zealand dollar. NZD/USD fell over -1.1% during its worst session in a month. AUD/NZD had its most bullish day in two-moths and broke above key resistance to touch a 1-year high. We expect dips above 1.0812 to be bought, in line with its dominant trend.
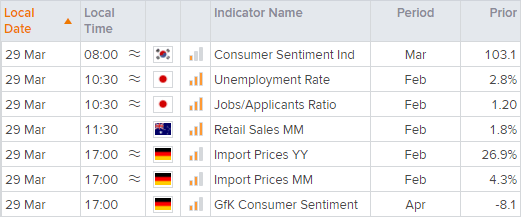
Up Next (Times in AEDT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.