



DAX forecast: German equities close in on record territory
European equities pushed higher this morning, joining the global rally. Investors are balancing ongoing geopolitical uncertainty in the Middle East against the relentless strength of the global technology sector. While European benchmarks have lagged behind Wall Street’s technology-led advance for much of the year, it appears like other areas of the market are catching up a little as risk appetite returns.
Share this:
European equities pushed higher this morning, joining the global rally. Investors are balancing ongoing geopolitical uncertainty in the Middle East against the relentless strength of the global technology sector. While European benchmarks have lagged behind Wall Street’s technology-led advance for much of the year, it appears like other areas of the market are catching up a little as risk appetite returns. We maintain a bullish DAX forecast, barring a major escalation in the US-Iran tensions.
DAX could be heading to new highs
The technology rally remains the dominant force across global markets. The Nasdaq 100 continues to register fresh record highs, while major Asian benchmarks in Japan and South Korea have also climbed to historic levels in recent weeks. European markets are now beginning to participate more fully in the broader equity advance, with the DAX once again approaching record territory.
A key factor supporting sentiment has been the recent decline in oil prices. Investors appear increasingly confident that, despite recent setbacks, Washington and Tehran will eventually find a diplomatic path forward. While negotiations remain unpredictable, the market is placing greater weight on the prospect of a future agreement than on the latest setbacks in talks.
Inflation concerns fail to derail equity momentum
The retreat in crude prices has helped soothe concerns that geopolitical tensions could trigger another inflation shock. Even as conflict in the Middle East has generated volatility across energy markets, investors have largely looked through the risks and maintained their focus on corporate earnings and economic resilience.
That confidence was tested slightly by the latest eurozone inflation figures. Core consumer prices rose by 2.5% year-on-year in May, marginally above expectations and up from 2.2% previously. Headline inflation matched forecasts at 3.2%.
With the next European Central Bank meeting approaching, the inflation data reinforces the case for policymakers to tighten their policy. The rise in price pressures reflects the earlier surge in energy costs stemming from US-Iran tensions.
Inflation in the euro area has now accelerated steadily from 2.6% in March to 3.0% in April and 3.2% in May, leaving it comfortably above the ECB’s 2% target. Given Europe’s heavy reliance on imported energy, the region remains particularly exposed to fluctuations in oil and gas markets.
Financial markets continue to anticipate a 25-basis-point interest rate increase from the ECB at its upcoming meeting, with investors viewing such a move as a precautionary step rather than the start of an aggressive tightening cycle.
Technology optimism continues to dominate
Despite geopolitical headlines and concerns over monetary policy, the investment narrative remains centred on artificial intelligence and the broader technology sector.
Investors continue to view AI-driven spending as one of the most powerful growth themes in global markets. Strong earnings from major technology companies have reinforced confidence that the current investment cycle still has room to run, even as valuations in parts of the sector remain stretched by historical standards.
For now, equity investors appear willing to overlook both geopolitical risks and valuation concerns. Whether that confidence ultimately proves justified will be one of the defining questions for markets over the second half of the year.
German equities are benefiting not only from improving global sentiment but also from domestic fiscal support. Germany’s substantial infrastructure and defence spending programme continues to provide a favourable backdrop for sectors such as industrials, construction and utilities, helping to offset otherwise subdued economic growth.
Technical DAX forecast: resistance levels coming into focus
From a technical perspective, the DAX forecast remains constructive. The index has demonstrated impressive resilience throughout the recent period of geopolitical uncertainty and has continued to build on its sequence of higher lows.
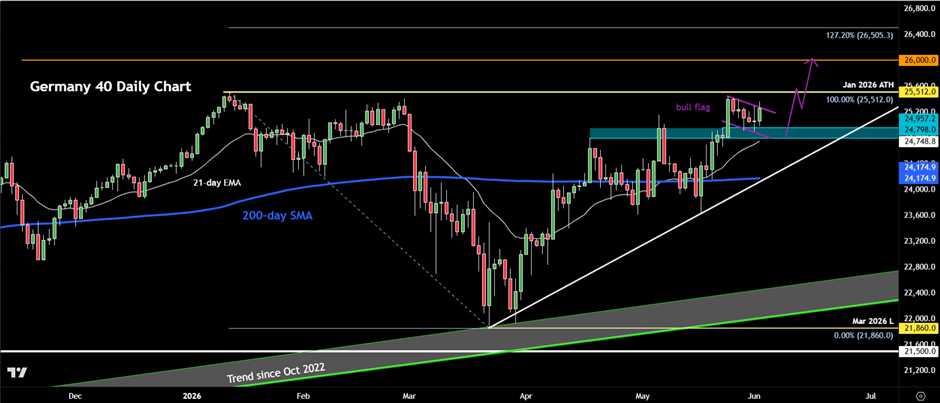
The recovery above the psychologically important 25,000 level reinforced the bullish structure and has encouraged further buying interest. As long as the index remains above this threshold, traders are likely to maintain a positive bias.
On the upside, the first area of resistance sits around 25,400, followed closely by the previous record high near 25,512. A decisive break above those levels would open the door towards the next major psychological milestone at 26,000.
Support remains concentrated around the 25,000 area, which now serves as an important pivot for the broader trend. Additional near-term support can be found around 25,180 and 25,100 should profit-taking emerge.
Looking ahead, the key question is whether investors continue to buy market dips as geopolitical tensions gradually ease and technology-led optimism remains intact. Unless a fresh escalation in the Middle East triggers a meaningful shift in sentiment, the path of least resistance for the DAX continues to point higher.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
The RBA Hiked Rates and the Australian Dollar Still Fell
AUD/USD fell after the RBA rate hike because the central bank's hawkish stance was already priced in while the U.S. dollar stayed firm.

EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.

AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.