



DAX forecast: Stocks drop but all is not lost
European markets were lower across the board in a risk off trade this morning. The risk off tone gathered momentum following yesterday’s reversal on Wall Street. European indices and US futures fell a further 0.5 to 1.5 percent while safe haven gold got to within $20 from reaching $4,400, before easing back a little to still hold around 8% weekly gains at the time of writing.
Share this:
European markets were lower across the board in a risk off trade this morning. The risk off tone gathered momentum following yesterday’s reversal on Wall Street. European indices and US futures fell a further 0.5 to 1.5 percent while safe haven gold got to within $20 from reaching $4,400, before easing back a little to still hold around 8% weekly gains at the time of writing. Cryptos also fell alongside risk assets with Bitcoin plunging below $105K after taking out a key support around $110K yesterday. As well as ongoing trade war uncertainty between the US and China, sluggish global growth and stretched valuations, credit risk in US regional banks has added to the list of growing worries. But all it would take is a social media post by Trump to flip trigger a bullish reversal in risk appetite. For that reason, I am a bit sceptical whether this will turn into a sharp correction. Dip-buying has been a key theme in stock markets throughout 2025 and I expect that to continue. The DAX forecast remains bullish for now.
DAX forecast remains positive despite the drop
There are reasons to be cheerful for European stock market investors, even if economic conditions are grim in Germany at the moment. A French political breakthrough, weaker oil prices, and firming expectations that the Fed will deliver two rate cuts before year-end should all mean downside is limited for stocks. But more to the point, Germany’s major fiscal stimulus worth €500 billion in infrastructure spending alone plus around another €500 for spending and defence projects should help the Eurozone’s economy grow, and provide a positive backdrop for stock markets.
The real drag on the DAX in the last couple of days has all been to do with the wider risk sentiment but data, too, has been weak for the eurozone’s largest economy, from weaker industrial output to fading consumer sentiment. The data has been soft enough to keep the ECB’s dovish camp in control who would be eyeing potentially one more cut next year.
German stimulus: a slow-burn catalyst
Berlin’s multi-year spending plan — which breaks the country’s self-imposed debt ceiling — could mark a structural turning point for Europe. Nearly €1 trillion in planned investment for defence, infrastructure, and green projects may not hit the economy immediately, but the shift in fiscal stance is already reshaping sentiment.
Germany’s deficit is expected to swell from €41 billion to €143 billion this year — a meaningful expansion after years of restraint. While the real economic impact will likely unfold from 2026 onward, the broader narrative is positive for the DAX forecast. It signals a more growth-oriented Europe. In the near term, though, traders remain cautious until they see spending translate into tangible growth data, while keeping a close eye on the US-China trade talks.
Across the broader, France added a welcome dose of calm yesterday. Prime Minister Sébastien Lecornu surviving a second no-confidence vote has helped steady investor nerves and restore confidence in French assets. For the euro, it’s another reason to stay bid, but so far we haven’t seen that translate into a rebounding stock markets. Could that change, though, as the DAX tests a key support area near 23,700?
Technical DAX forecast and key levels to watch
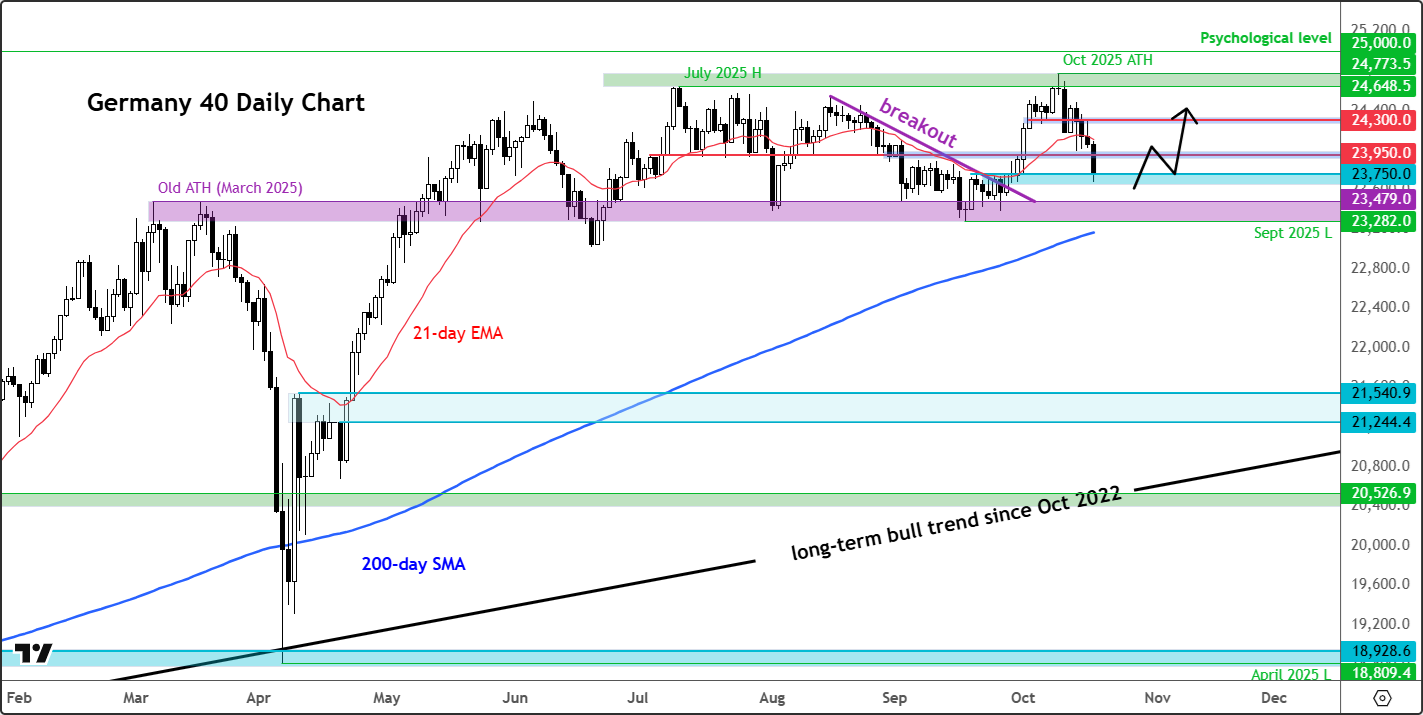
I didn’t expect the DAX to pullback this deep after breaking to a new high just last week following a lengthy consolidation. But pull deep it has done, making us a little more concerned about the strength of the market. Still, we are giving the bulls the benefit of the doubt with the DAX now testing a key infliction point near 23700-23750 area as highlighted in blue on the chart. This area was the breakout zone a couple of weeks ago. Can we see another rally away from here? Below this zone, the purple area around 23280-23480 is the next major support zone. Resistance meanwhile is seen around 23950, then 24300. But if these levels break then a new wave of selling could commence towards the 25K handle. That’s my base case scenario and will therefore maintain a bullish DAX forecast from a technical standpoint.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.