

DAX Reclaims Momentum Ahead of US Inflation and Key Earnings
The DAX has started the week on a stronger footing, recovering from last week's technology-driven selloff and pushing back toward the key 26,000 level. Improving sentiment across global markets, easing oil prices and a positive reassessment of technology valuations have helped support the rebound. Attention now shifts to Tuesday's US inflation report and a busy earnings calendar, both of which will determine whether the recovery can extend further.
Share this:
DAX Market Brief — Monday, 9 November 2026
The DAX is opening the week firmly higher, recovering from last week’s AI-led selloff. At 10:40 CET, the index traded at 25,965 points, up 293 points or 1.14%, after opening at 25,648.60 and reaching an intraday high of 25,996.50.
The recovery is broad. The Euro Stoxx 50 is up 1.15% at 6,215.50, the STOXX Europe 600 has gained 0.47% to 651.36, the CAC 40 is higher by 0.19% at 8,154.83, and the FTSE 100 has added 0.48% to 10,724.86. Investors appear to be re-engaging with European risk assets after last week’s volatility.
DAX technicals and German data
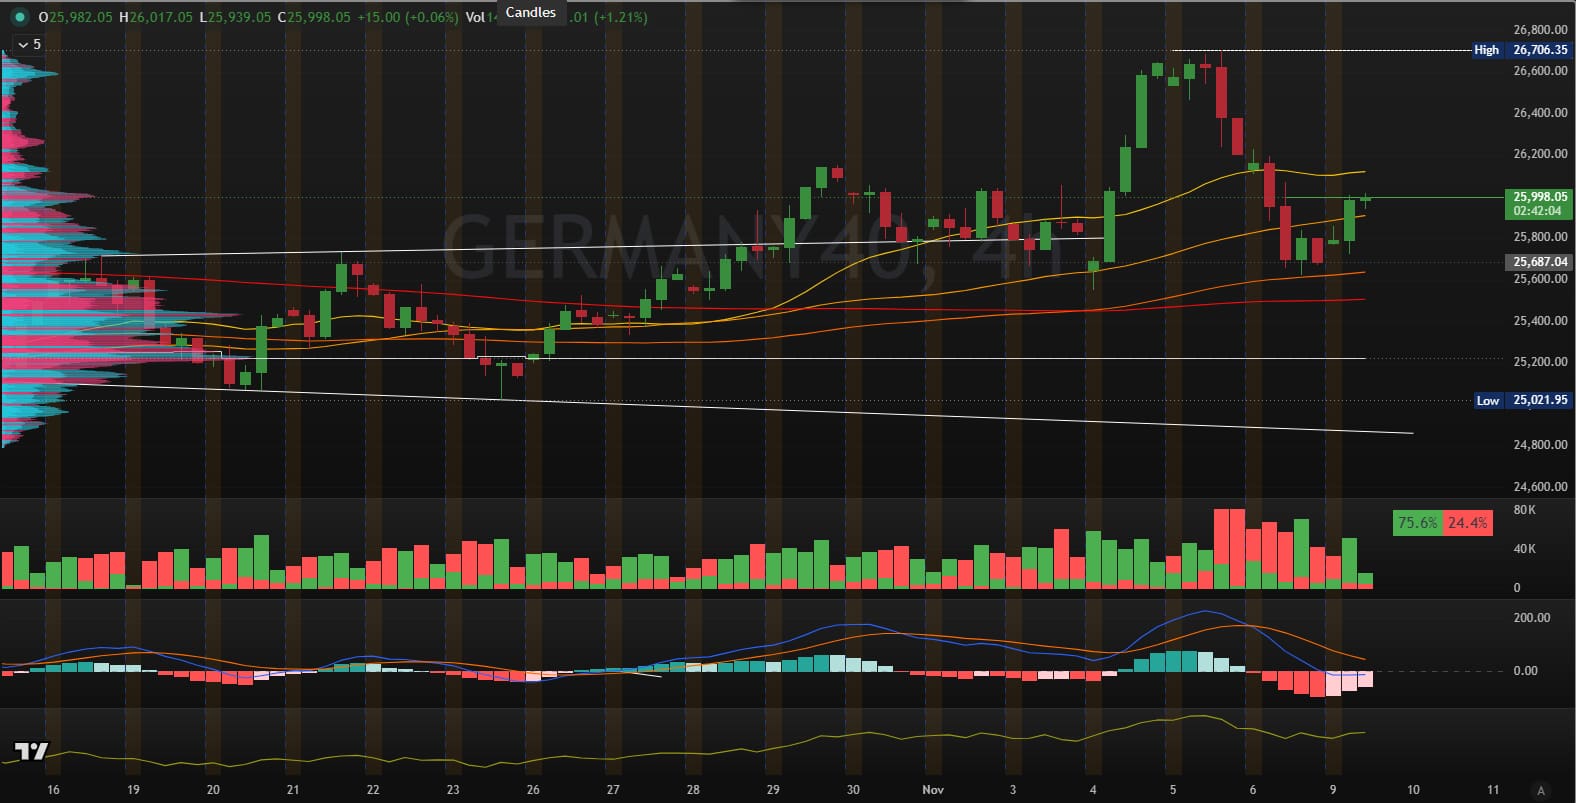
Technically, the DAX is attempting to reclaim the 26,000 psychological level after closing Friday at 25,672. The index opened near that closing level, dipped to 25,645.30, then rallied strongly toward 25,996.50.
- Immediate support: 25,645–25,672, today’s low and Friday’s close.
- Key resistance: 25,996–26,000, the intraday high and psychological barrier.
- Confirmation level: A sustained move above 26,000 would signal that last week’s AI-driven correction could be absorbed.
- Next upside reference: The DAX’s recent recovery highs, with the market still well below its all-time high after last week’s pullback.
The German macro backdrop is improving, though not uniformly. September exports rose 2.0% month-on-month to €141.1 billion, while imports increased 4.2% to €125.5 billion. As a result, the trade surplus narrowed to €15.6 billion from €17.9 billion in August.
For German industrials, this suggests that manufacturers are finding external demand even as domestic conditions remain uneven. However, the faster rise in imports also shows continuing cost pressure and supply-chain activity, which can limit the improvement in the trade balance.
The week ahead is also important for German corporate earnings. Twelve of the 40 DAX constituents are scheduled to report, including Infineon, Siemens Energy, E.ON, RWE, Allianz and Siemens. Final October eurozone inflation is also expected to confirm the preliminary 2.8% year-on-year rate.
World markets: Asia and the US
Asia is also rebounding after last week’s sharp technology-led selloff. The MSCI index of Asia-Pacific shares excluding Japan rose 0.8% in early trading, while Taiwan’s benchmark jumped more than 6% after suffering its steepest weekly decline in two decades last week.
Japan’s Nikkei 225 closed 2.33% higher at 58,775.50, recovering part of Friday’s 6% slump. But the index still remains more than 20% below its June record, however the rebound shows that investors are willing to re-enter technology exposure once the initial panic subsides.
US equity futures are also firmer. S&P 500 e-minis are up around 0.6%, while Nasdaq 100 futures gained roughly 0.59%. The market appears to be attempting to stabilise after the Nasdaq fell 5.5% on Thursday and entered correction territory, with the Philadelphia semiconductor index plunging 12% to a six-month low before rebounding more than 4% on Friday.
But macro factors show challenging times. October US payrolls rose by 165,000, more than double the expected 65,000, while unemployment fell to 4.1% and wage growth held at 3.1%. That has lifted the probability of a Federal Reserve rate hike in December to nearly 80% from previously 70%, according to CME FedWatch.
On the front of Oil: Oil is easing, which is supportive for inflation expectations. Brent crude fell to about $96.38–$98.20 per barrel after President Donald Trump indicated that he was highly unlikely to order fresh strikes on Iran while diplomatic talks progress.
Corporate news: SAP leads the DAX
SAP is the standout corporate story this morning. The shares rose 2.1% to €215.15 after JPMorgan upgraded the stock from Neutral to Overweight and raised its price target from €175 to €275, implying roughly 30% upside from the prior close.
The upgrade is significant because SAP had been one of the main casualties of the AI-regulation concerns last week. JPMorgan’s bullish view is supported by SAP’s cloud backlog, which grew 26% in the third quarter and has beaten expectations for three consecutive quarters.
That makes SAP a useful test case for the broader market. If investors are willing to buy a high-multiple German software company on an upgraded outlook, it could suggest the AI selloff is being treated as a valuation reset rather than the beginning of a structural downturn.
Elsewhere, the earnings calendar will be decisive. Infineon, Siemens Energy, E.ON, RWE, Allianz and Siemens are among the DAX companies reporting this week. Their results will determine whether the market continues to reward industrial and energy-transition exposure or remains focused on AI-policy risk.
Outlook: what to watch this week
The immediate focus is whether the DAX can hold above 25,800 and then stay above 26,000. A close above 26,000 would be the first clear confirmation that last week’s AI-led correction can stabilize in the near term.
The key macro event for this week is Tuesday’s US CPI release. A softer inflation print could ease pressure on the Federal Reserve and support global equities, while another hot reading would reinforce expectations of a December rate hike and could renew pressure on high-multiple technology names.
Corporate earnings will also shape the direction. Results from CoreWeave, Cisco and Applied Materials will provide a direct read on AI infrastructure demand, while German results from Infineon, Siemens Energy, E.ON, RWE, Allianz and Siemens will show whether European industrials can sustain their momentum.
Bottom line
The DAX is entering the week with a constructive setup. The index is recovering from last week’s AI-led selloff, German export data are improving, and SAP’s upgrade shows that some are still willing to reward companies with visible earnings momentum.
Trade safe.
Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US CPI Preview: Will Inflation Fall Enough to Put a Fed Hike in Doubt?
A CPI reading that comes in above, or even at, consensus expectations this month would keep the FOMC on track to hike, so only a notable downside surprise would be likely to drive significant market volatility - what does that mean for the US Dollar?
S&P 500 Forecast: SPX rises despite Nvidia’s decline
U.S. stocks are rising, extending gains from Friday, as oil prices decline and bargain hunters step in, although Nvidia falls amid controversy surrounding CEO Jensen Huang.

DAX Rebounds as Investors Look Beyond the AI Selloff
The DAX has started the week on a stronger footing, recovering from last week's technology-driven selloff and pushing back toward the key 26,000 level. Improving sentiment across global markets, easing oil prices and a positive reassessment of technology valuations have helped support the rebound. Attention now shifts to Tuesday's US inflation report and a busy earnings calendar, both of which will determine whether the recovery can extend further.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.