



Dow Jones Forecast: Stocks rise as rate cut optimism persists
US stocks are heading higher again as rate cut optimism persists. The market has shrugged off recent comments by Fed speakers pushing back on rate-cut bets. Vice Chair John Williams and Fed policymaker Mester have suggested that the market is ahead of the Fed with regard to rate cuts. Elsewhere, Google rises despite agreeing to pay $700M to US consumers and the state and pledged to allow for greater competition in the Play store.
Share this:

US futures
Dow futures +0.19% at 37398
S&P futures +0.23% at 4742
Nasdaq futures +0.18% at 16750
In Europe
FTSE +0.01% at 7620
Dax +0.48% at 16725
- Fed speakers push back on rate cut bets
- Gains could be capped owing to Red Sea developments
- Google agrees to pay $700M
- Oil holds yesterday’s gains
Stocks rise as markets shrug off Fed speakers
US stocks are pointing to modest gains as investors remain optimistic that the Federal Reserve will start cutting interest rates in 2024 despite some Fed officials playing down rate-cut bets.
Several Federal Reserve officials in recent days have been pushing back against the market expectations of interest rates early next year. On Friday, Vice Chair John Williams said that the central bank isn't really talking about cutting rates now. His thoughts were mirrored by the Fed policymaker Master, who said that the markets were a bit ahead of the central bank on rate cuts.
Still, those attempts to peddle back don't appear to dampen the positive mood in the market, with all three major indices set to open on the front foot.
Concerns over events in the Red Sea could limit the upside If the situation deteriorates much further. Shipping giants diverging ships around Africa to avoid the Red Sea security threat could mean higher shipping costs, which, as we know from COVID-19 times, can quickly mean higher prices for goods and result in rising inflation.
Corporate news
Apple is unchanged by the news that it will halt sales of its Watch Series 9 and Ultra 2 after the International Trade Commission's ruling upholding a decision that Apple infringed on medical technology patents.
Alphabet will be in focus as Google agrees to pay $700 million to settle a lawsuit brought by U.S. states and consumers over alleged anti-competitive practices at the Play Store.
Tesla will also be in focus as it plans to increase pay for some hourly employees at the Nevada factory. This comes as Tesla faces escalating labor disputes in Sweden, which could spread to Denmark, Norway, and Finland.
Dow Jones forecast – technical analysis
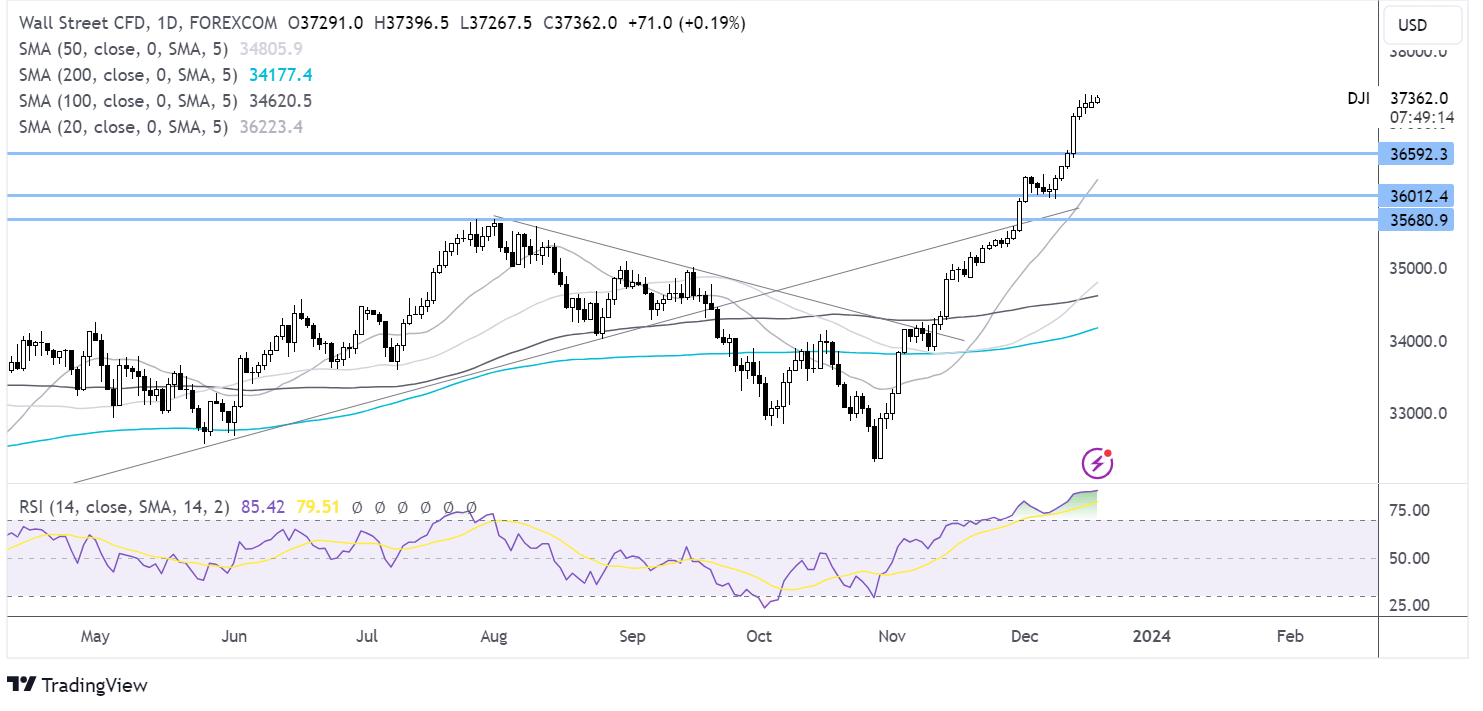
The Dow Jones continues to consolidate below all-time highs. There are few signs of a pullback forming despite seriously overbought conditions. Immediate support can be seen around 36600, the pre-Fed meeting record high, and 36000 round number.
FX markets – USD falls, GBP/USD rises
The USD is edging lower despite Federal Reserve officials pushing back on right-cut bets. The market appears to be ignoring the last commentary. Instead, market players are increasingly bearish about the direction of the USD in 2024.
As expected, BoJ left interest rates in negative territory and said it would continue with its yield curve control measures to support the economy. The central bank gave no clues on its plans for monetary policy tightening next year.
EUR/USD is rising despite eurozone inflation cooling by more than expected in November. CPI fell -0.6% MoM, a steeper decline than the -0.5% seen in the preliminary reading. CPI eased to 2.4% year on year, in line with the initial reading, which is within touching distance of the ECB's 2% target. Falling inflation raises questions over the ECB's hawkish stance last week.
GBP/USD is rising after losses in the previous session and despite a lack of fresh catalysts. Attention will be on UK CPI data tomorrow, which is expected to cool slightly to 4.4%, although core inflation could remain sticky.
USD/JPY +1.1% at 144.35
EUR/USD +0.3% at 1.0962
GBP/USD +0.76% at 1.2743
Oil holds yesterday’s gains.
Oil prices are holding steady on Tuesday after solid gains in the previous session as investors continue to weigh up the possible impact on oil supply after attacks by the Houthi militants on ships in the Red Sea.
While oil major BP has temporarily halted the transition through the Red Sea, oil tanker firms have also said that they will look to avoid the route. However, the disruption is unlikely to greatly affect crude oil supply and is more representative of a rising geopolitical risk premium.
Looking ahead, attention will be on the API US crude inventory data, which is expected to decline by 2.2 million barrels.
WTI crude trades +0.05% at $73.70
Brent trades +0.05% at $78.80
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.

Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

US Dollar Technical Outlook: DXY Bulls Meet Resistance at Yearly Highs 10 1 2026
The U.S. Dollar has held firm despite fading Fed hike bets, but Friday’s payrolls could test the rally’s staying power.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.