




EURCHF Hits a Nearly 3Year Low as SNB Intervention Odds Fall
With today’s headlines allaying fears of imminent intervention, we’ve seen EUR/CHF drop to its lowest level in nearly three years...
Share this:

“Don’t fight in the North or the South. Fight every battle everywhere, always, in your mind. Everyone is your enemy, everyone is your friend.” – Petyr Baelish, Game of Thrones
As many of us recall, the ending of the HBO’s wildly popular Game of Thrones was panned for nonsensical plot points and dialogue, including Littlefinger’s bizarre comment above.
Apparently, a similar “chaos is a ladder / fight every battle everywhere” philosophy pervades the US’s approach to currency manipulators as well. A day after the Trump Administration removed it’s “currency manipulator” label from China, it added Switzerland back onto the its manipulation watchlist. As any student of European history will tell you, it’s difficult to pick a fight with the historically neutral Swiss!
In any event, the Swiss National Bank was quick to respond that it only intervenes into its currency for monetary policy purposes and not for export advantage. In the words of the Swiss International Finance Secretary, “It's to be stressed that Switzerland doesn't manipulate its currency in any way to achieve an adjustment in its balance of payments or an unjustified competitive advantage.”
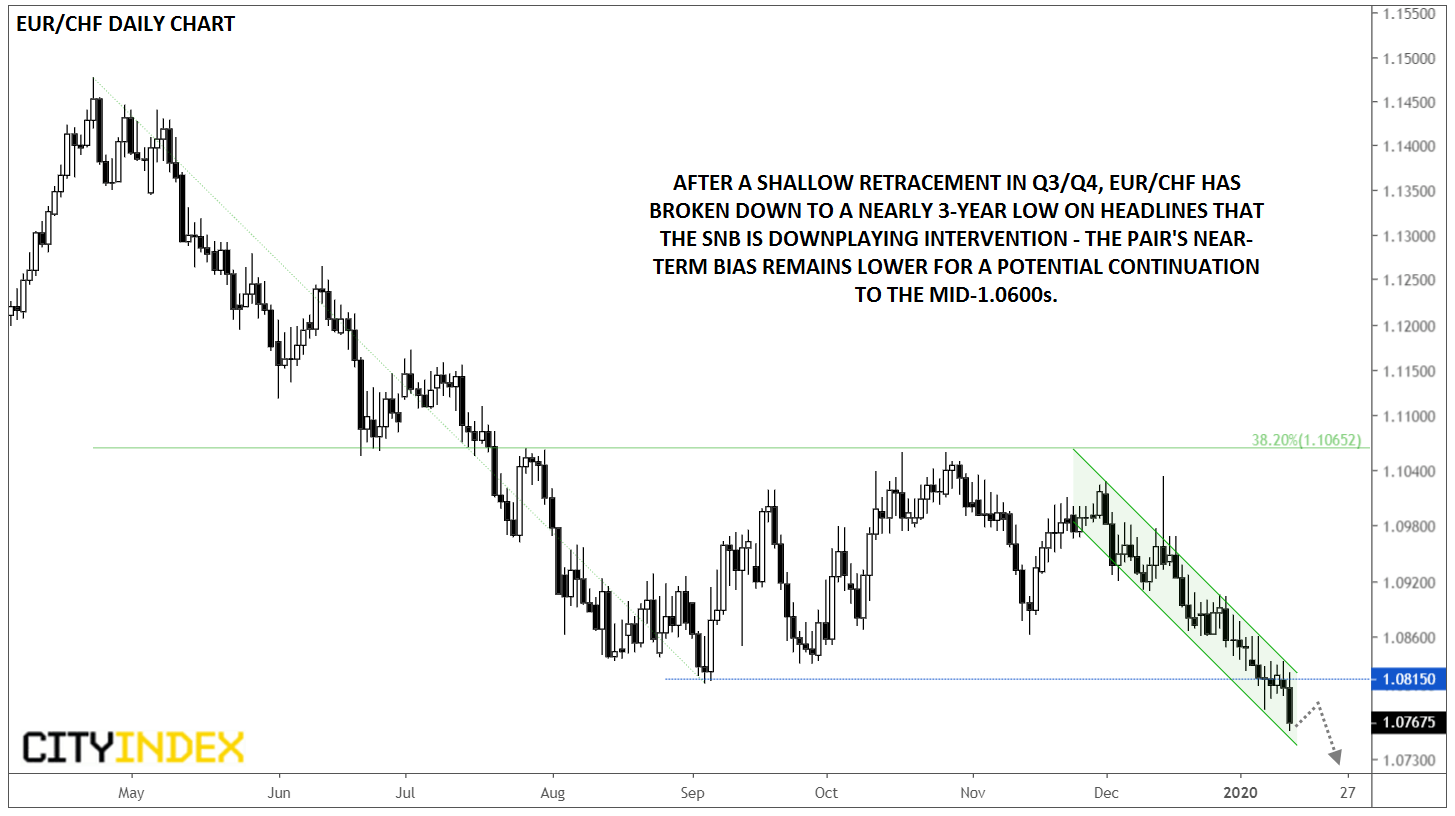
Turning our attention to the EUR/CHF cross, rates fell sharply through the middle of last year before stabilizing in the 1.0815-1.1050 range through Q3 and Q4. In total, the bounce off 1.0815 support didn’t even hit the shallow 38.2% retracement of the summer’s drop, signaling that the momentum remained with the bears. With today’s headlines allaying fears of imminent intervention, we’ve seen EUR/CHF drop to its lowest level in nearly three years:
Source: TradingView, GAIN Capital
Moving forward, the technical bias on EUR/CHF remains bearish, with potential for an extension toward the late 2016 / early 2017 support zone starting in the mid-1.0600s. Only a break out of the near-term bearish channel back above the key 1.0815 would shift the pair’s near-term technical bias back to neutral.
“Don’t fight in the North or the South. Fight every battle everywhere, always, in your mind. Everyone is your enemy, everyone is your friend.” – Petyr Baelish, Game of Thrones
As many of us recall, the ending of the HBO’s wildly popular Game of Thrones was panned for nonsensical plot points and dialogue, including Littlefinger’s bizarre comment above.
Apparently, a similar “chaos is a ladder / fight every battle everywhere” philosophy pervades the US’s approach to currency manipulators as well. A day after the Trump Administration removed it’s “currency manipulator” label from China, it added Switzerland back onto the its manipulation watchlist. As any student of European history will tell you, it’s difficult to pick a fight with the historically neutral Swiss!
In any event, the Swiss National Bank was quick to respond that it only intervenes into its currency for monetary policy purposes and not for export advantage. In the words of the Swiss International Finance Secretary, “It's to be stressed that Switzerland doesn't manipulate its currency in any way to achieve an adjustment in its balance of payments or an unjustified competitive advantage.”
Turning our attention to the EUR/CHF cross, rates fell sharply through the middle of last year before stabilizing in the 1.0815-1.1050 range through Q3 and Q4. In total, the bounce off 1.0815 support didn’t even hit the shallow 38.2% retracement of the summer’s drop, signaling that the momentum remained with the bears. With today’s headlines allaying fears of imminent intervention, we’ve seen EUR/CHF drop to its lowest level in nearly three years:
Source: TradingView, GAIN Capital
Moving forward, the technical bias on EUR/CHF remains bearish, with potential for an extension toward the late 2016 / early 2017 support zone starting in the mid-1.0600s. Only a break out of the near-term bearish channel back above the key 1.0815 would shift the pair’s near-term technical bias back to neutral.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.