




Europe To Start Higher As Trumps Health Improves
European bourses are opening on the front foot as President Trump’s condition improves. Speculation is growing that Trump could be discharged as early as today
Share this:

European bourses opening on the front foot as President Trump’s condition improves. Speculation is growing that Trump could be discharged as early as today. We know that the markers hate uncertainty. The latest headlines are providing more clarity surrounding the health of the President and are easing the political uncertainty which has clouded over the markets since Trump was taken ill. Risk appetite is on the rise meaning that risker assets such as stocks are well supported in early trade on Monday, whilst safe havens such as the US Dollar and Gold are out of favour.
Doctors are saying that they are pleased with Trump’s progress proving some relief to the financial markets. Trump contracted covid with just one month to go until the US Presidential elections adding another layer of uncertainty to elections which saw the two candidates, Jo Biden & Trump, close in the polls. Furthermore, Trump had raised doubts over whether he would accept the result of the elections.
Doctors are saying that they are pleased with Trump’s progress proving some relief to the financial markets. Trump contracted covid with just one month to go until the US Presidential elections adding another layer of uncertainty to elections which saw the two candidates, Jo Biden & Trump, close in the polls. Furthermore, Trump had raised doubts over whether he would accept the result of the elections.
News flow surrounding Trump’s health is expected to drive sentiment today. Signs of deterioration in his health will drag on risk appetite, pulling stocks lower. Whilst news that he has been released from hospital could lift stocks further.
Adding to the upbeat mood in the market, prospects of additional fiscal stimulus in the US have risen, according to House Speaker Nancy Pelosi
Services PMI data in focus
Today sees the release of global services PMIs. Whilst manufacturing has made an impressive recovery from the April’s contraction, service sectors, particularly in tourist destinations such as Spain and Italy are seeing the recovery wobble. Even France and German saw service sector activity back in contraction territory in the flash reading for September.
In the UK the service sector remains resilient for now. The dominant service sector saw activity expand quickly in August hitting 58.1 The more recent flash September reading printed at 55.1, slightly down from August’s peak but still a very strong number. Should Thursday’s print confirm 55.1 then Q3 will have seen an impressive expansion. However, there is a chance that the government’s most recently announced tightening of lockdown restrictions, including a curfew and new social distancing rules could knock confidence, hitting the PMI index.
Brexit talks to continue
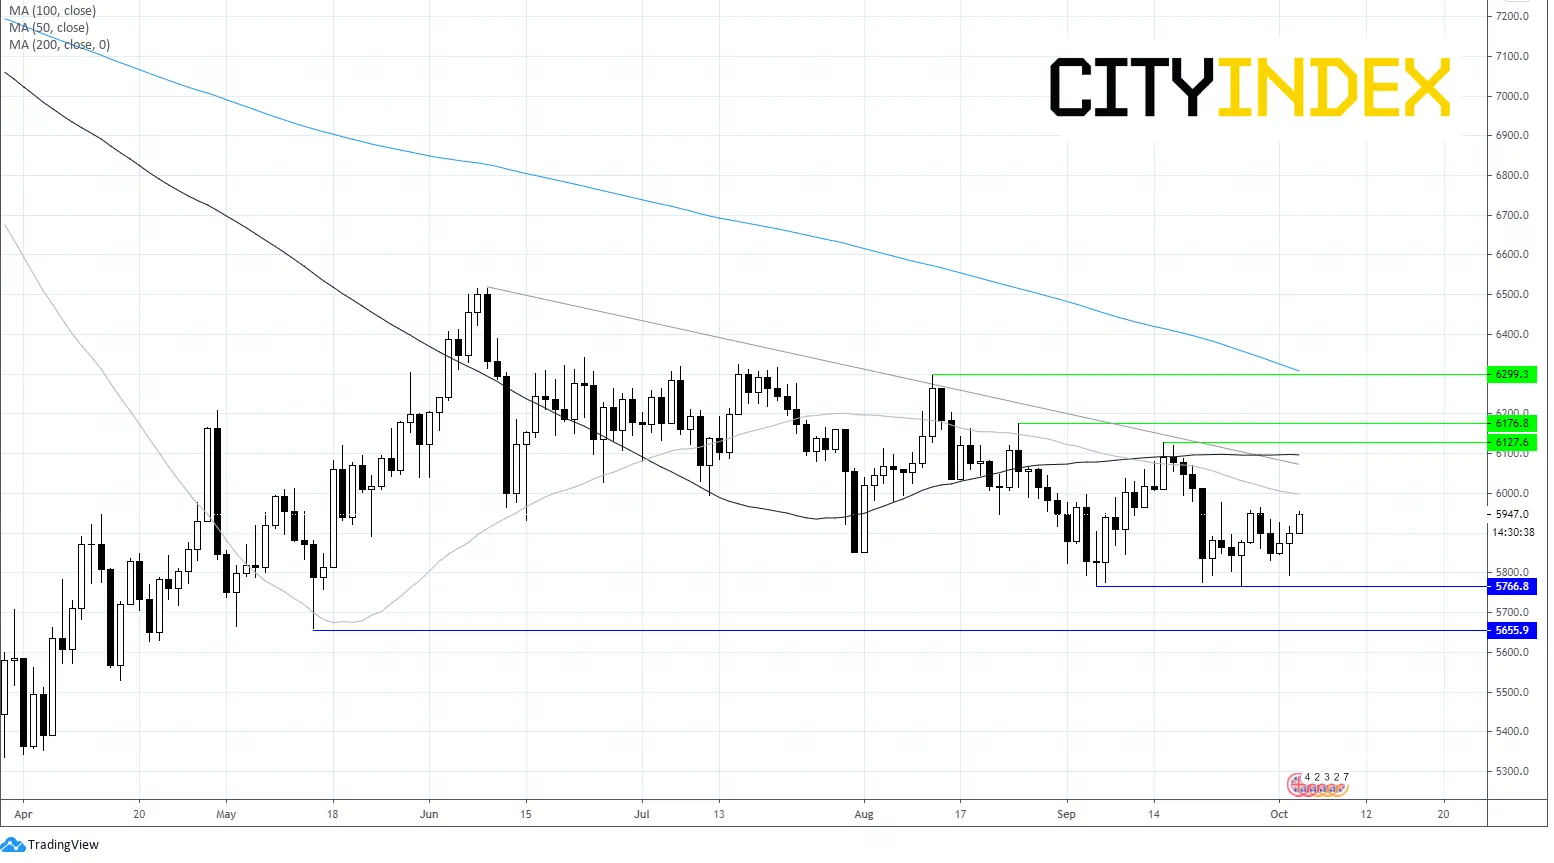
Brexit optimism is underpinning the Pound and could provide support to the more domestically focused FTSE 250. Boris Johnson holding talks with EC President Ursula von der Leyen appears to have injected at least a bit more political momentum into talks, which will now continue this week, after little progress last week. As the clock continues to tick towards the government’s self imposed October 15th deadline there is a growing sense of urgency between the two sides, which could be the key ingredient to a trade deal actually being done.
FTSE Chart
European bourses opening on the front foot as President Trump’s condition improves. Speculation is growing that Trump could be discharged as early as today. We know that the markers hate uncertainty. The latest headlines are providing more clarity surrounding the health of the President and are easing the political uncertainty which has clouded over the markets since Trump was taken ill. Risk appetite is on the rise meaning that risker assets such as stocks are well supported in early trade on Monday, whilst safe havens such as the US Dollar and Gold are out of favour.
Doctors are saying that they are pleased with Trump’s progress proving some relief to the financial markets. Trump contracted covid with just one month to go until the US Presidential elections adding another layer of uncertainty to elections which saw the two candidates, Jo Biden & Trump, close in the polls. Furthermore, Trump had raised doubts over whether he would accept the result of the elections.
Doctors are saying that they are pleased with Trump’s progress proving some relief to the financial markets. Trump contracted covid with just one month to go until the US Presidential elections adding another layer of uncertainty to elections which saw the two candidates, Jo Biden & Trump, close in the polls. Furthermore, Trump had raised doubts over whether he would accept the result of the elections.
News flow surrounding Trump’s health is expected to drive sentiment today. Signs of deterioration in his health will drag on risk appetite, pulling stocks lower. Whilst news that he has been released from hospital could lift stocks further.
Adding to the upbeat mood in the market, prospects of additional fiscal stimulus in the US have risen, according to House Speaker Nancy Pelosi
Services PMI data in focus
Today sees the release of global services PMIs. Whilst manufacturing has made an impressive recovery from the April’s contraction, service sectors, particularly in tourist destinations such as Spain and Italy are seeing the recovery wobble. Even France and German saw service sector activity back in contraction territory in the flash reading for September.
In the UK the service sector remains resilient for now. The dominant service sector saw activity expand quickly in August hitting 58.1 The more recent flash September reading printed at 55.1, slightly down from August’s peak but still a very strong number. Should Thursday’s print confirm 55.1 then Q3 will have seen an impressive expansion. However, there is a chance that the government’s most recently announced tightening of lockdown restrictions, including a curfew and new social distancing rules could knock confidence, hitting the PMI index.
Today sees the release of global services PMIs. Whilst manufacturing has made an impressive recovery from the April’s contraction, service sectors, particularly in tourist destinations such as Spain and Italy are seeing the recovery wobble. Even France and German saw service sector activity back in contraction territory in the flash reading for September.
In the UK the service sector remains resilient for now. The dominant service sector saw activity expand quickly in August hitting 58.1 The more recent flash September reading printed at 55.1, slightly down from August’s peak but still a very strong number. Should Thursday’s print confirm 55.1 then Q3 will have seen an impressive expansion. However, there is a chance that the government’s most recently announced tightening of lockdown restrictions, including a curfew and new social distancing rules could knock confidence, hitting the PMI index.
Brexit talks to continue
Brexit optimism is underpinning the Pound and could provide support to the more domestically focused FTSE 250. Boris Johnson holding talks with EC President Ursula von der Leyen appears to have injected at least a bit more political momentum into talks, which will now continue this week, after little progress last week. As the clock continues to tick towards the government’s self imposed October 15th deadline ther is a growing sense of urgency between the two sides, which could be the key ingredient to a trade deal actually being done.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.