



EUR/USD: Don’t be fooled by slight dollar weakness
Dollar weakness undoubtedly driven by profit-taking ahead of the publication of US CPI report...
Share this:

During the early European session, the US dollar eased off the highs before turning lower ahead of the publication of US inflation report this afternoon. This drove the likes of the EUR/USD, GBP/USD and gold higher. However, don’t be fooled by the apparent dollar weakness here. Its weakness is undoubtedly driven by profit-taking ahead of the publication of US CPI report. I reckon, it will resume higher, possibly as early as later today. The greenback remains head and shoulders above the rest of the major currencies in terms of strength thanks to the Fed’s hawkish stance and a relatively stronger US economy.
Prior to today’s weakness, the greenback had been in renewed demand due in part to firmer data on both the jobs and inflation fronts. On Wednesday, the RPI measure of inflation was a tad stronger than expected, which led to speculation that CPI will also overshoot when it is released later today. On Friday, the latest US non-farm payrolls report continued to point to a healthy jobs market.
With employment at or near maximum, the Fed’s other mandate of keeping inflation close to 2% means it has no choice but to keep on hiking rates until CPI falls sharply and keeps on trending lower from its current 8.3% annual rate. Indeed, the minutes of the September FOMC meeting highlighted that a dovish pivot is still nowhere in sight. Policymakers are in agreement that the risk of doing too little outweighs the risk of hiking too aggressively.
Unless CPI comes in well below expectations of 8.1% today, the dollar rally and stock & bond market weakness is likely to continue, as hopes over the Fed potentially pivoting to a slightly more dovish stance will be dashed… again. Consumer inflation has fallen very slightly in the last couple of months and another print lower would be a welcome sign. However, for the dollar to weaken we will need to see a big drop below expectations.
If PPI is anything to go by, then CPI might actually disappoint those looking for a sharp drop. If that’s the case, the dollar bulls will be happy to keep the currency bid until something changes dramatically.
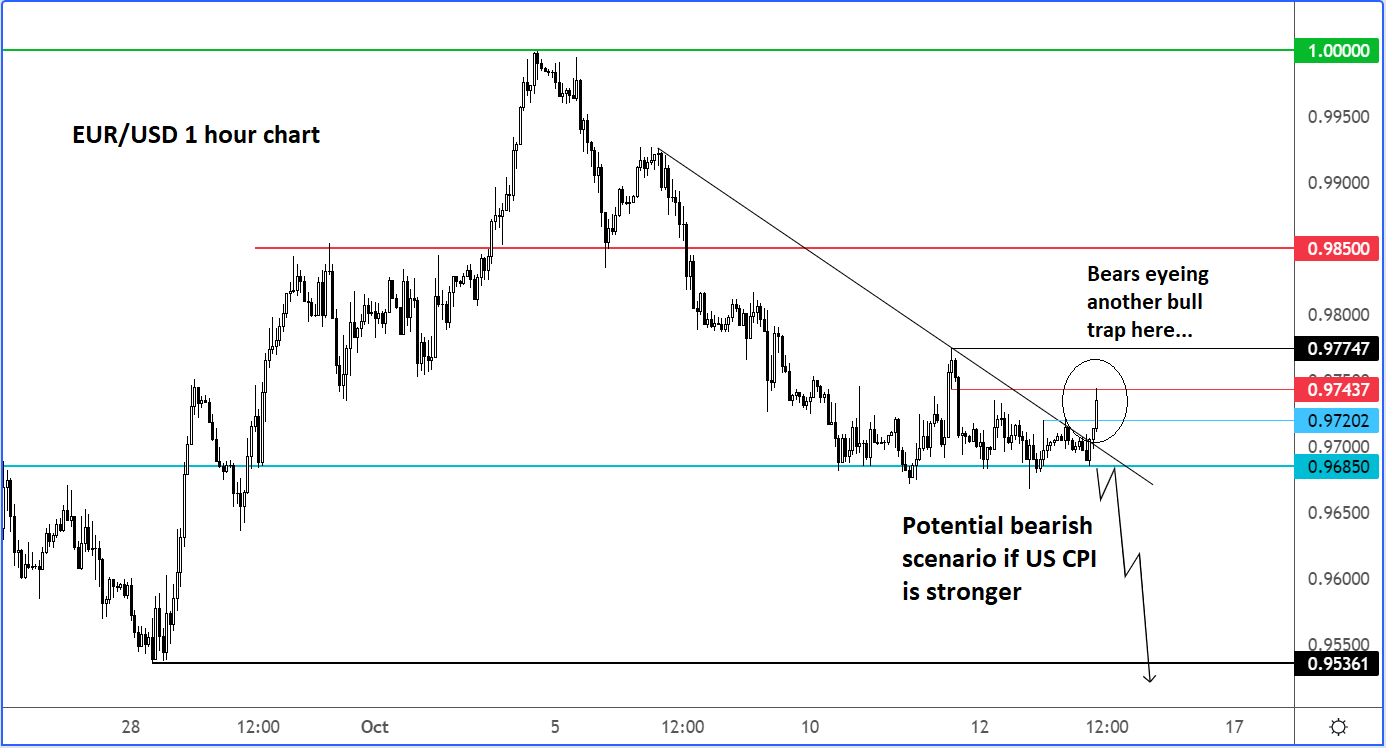
With that in mind, take this breakout on the hourly chart of the EUR/USD with a pinch of salt:
Remember that the long-term trend is bearish and so it is best to look for signs of a failure. If the bearish trend is re-claimed, then that could see the EUR/USD head back down to the recent lows circa 0.9536.
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.