



FTSE rebounds after large losses
The FTSE fell 4.1% last week, tumbling to a three and a half month low. Today risk sentiment has improved and banks do the heavy lifting.
Share this:
FTSE rises after large losses last week
The FTSE is rebounding after steep losses last week. The UK index tumbled 4.1% last week, dropping to a three-and-a-half-month low as recession fears grew.
The FTSE came under pressure after the BoE raised interest rates by 25 basis points and indicated that there were more hikes to come as inflation is set to rise to 11% in the coming month.
In addition to surging inflation, economic growth has stalled, and the outlook is deteriorating further as the coat of living crisis ramps up.
Higher interest rates, supply issues, and falling real wages are reflected in weaker sentiment.
Today data revealed that house prices rose 0.3% to a record high. However, this was a significant slowdown in growth. Rising interest rates are cooling the housing market, bringing house builders lower.
Instead, leading the index higher are the heavyweight Banks after the BoE stops the mortgage market affordability test. Separately banks are also the sector that stands to benefit from rising interest rates lifting ne5t interest income.
Where next for FTSE?
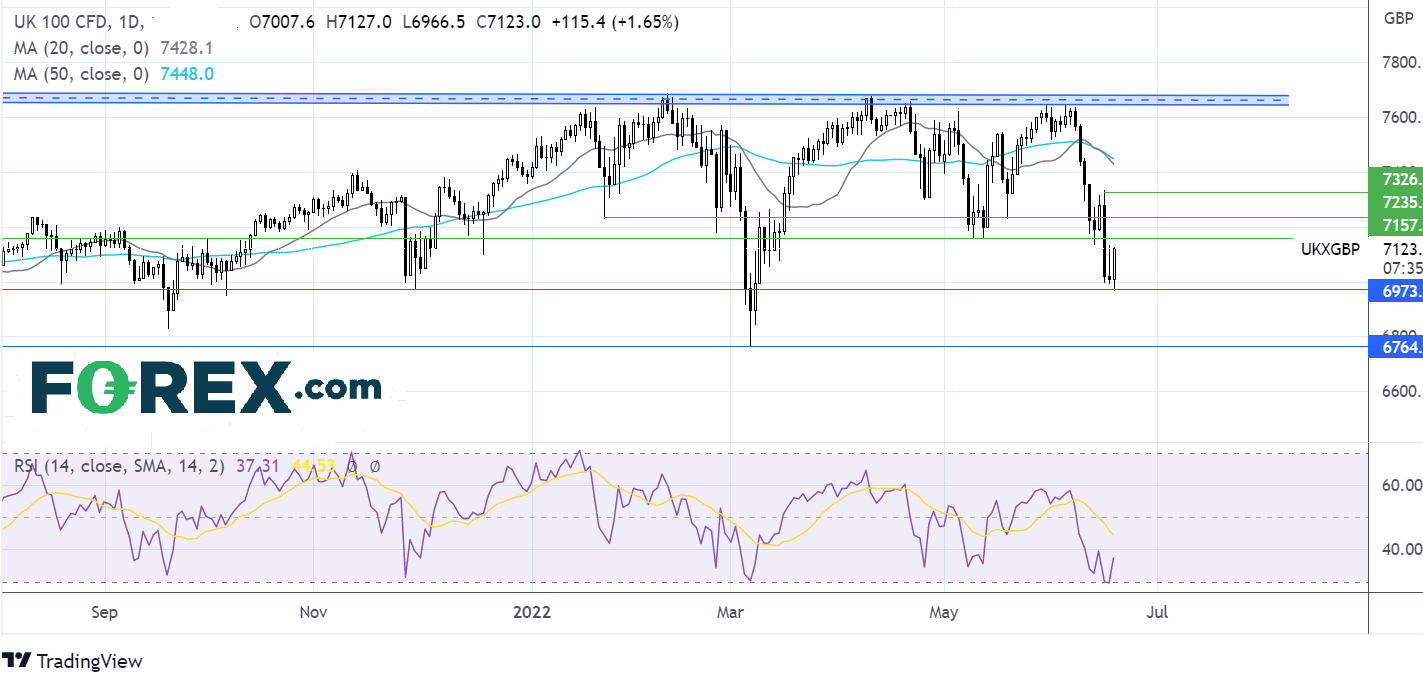
The FTSE ran into resistance at7650 at the start of the month and rebounded lower. The price fell below its 20 & 50 sma, tumbling to support at 6966, the November 30 low.
Today the index is rebounding and heads towards resistance at 7150, the May low. A move over here opens the door to 7225, the May 19 low. However, it would take a move over 7325, the June 16 high, to create a higher high.
However, the trend is still bearish, as highlighted by the RSI remaining in bearish territory and the 20 sma crossing below the 50 sma. Sellers need a move below 6966 in order to extend the bearish trend towards 6830, the September low, and 6762, the 2022 low.
FTSE rises after large losses last week
The FTSE is rebounding after steep losses last week. The UK index tumbled 4.1% last week, dropping to a three-and-a-half-month low as recession fears grew.
The FTSE came under pressure after the BoE raised interest rates by 25 basis points and indicated that there were more hikes to come as inflation is set to rise to 11% in the coming month.
In addition to surging inflation, economic growth has stalled, and the outlook is deteriorating further as the coat of living crisis ramps up.
Higher interest rates, supply issues, and falling real wages are reflected in weaker sentiment.
Today data revealed that house prices rose 0.3% to a record high. However, this was a significant slowdown in growth. Rising interest rates are cooling the housing market, bringing house builders lower.
Instead, leading the index higher are the heavyweight Banks after the BoE stops the mortgage market affordability test. Separately banks are also the sector that stands to benefit from rising interest rates lifting ne5t interest income.
Where next for FTSE?
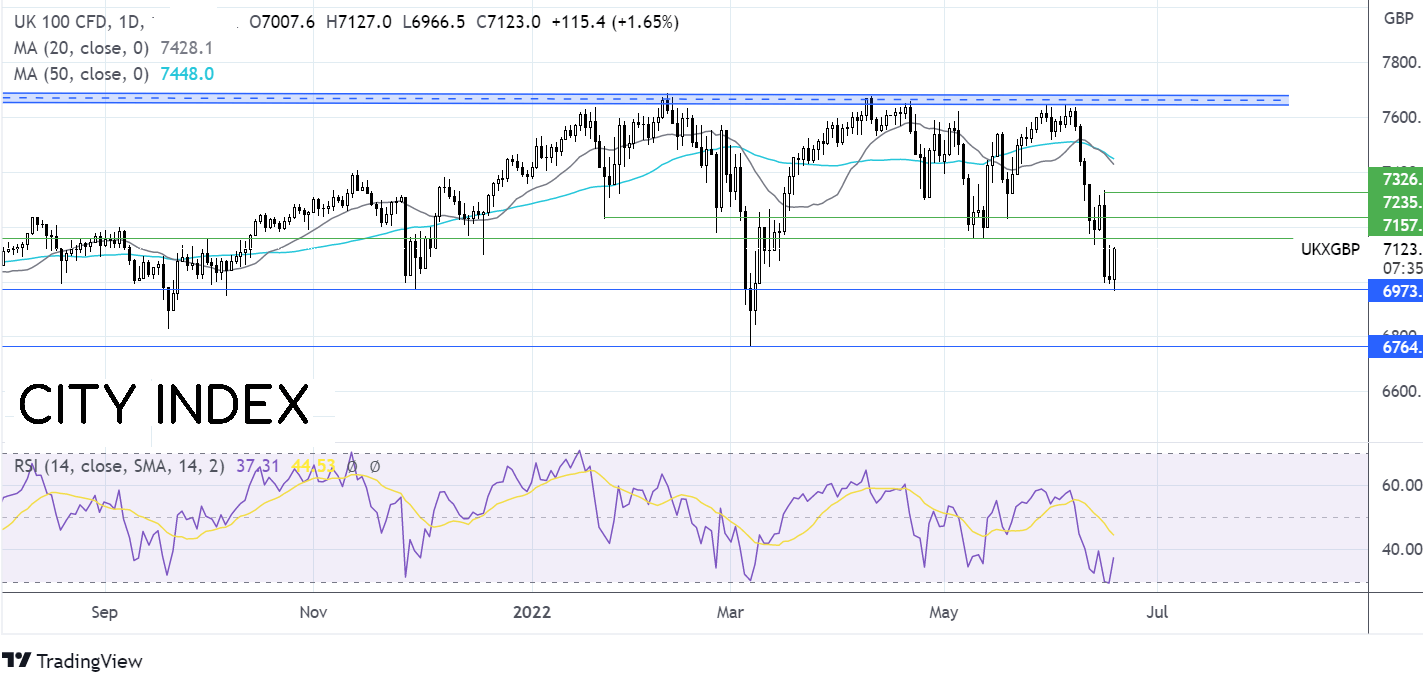
The FTSE ran into resistance at7650 at the start of the month and rebounded lower. The price fell below its 20 & 50 sma, tumbling to support at 6966, the November 30 low.
Today the index is rebounding and heads towards resistance at 7150, the May low. A move over here opens the door to 7225, the May 19 low. However, it would take a move over 7325, the June 16 high, to create a higher high.
However, the trend is still bearish, as highlighted by the RSI remaining in bearish territory and the 20 sma crossing below the 50 sma. Sellers need a move below 6966 in order to extend the bearish trend towards 6830, the September low, and 6762, the 2022 low.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.