




FTSE Rises After Better Than Forecast Employment Figures Chinese Data
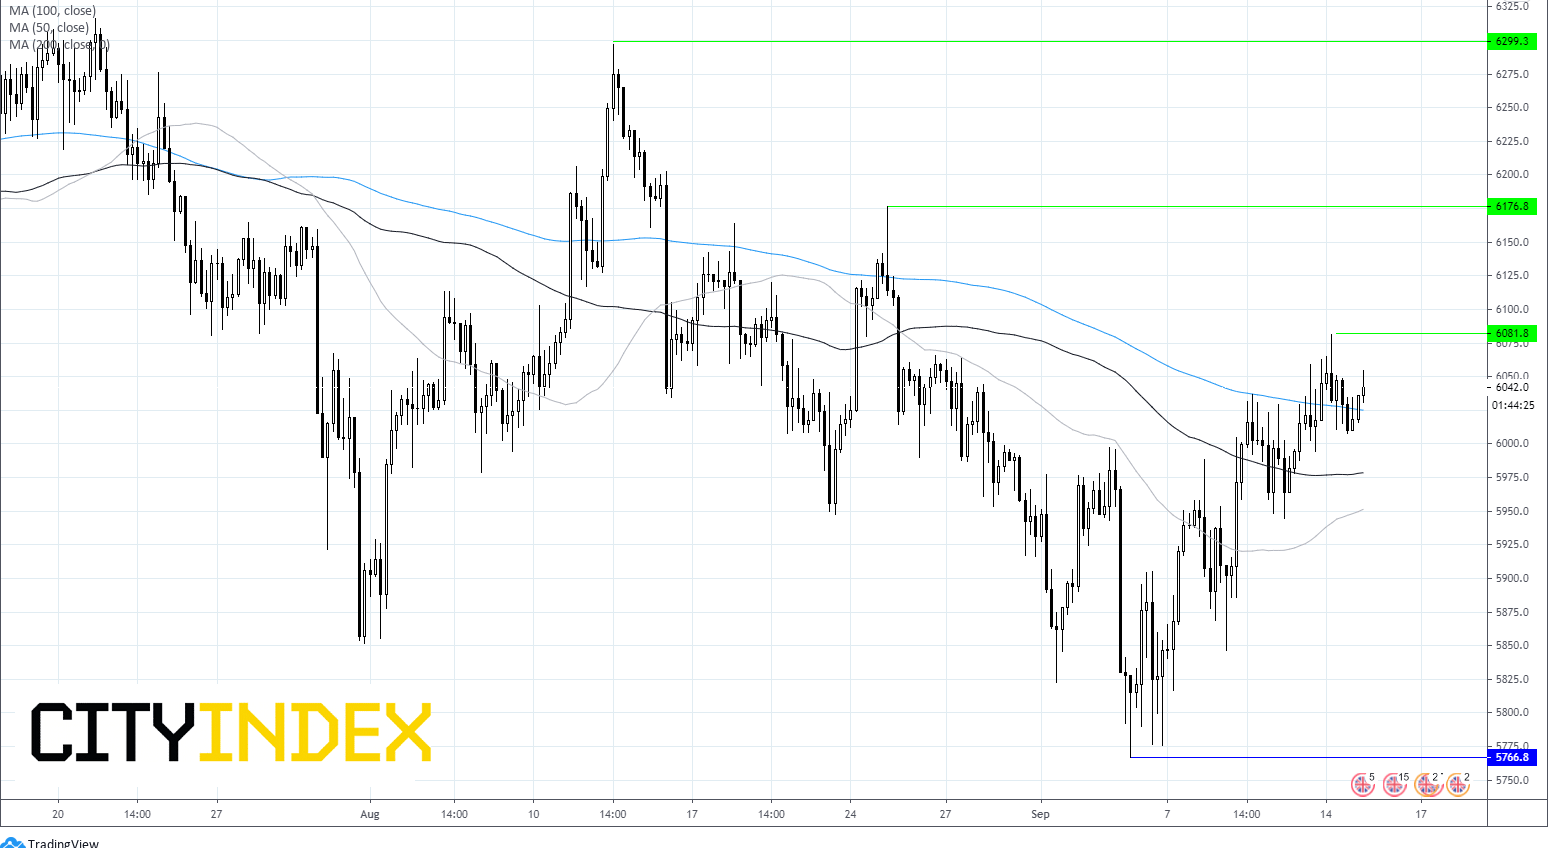
FTSE attempts to push higher following slightly brighter than expected UK employment figures and encouraging Chinese data.
Share this:

After a strong finish on Wall Street overnight, European indices are looking less certain with a mildly positive open.
Deal making on Wall Street and vaccine optimism boosted risk sentiment overnight and drove share prices higher in the previous session. Today trades in Europe are looking less certain attempting to push mildly higher, following slightly brighter than expected UK employment figures and encouraging Chinese data.
UK employment data was mixed, but on the brighter side of mixed. The unemployment rate ticked higher to 4.1% in the three months to July, up from 3.9%. Whilst this is a tick closer to reality the figures show that the report isn’t fit for purpose as those 2 million still furloughed still aren’t showing up. The fact that the claimant count (73.7k vs 100k) and the change in employment (-12k vs -125k exp) were better than forecast offers some hope that the labour market could be in a slightly better place than initially feared. The Pound holds gains versus
US Dollar and has reversed earlier losses versus the Euro.
Boris Johnson’s Internal markets bill has cleared its firth hurdle in Parliament. There was a sense of Brexit déjà vu, but the controversial bill was pushed through to a second reading on a majority of 77. So far the Pound has not been that deterred by the bill advancing indicating that optimism remains that a trade deal could still be salvaged in the coming weeks.
Boris Johnson’s Internal markets bill has cleared its firth hurdle in Parliament. There was a sense of Brexit déjà vu, but the controversial bill was pushed through to a second reading on a majority of 77. So far the Pound has not been that deterred by the bill advancing indicating that optimism remains that a trade deal could still be salvaged in the coming weeks.
China retail sales turn positive
Figures from China revealed that the economic recovery in the world’s second largest economy continued in August. Industrial output rose 5.6% yoy, its fifth straight month of growth. Perhaps more importantly retail sales grew for the first time in 2020 as Chinese consumers stepped up the spending following the coronavirus crisis. The consumer recovery in China has taken significantly longer to pull through than the industrial recovery, given the way that coronavirus lockdown impacts the economy. However, the data offers optimism that a recovery is possible. The risk on trade is being reflected more in the softer dollar rather than sharply rising stock indices.
Figures from China revealed that the economic recovery in the world’s second largest economy continued in August. Industrial output rose 5.6% yoy, its fifth straight month of growth. Perhaps more importantly retail sales grew for the first time in 2020 as Chinese consumers stepped up the spending following the coronavirus crisis. The consumer recovery in China has taken significantly longer to pull through than the industrial recovery, given the way that coronavirus lockdown impacts the economy. However, the data offers optimism that a recovery is possible. The risk on trade is being reflected more in the softer dollar rather than sharply rising stock indices.
Ocado sees sales jump 52%
Ocado reported a 52% jump in revenue for the 13 weeks to August as the coronavirus crisis sparked a huge demand for deliveries. The Q3 growth follows a 27.2% jump in sales in the first half. Whilst a strong lift in demand was on the cards, these levels are impressive. But perhaps what will be of more interest is how the joint venture with M&S is going. It is still very early days with switch on 1st September , however the fact that clients are reportedly responding well to the switch bodes well.
FTSE Chart
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.