




FX Brief Kiwi Spikes Aside Its Calm Before The Powell Storm
A summary of news and snapshot of moves from today’s Asia session.
Share this:

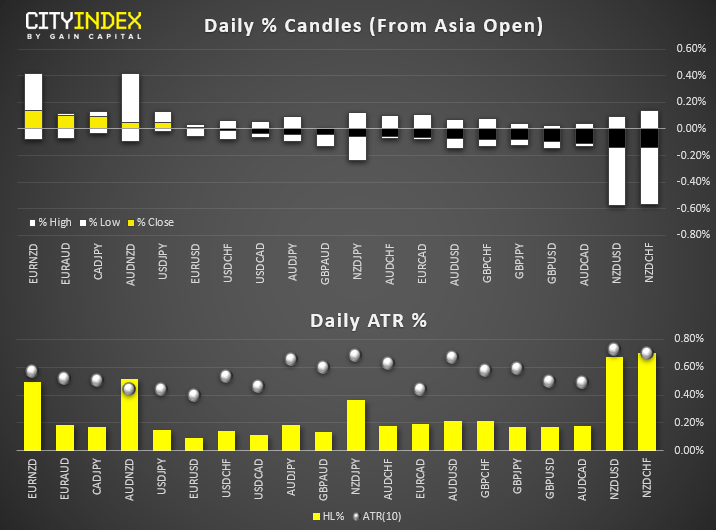
- Were it not for the sudden spike on NZD crosses then ranges would have been typically small, given market are keenly awaiting comments from Powell later. The lack of news and immediate price reversal suggests its liquidity driven.
- USD and NZD are currently the strongest majors, CHF and AUD are the weakest.
- Bitcoin is above $13k against after breaking out of compression this week.
- Despite 2 cuts from the RBA, Australian consumer sentiment fell -4.1% in June, it’s most pessimistic level in Q2. The index has fallen to a 2-year low and fell -9.3% YoY, its weakest annual rate of change since January 2015.
- Chinese producer prices were flat at 0%, their lowest level since August 2018 when prices were last deflating. Inflation rose 2.7% expected, driven by food at +8.3% YoY, 21.1% of which was pork prices. Presumably driven by the trade war, they could prove to be quite an inflationary input.
- Equities and Index futures are trading mostly higher after a couple of subdued sessions ahead of Powell’s testimony and Fed minutes.
Up Next
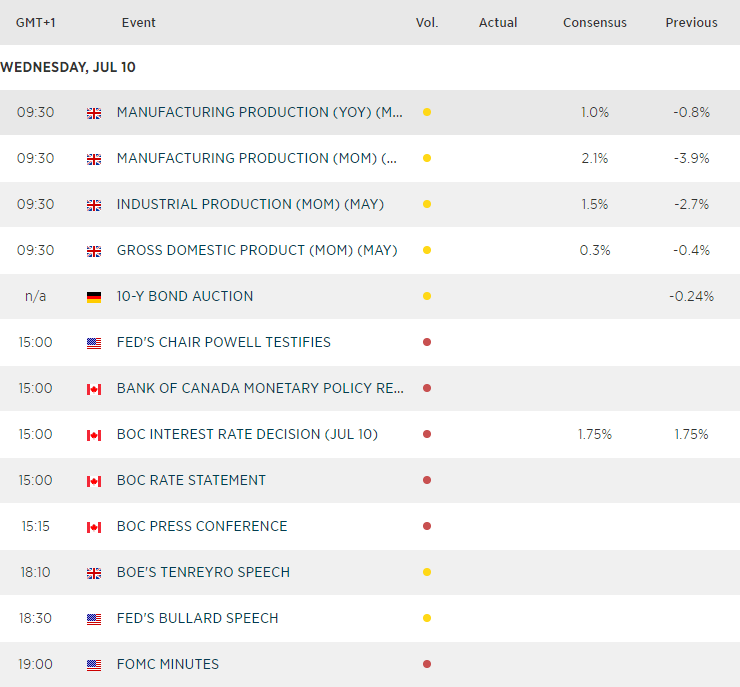
- A host of economic data puts Sterling firmly on the radar early session. Car plant shutdown saw manufacturing and industrial output plummet in April, so we’re not expecting a merry turnaround here. GDP is a final estimate so not likely to deviate too far from its prior read of 1.3%.
- From the US, Powell’s testimony is likely to be the highlight of the session as markets want more clarity over how far Fed are likely to cut and when. Fed minutes are also later in the session, but not expected to be as lively as Powell’s testimony.
- BOC are expected to hold rates but, given their strong economic data in recent weeks then be on guard for a slightly hawkish undertone. CAD crosses are clearly the ones to watch around this.
- Were it not for the sudden spike on NZD crosses then ranges would have been typically small, given market are keenly awaiting comments from Powell later. The lack of news and immediate price reversal suggests its liquidity driven.
- USD and NZD are currently the strongest majors, CHF and AUD are the weakest.
- Despite 2 cuts from the RBA, Australian consumer sentiment fell -4.1% in June, it’s most pessimistic level in Q2. The index has fallen to a 2-year low and fell -9.3% YoY, its weakest annual rate of change since January 2015.
- Chinese producer prices were flat at 0%, their lowest level since August 2018 when prices were last deflating. Inflation rose 2.7% expected, driven by food at +8.3% YoY, 21.1% of which was pork prices. Presumably driven by the trade war, they could prove to be quite an inflationary input.
- Equities and Index futures are trading mostly higher after a couple of subdued sessions ahead of Powell’s testimony and Fed minutes.
Up Next
- A host of economic data puts Sterling firmly on the radar early session. Car plant shutdown saw manufacturing and industrial output plummet in April, so we’re not expecting a merry turnaround here. GDP is a final estimate so not likely to deviate too far from its prior read of 1.3%.
- From the US, Powell’s testimony is likely to be the highlight of the session as markets want more clarity over how far Fed are likely to cut and when. Fed minutes are also later in the session, but not expected to be as lively as Powell’s testimony.
- BOC are expected to hold rates but, given their strong economic data in recent weeks then be on guard for a slightly hawkish undertone. CAD crosses are clearly the ones to watch around this.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.
Canadian Dollar Forecast: USD/CAD Four-Week Rally Eyes Yearly Highs 9 30 2026
USD/CAD has advanced in 14 of the past 15 sessions, but stretched momentum raises the stakes as major resistance and NFP come into focus.


British Pound Technical Outlook: GBP/USD Rebound Challenges September Downtrend 9 30 2026
Sterling has rallied sharply from key support, with GBP/USD at an inflection point that could determine whether a larger recovery is underway.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.