



GBPUSD stronger and USDCHF weaker
Here is a look at some of the largest movers of the week: Chart
Share this:

The US Dollar was bullish against all of its major pairs on Friday. On the US economic data front, the Leading Index rose 0.6% on month in November (+0.5% expected), compared to a revised +0.8% in October.
On Monday, no major economic data is expected.
The Euro was bearish against most of its major pairs with the exception of the CAD and GBP. In Europe, on the statistical front, in Germany, the IFO business climate index came out better than expected at 92.1 in December, compared with 90.9 in November (revised from 90.7) and 90.0 expected. The Current Conditions sub-index stood at 91.3, compared with 90.0 in the previous month and 89.0 expected. The outlook sub-index stood at 92.8, compared with 91.8 a month earlier (revised from 91.5) and 92.5 expected. On the other hand, the producer price index was up 0.2% in November, compared with +0.1% expected, after increasing by 0.1% the previous month. Also, in the UK, retail sales fell by 2.6% in November, whereas the consensus forecast was for a decline of 4.0%, after a 1.4% increase in October (revised from +1.3%). In addition, the GfK household confidence indicator showed a slight increase to -26 in December, as expected, compared to -33 the previous month.
The Australian dollar was bullish against most of its major pairs with the exception of the CHF and USD.
Looking at the large movers of the week, the GBP/USD jumped just over 2% (274 pips) over the last 5 trading days making it the top performer of the week. The pair broke above 1.3535 resistance briefly however could not close above it. The anticipation of a breakout remains.
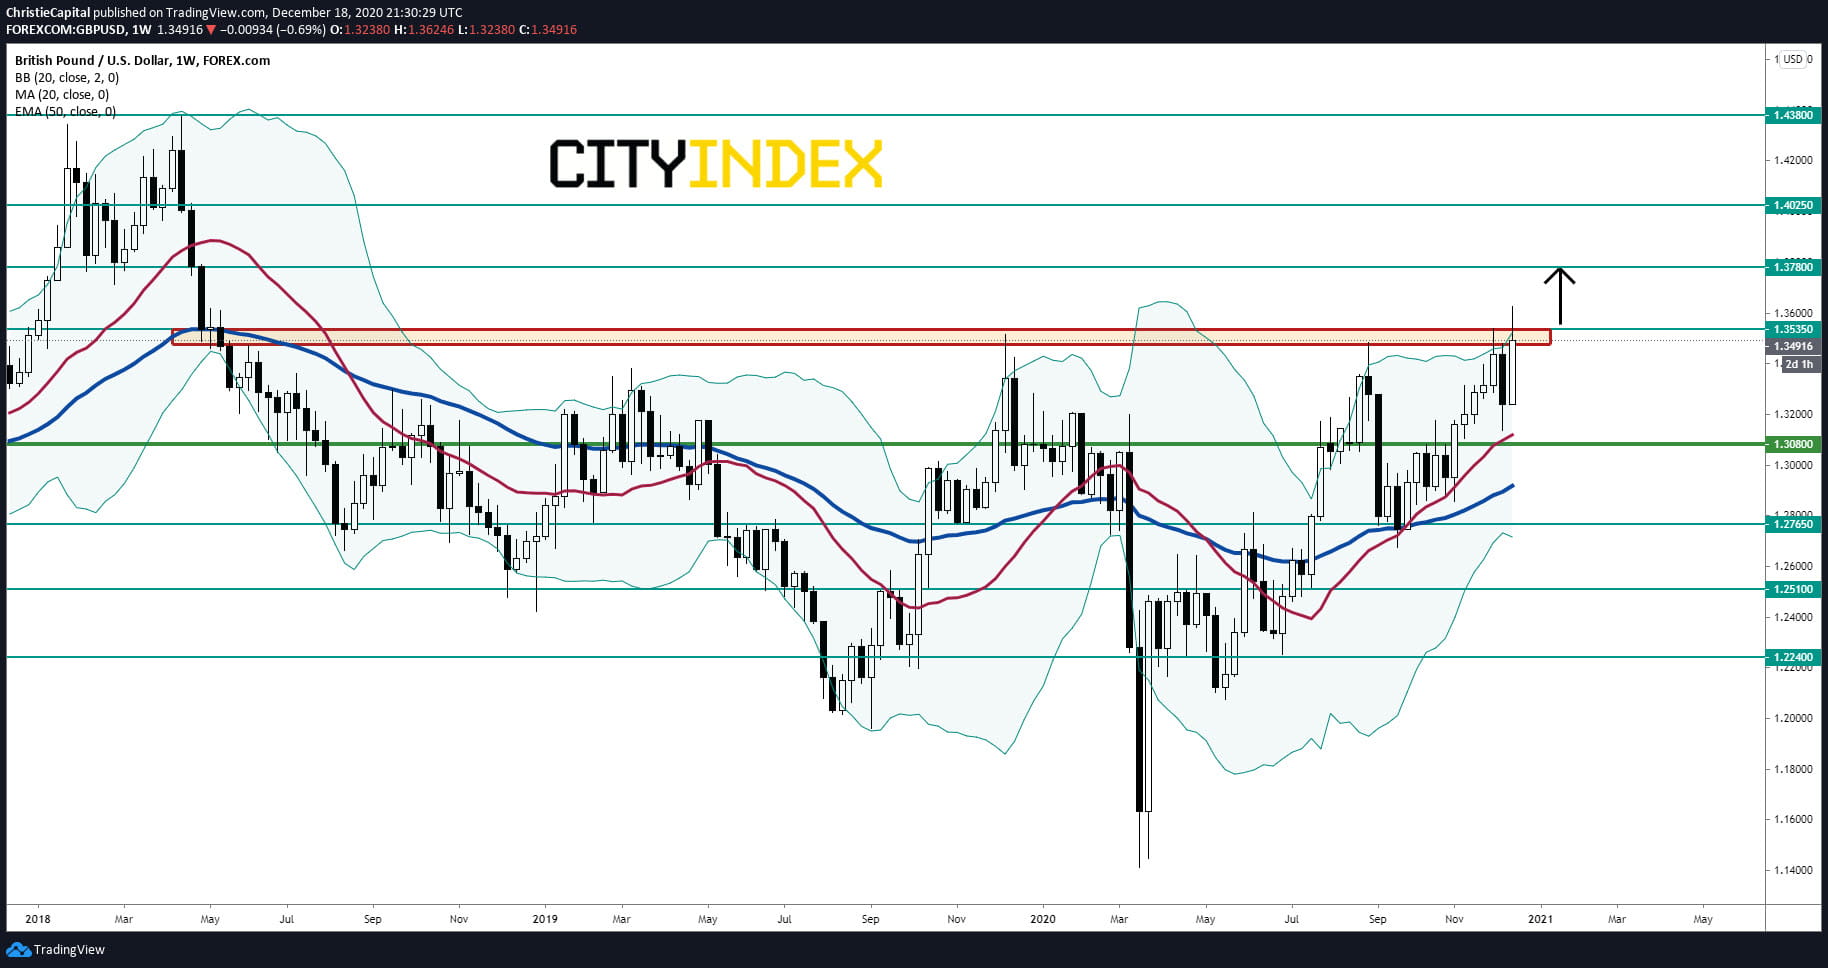
Source: GAIN Capital, TradingView
The largest decliner on the week was the USD/CHF pair with a decline of 0.76% (63 pips). The downside prevails after the pair broke below a consolidation zone. Prior support in the consolidation at 0.898 has now become key resistance on the decline. Look for the bearish trend to continue towards support targets of 0.898 and 0.87 in extension.

Source: GAIN Capital, TradingView
On Monday, no major economic data is expected.
The Euro was bearish against most of its major pairs with the exception of the CAD and GBP. In Europe, on the statistical front, in Germany, the IFO business climate index came out better than expected at 92.1 in December, compared with 90.9 in November (revised from 90.7) and 90.0 expected. The Current Conditions sub-index stood at 91.3, compared with 90.0 in the previous month and 89.0 expected. The outlook sub-index stood at 92.8, compared with 91.8 a month earlier (revised from 91.5) and 92.5 expected. On the other hand, the producer price index was up 0.2% in November, compared with +0.1% expected, after increasing by 0.1% the previous month. Also, in the UK, retail sales fell by 2.6% in November, whereas the consensus forecast was for a decline of 4.0%, after a 1.4% increase in October (revised from +1.3%). In addition, the GfK household confidence indicator showed a slight increase to -26 in December, as expected, compared to -33 the previous month.
The Australian dollar was bullish against most of its major pairs with the exception of the CHF and USD.
Looking at the large movers of the week, the GBP/USD jumped just over 2% (274 pips) over the last 5 trading days making it the top performer of the week. The pair broke above 1.3535 resistance briefly however could not close above it. The anticipation of a breakout remains.
Source: GAIN Capital, TradingView
The largest decliner on the week was the USD/CHF pair with a decline of 0.76% (63 pips). The downside prevails after the pair broke below a consolidation zone. Prior support in the consolidation at 0.898 has now become key resistance on the decline. Look for the bearish trend to continue towards support targets of 0.898 and 0.87 in extension.
Source: GAIN Capital, TradingView
The US Dollar was bullish against all of its major pairs on Friday. On the US economic data front, the Leading Index rose 0.6% on month in November (+0.5% expected), compared to a revised +0.8% in October.
On Monday, no major economic data is expected.
The Euro was bearish against most of its major pairs with the exception of the CAD and GBP. In Europe, on the statistical front, in Germany, the IFO business climate index came out better than expected at 92.1 in December, compared with 90.9 in November (revised from 90.7) and 90.0 expected. The Current Conditions sub-index stood at 91.3, compared with 90.0 in the previous month and 89.0 expected. The outlook sub-index stood at 92.8, compared with 91.8 a month earlier (revised from 91.5) and 92.5 expected. On the other hand, the producer price index was up 0.2% in November, compared with +0.1% expected, after increasing by 0.1% the previous month. Also, in the UK, retail sales fell by 2.6% in November, whereas the consensus forecast was for a decline of 4.0%, after a 1.4% increase in October (revised from +1.3%). In addition, the GfK household confidence indicator showed a slight increase to -26 in December, as expected, compared to -33 the previous month.
The Australian dollar was bullish against most of its major pairs with the exception of the CHF and USD.
Looking at the large movers of the week, the GBP/USD jumped just over 2% (274 pips) over the last 5 trading days making it the top performer of the week. The pair broke above 1.3535 resistance briefly however could not close above it. The anticipation of a breakout remains.
Source: GAIN Capital, TradingView
The largest decliner on the week was the USD/CHF pair with a decline of 0.76% (63 pips). The downside prevails after the pair broke below a consolidation zone. Prior support in the consolidation at 0.898 has now become key resistance on the decline. Look for the bearish trend to continue towards support targets of 0.898 and 0.87 in extension.
Source: GAIN Capital, TradingView
On Monday, no major economic data is expected.
The Euro was bearish against most of its major pairs with the exception of the CAD and GBP. In Europe, on the statistical front, in Germany, the IFO business climate index came out better than expected at 92.1 in December, compared with 90.9 in November (revised from 90.7) and 90.0 expected. The Current Conditions sub-index stood at 91.3, compared with 90.0 in the previous month and 89.0 expected. The outlook sub-index stood at 92.8, compared with 91.8 a month earlier (revised from 91.5) and 92.5 expected. On the other hand, the producer price index was up 0.2% in November, compared with +0.1% expected, after increasing by 0.1% the previous month. Also, in the UK, retail sales fell by 2.6% in November, whereas the consensus forecast was for a decline of 4.0%, after a 1.4% increase in October (revised from +1.3%). In addition, the GfK household confidence indicator showed a slight increase to -26 in December, as expected, compared to -33 the previous month.
The Australian dollar was bullish against most of its major pairs with the exception of the CHF and USD.
Looking at the large movers of the week, the GBP/USD jumped just over 2% (274 pips) over the last 5 trading days making it the top performer of the week. The pair broke above 1.3535 resistance briefly however could not close above it. The anticipation of a breakout remains.
Source: GAIN Capital, TradingView
The largest decliner on the week was the USD/CHF pair with a decline of 0.76% (63 pips). The downside prevails after the pair broke below a consolidation zone. Prior support in the consolidation at 0.898 has now become key resistance on the decline. Look for the bearish trend to continue towards support targets of 0.898 and 0.87 in extension.
Source: GAIN Capital, TradingView
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.