





Market Brief Double Whammy for Pound
A summary of news and snapshot of moves ahead of the US session.
Share this:

- Market update at 12:20 GMT: In FX GBP was by far the weakest, with EUR and USD the strongest among the majors; stocks were off their best levels, and key commodities were lower.
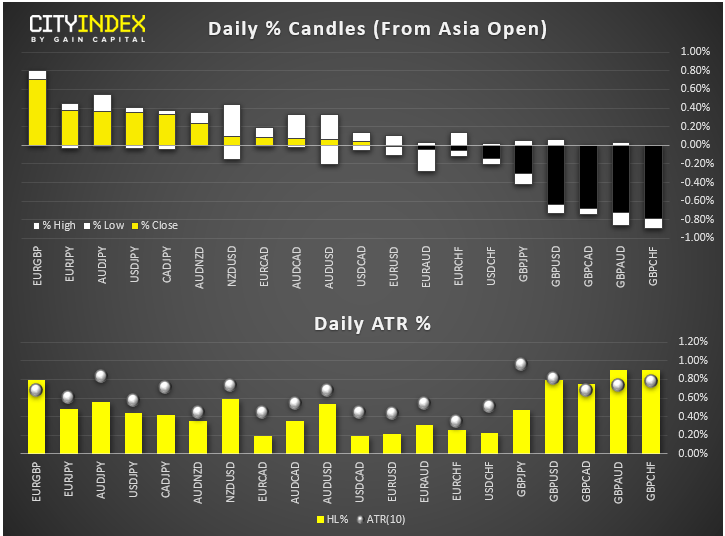
View our guide on how to interpret the FX Dashboard
- GBP, already downbeat by news BoE’s Vlieghe will consider voting for a rate cut, was hit further when UK GDP came in below expectations earlier with a print of -0.3% m/m vs 0.0% expected. Manufacturing production (-1.7%) also disappointed but construction output (+1.9%) beat.
- Stocks: Risk sentiment was given a gentle boost first thing, with traders anticipating that US and China will sign the much-touted phase one trade deal on Wednesday. However, European indices turned lower by mid-morning, awaiting direction from wall Street. That said, the FTSE remained in the black thanks to those disappointing UK macro numbers weighing on the pound.
- Earnings kick off: The other significant focus will be the start of U.S. Q4 2019 earnings session. Major banks will kickstart the reporting session with Wells Fargo, Citigroup and JP Morgan all scheduled to report their results on Tuesday.
- No major data scheduled from North America, except the BOC Business Outlook Survey at 15:30 GMT.
- Market update at 12:20 GMT: In FX GBP was by far the weakest, with EUR and USD the strongest among the majors; stocks were off their best levels, and key commodities were lower.

View our guide on how to interpret the FX Dashboard
- GBP, already downbeat by news BoE’s Vlieghe will consider voting for a rate cut, was hit further when UK GDP came in below expectations earlier with a print of -0.3% m/m vs 0.0% expected. Manufacturing production (-1.7%) also disappointed but construction output (+1.9%) beat.
- Stocks: Risk sentiment was given a gentle boost first thing, with traders anticipating that US and China will sign the much-touted phase one trade deal on Wednesday. However, European indices turned lower by mid-morning, awaiting direction from wall Street. That said, the FTSE remained in the black thanks to those disappointing UK macro numbers weighing on the pound.
- Earnings kick off: The other significant focus will be the start of U.S. Q4 2019 earnings session. Major banks will kickstart the reporting session with Wells Fargo, Citigroup and JP Morgan all scheduled to report their results on Tuesday.
- No major data scheduled from North America, except the BOC Business Outlook Survey at 15:30 GMT.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.