




Market Brief FTSE roars higher for second straight session
A summary of news and snapshot of moves ahead of the US session.
Share this:

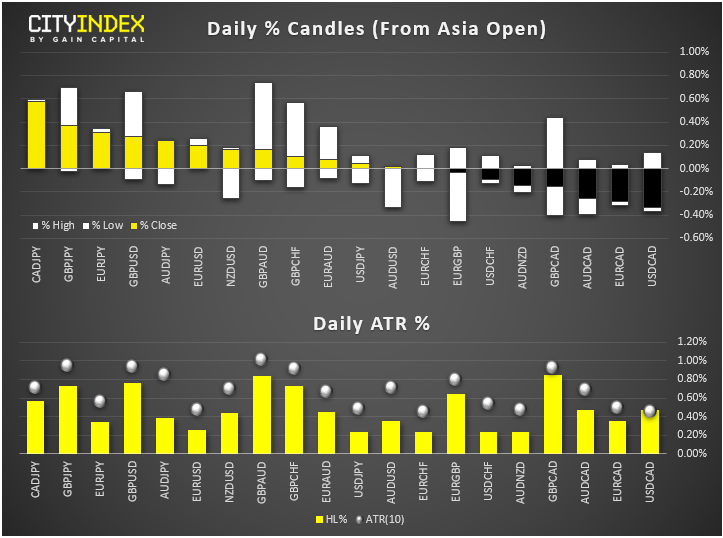
- Market update at just after midday in London: In FX, CAD lead commodity dollars higher while JPY and USD were the weakest. Stocks were higher in Europe, led by the FTSE, after a lacklustre session in Asia overnight and a flat close on Wall Street on Friday. Oil was higher, so too were copper and silver prices. Gold was flat as a weaker dollar and ongoing “risk-on” trade provided conflicting forces.
View our guide on how to interpret the FX Dashboard
- Sentiment towards risk assets remained positive after the US and China managed to strike a phase one trade deal and as voters in the UK delivered a surprisingly large support for PM Boris Johnson’s Conservatives - this has likely paved the way for the Brexit Withdrawal Agreement to be finally passed through parliament, ending months of uncertainty.
- Data recap: Today’s economic data releases show a mixed real economy. China’ retail sales (+8% y/y) and industrial production (+6.2% y/y) both topped expectations, while surveyed purchasing managers among manufacturers in UK (47.4), France (50.3), Germany (43.4), and Eurozone (45.9) reported deteriorating economic activity in the sector. However, these were offset by better than expected services PMIs from France (52.4), Germany (52.0) and Eurozone (52.4), although the UK PMI (49.0) was weaker.
- GBP: Despite the soft UK PMI data, the pound refused to give back any meaningful chunk of its election-linked gains. Investors realise the PMI data reflects sentiment before the outcome of the election was announced. UK data may well improve in the months ahead given the clearing of the dark Brexit clouds that had brought a gloomy feeling among businesses and households.
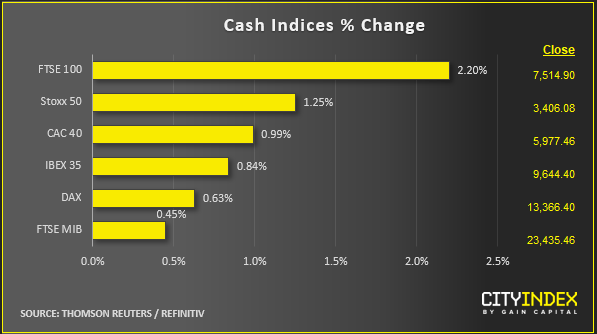
- Stocks: UK markets have jumped higher for the second session. This comes after Boris Johnson’s big election victory alleviating some Brexit-related uncertainty. It looks like we are not the only ones bullish on the FTSE as outlined in the Week Ahead report on Friday. Goldman Sachs said it was particularly bullish on UK homebuilders and banks that have struggled recently. “Clarity on the UK’s terms of exit from the EU should unlock pent-up business investment; the reversal of a decade of fiscal consolidation should provide a fillip to domestic demand; and a pick-up in global growth should underpin a recovery in net exports,” the bank said in a note.
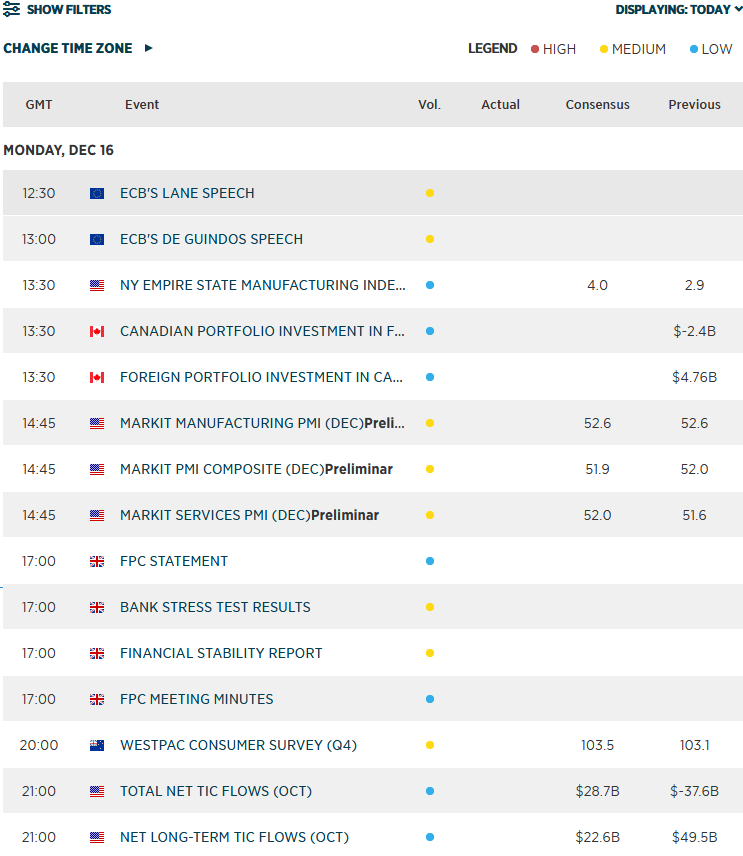
- Coming up:
- Market update at just after midday in London: In FX, CAD lead commodity dollars higher while JPY and USD were the weakest. Stocks were higher in Europe, led by the FTSE, after a lacklustre session in Asia overnight and a flat close on Wall Street on Friday. Oil was higher, so too were copper and silver prices. Gold was flat as a weaker dollar and ongoing “risk-on” trade provided conflicting forces.
View our guide on how to interpret the FX Dashboard
- Sentiment towards risk assets remained positive after the US and China managed to strike a phase one trade deal and as voters in the UK delivered a surprisingly large support for PM Boris Johnson’s Conservatives - this has likely paved the way for the Brexit Withdrawal Agreement to be finally passed through parliament, ending months of uncertainty.
- Data recap: Today’s economic data releases show a mixed real economy. China’ retail sales (+8% y/y) and industrial production (+6.2% y/y) both topped expectations, while surveyed purchasing managers among manufacturers in UK (47.4), France (50.3), Germany (43.4), and Eurozone (45.9) reported deteriorating economic activity in the sector. However, these were offset by better than expected services PMIs from France (52.4), Germany (52.0) and Eurozone (52.4), although the UK PMI (49.0) was weaker.
- GBP: Despite the soft UK PMI data, the pound refused to give back any meaningful chunk of its election-linked gains. Investors realise the PMI data reflects sentiment before the outcome of the election was announced. UK data may well improve in the months ahead given the clearing of the dark Brexit clouds that had brought a gloomy feeling among businesses and households.
- Stocks: UK markets have jumped higher for the second session. This comes after Boris Johnson’s big election victory alleviating some Brexit-related uncertainty. It looks like we are not the only ones bullish on the FTSE as outlined in the Week Ahead report on Friday. Goldman Sachs said it was particularly bullish on UK homebuilders and banks that have struggled recently. “Clarity on the UK’s terms of exit from the EU should unlock pent-up business investment; the reversal of a decade of fiscal consolidation should provide a fillip to domestic demand; and a pick-up in global growth should underpin a recovery in net exports,” the bank said in a note.
- Coming up:
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.