






Market Brief Short squeeze continues on US China trade and Brexit optimism
A summary of news and snapshot of moves ahead of the US session.
Share this:

- At midday in London, GBP was the strongest while the JPY was the weakest among major currencies. Stocks continued to push sharply higher following yesterday’s big rally. Oil and copper prices found further support, while safe-haven gold eased back after its earlier rebound. In other words, it was risk ON at the time of writing.
- GBP/USD and GBP crosses continued to hit repeated session highs this morning. This comes on the back of "constructive" Brexit talks between EU and UK negotiators Michel Barnier and Stephen Barclay this morning, and after leaders of the UK & Ireland held detailed discussions yesterday, agreeing that they could see a "pathway to a possible deal." Lots of optimistic headlines, even if nothing has changed fundamentally. Traders are evidently happy to be buying the rumours and will be asking questions later.
- Key data this afternoon from North America is Canada’s employment report, which is expected to show 11,200 new net jobs created last month. Meanwhile US consumer Sentiment is expected to ease to 92.0 from 93.2 previously.
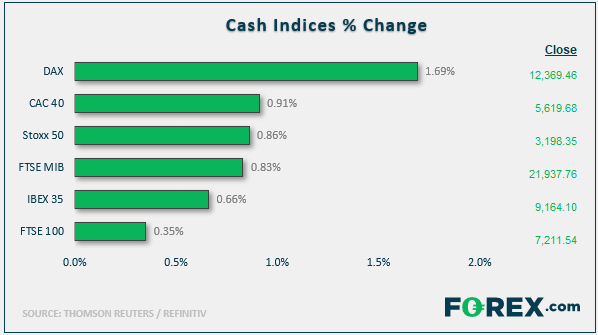
- Global stocks continued to rally on the back of optimism the US and China will reach an agreement of some sort to prevent any further escalation in their bitter trade war. Following the conclusion of the first day of talks, investors expressed optimism that they might be able to ease the conflict and delay a planned US tariff hike scheduled for next week. Trade-sensitive DAX was the strongest European index, while the FTSE underperformed because of the pound’s big rally and despite sharp gains for some individual names on Brexit hopes-related (see below). US index futures were up around 1%, suggesting Wall Street will gap higher at the open – unless, something big happens, for example Trump cancelling his scheduled meeting with Chinese Vice Premier Lie He at 14:45 EDT today.
- In company news
- SAP, Europe's most valuable technology company, was up sharply on the back of strong third-quarter results
- Publicis tumbled more than 10% after the ad firm lowered its full-year sales target for the second time this year. The news also weighed on London rival WPP.
- Hugo Boss dropped sharply after the fashion house cut its 2019 earnings forecast and reported third quarter results below expectations.
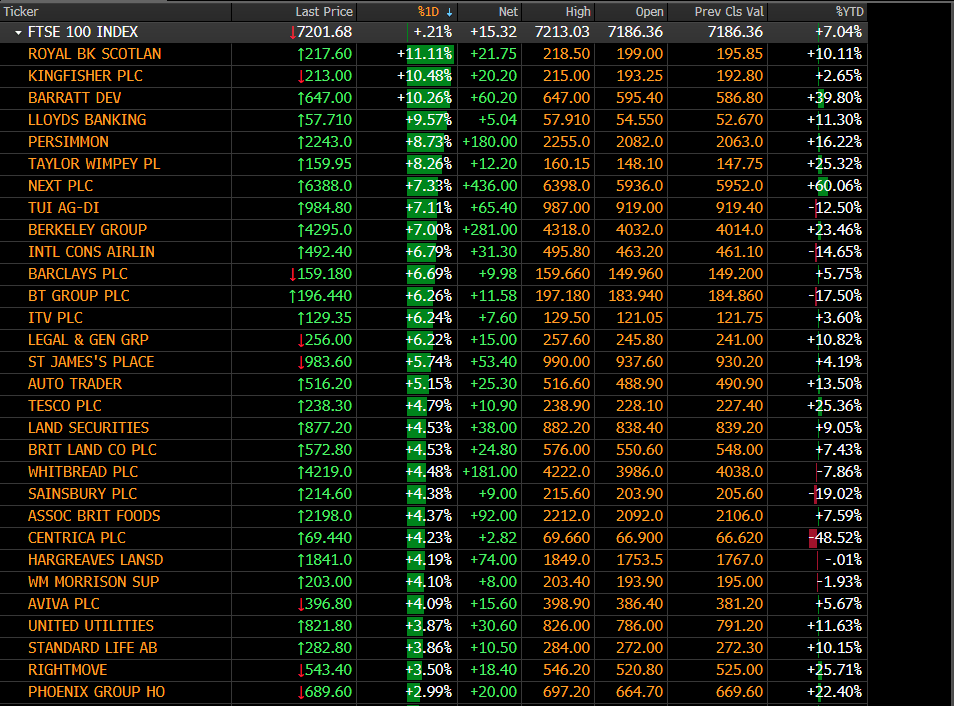
- RBS and LLOYDS shares were up more 10% each this morning on Brexit optimism. Here are today’s big risers, mostly due to Brexit optimism, courtesy of Bloomberg and colleague Ken Odeluga:
- At midday in London, GBP was the strongest while the JPY was the weakest among major currencies. Stocks continued to push sharply higher following yesterday’s big rally. Oil and copper prices found further support, while safe-haven gold eased back after its earlier rebound. In other words, it was risk ON at the time of writing.
- GBP/USD and GBP crosses continued to hit repeated session highs this morning. This comes on the back of "constructive" Brexit talks between EU and UK negotiators Michel Barnier and Stephen Barclay this morning, and after leaders of the UK & Ireland held detailed discussions yesterday, agreeing that they could see a "pathway to a possible deal." Lots of optimistic headlines, even if nothing has changed fundamentally. Traders are evidently happy to be buying the rumours and will be asking questions later.
- Key data this afternoon from North America is Canada’s employment report, which is expected to show 11,200 new net jobs created last month. Meanwhile US consumer Sentiment is expected to ease to 92.0 from 93.2 previously.
- Global stocks continued to rally on the back of optimism the US and China will reach an agreement of some sort to prevent any further escalation in their bitter trade war. Following the conclusion of the first day of talks, investors expressed optimism that they might be able to ease the conflict and delay a planned US tariff hike scheduled for next week. Trade-sensitive DAX was the strongest European index, while the FTSE underperformed because of the pound’s big rally and despite sharp gains for some individual names on Brexit hopes-related (see below). US index futures were up around 1%, suggesting Wall Street will gap higher at the open – unless, something big happens, for example Trump cancelling his scheduled meeting with Chinese Vice Premier Lie He at 14:45 EDT today.
- In company news
- SAP, Europe's most valuable technology company, was up sharply on the back of strong third-quarter results
- Publicis tumbled more than 10% after the ad firm lowered its full-year sales target for the second time this year. The news also weighed on London rival WPP.
- Hugo Boss dropped sharply after the fashion house cut its 2019 earnings forecast and reported third quarter results below expectations.
- RBS and LLOYDS shares were up more 10% each this morning on Brexit optimism. Here are today’s big risers, mostly due to Brexit optimism, courtesy of Bloomberg and colleague Ken Odeluga:
Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.


GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.

Australian Dollar Technical Outlook: AUD/USD Breakdown Threatens Deeper Correction 9 23 2026
AUD/USD remains under pressure after breaking key trend support, with the latest decline putting the focus on the next major downside pivot.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.