



Market Brief Stocks Shrug Off Lackluster Wage Growth
See a summary of the top market themes and trends from today's US trading session!
Share this:

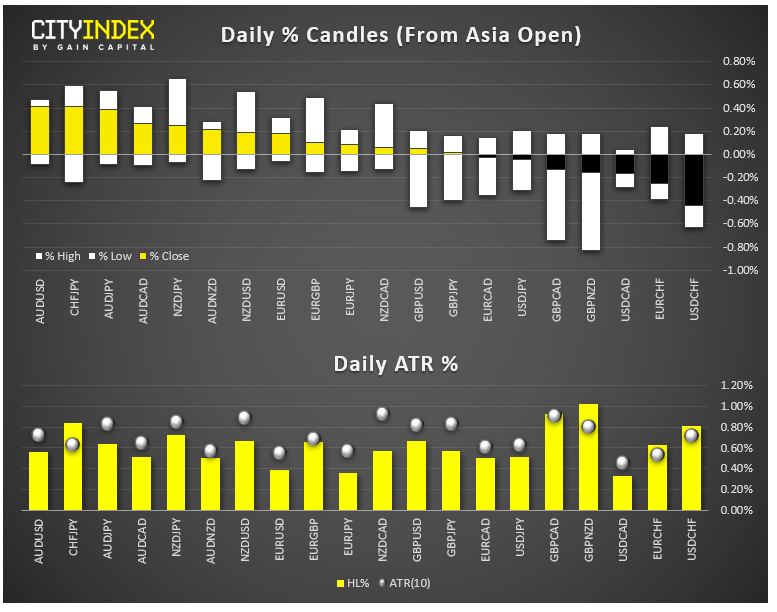
- FX: The Australian dollar was the strongest major currency on the day, with the British pound and US dollar bringing up the rear. The pound was hurt by fears over the viability of PM Boris Johnson’s Brexit proposal and his repeated emphasis on leaving the EU at the end of the month, with or without a deal.
- US data: US Non-Farm Payrolls (Sept) printed at 136k, roughly in-line with the 145k reading expected, but the details of the report were mixed: previous revisions added +45k jobs to the total, but wages were flat (0.0% m/m). The unemployment rate ticked down to 3.5%, a 50-year low.
- Commodities: Gold was essentially flat on the day while oil ticked higher in quiet trade.
- See the key economic reports and market trends we’ll be watching in the coming week!

- US indices closed roughly 1% higher in a “sell the rumor, buy the fact” reaction to this morning’s NFP report.
- All eleven major sectors rose on the day, led by Financial (XLF). Materials stocks (XLB) brought up the rear on the day.
- Stocks on the move:
- Apple (AAPL) rose nearly 3% after a report that the company had asked suppliers to increase production of the iPhone 11 by 10%.
- PC and printer manufacturer HP (HPQ) shed -10% after announcing plans to layoff thousands of workers and refocus its business on software and services.


- FX: The Australian dollar was the strongest major currency on the day, with the British pound and US dollar bringing up the rear. The pound was hurt by fears over the viability of PM Boris Johnson’s Brexit proposal and his repeated emphasis on leaving the EU at the end of the month, with or without a deal.
- US data: US Non-Farm Payrolls (Sept) printed at 136k, roughly in-line with the 145k reading expected, but the details of the report were mixed: previous revisions added +45k jobs to the total, but wages were flat (0.0% m/m). The unemployment rate ticked down to 3.5%, a 50-year low.
- Commodities: Gold was essentially flat on the day while oil ticked higher in quiet trade.
- See the key economic reports and market trends we’ll be watching in the coming week!

- US indices closed roughly 1% higher in a “sell the rumor, buy the fact” reaction to this morning’s NFP report.
- All eleven major sectors rose on the day, led by Financial (XLF). Materials stocks (XLB) brought up the rear on the day.
- Stocks on the move:
- Apple (AAPL) rose nearly 3% after a report that the company had asked suppliers to increase production of the iPhone 11 by 10%.
- PC and printer manufacturer HP (HPQ) shed -10% after announcing plans to layoff thousands of workers and refocus its business on software and services.

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.


GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.

Australian Dollar Technical Outlook: AUD/USD Breakdown Threatens Deeper Correction 9 23 2026
AUD/USD remains under pressure after breaking key trend support, with the latest decline putting the focus on the next major downside pivot.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.