





Market brief Swissy breaks through parity
A summary of news and snapshot of moves ahead of the US session.
Share this:

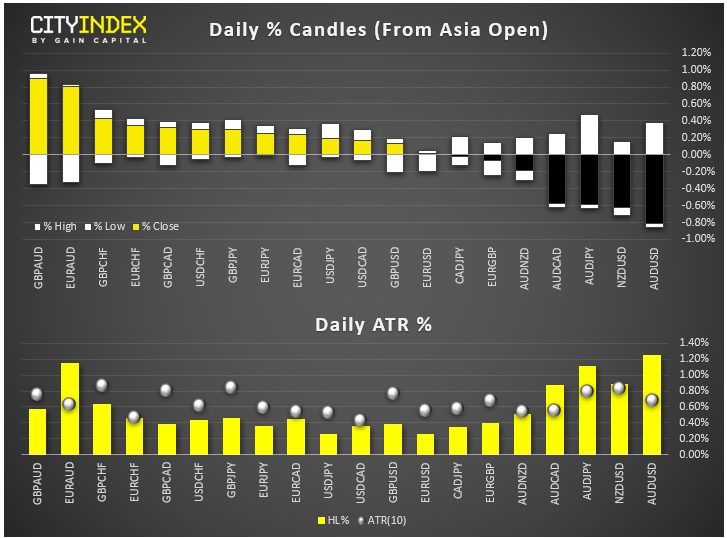
- At midday in London the GBP and EUR were among the strongest while the AUD, NZD and CHF were the weakest
- The economic calendar is full of data today and so far, the biggest event was the RBA’s rate cut, a decision which was mostly priced in - although the central bank still surprised the markets by providing a more dovish assessment of the economy and indicated rates could be loosened further if needed.
- The EUR rose even though the Eurozone headline CPI fell further in September to 0.9% y/y, when an unchanged reading of 1.0% was expected. Core CPI rose however to 1.0% from 0.9%, in line with expectations. Meanwhile, the latest Manufacturing PMIs from the UK (48.3 vs. 47.0 expected) and Japan (Tankan) both beat, while those from Italy (47.8 vs. 48.2), Spain (47.7 vs. 48.2) and Switzerland (44.6 vs. 46.5) all disappointed. Still, Eurozone final PMI was revised a touch higher (to 45.7) thanks to a small positive revision for Germany. Nevertheless, all the above-mentioned PMIs remained below the boom/bust level of 50.0, pointing to falling economic activity and underscoring the need for further monetary stimulus by major central banks. Among the notable movers in FX, the USD/CHF broke above parity as Switzerland’s retail sales printed -1.4% y/y vs. +1.6% expected and the manufacturing PMI also disappointed as per above.
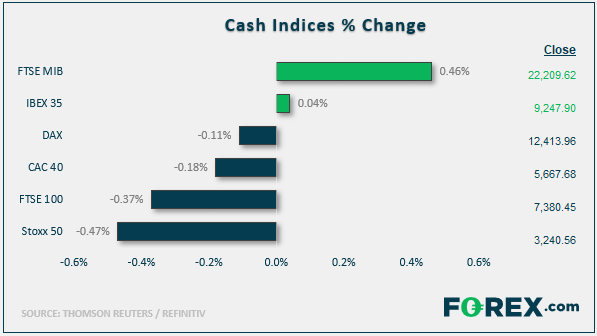
- The Swiss franc and other safe haven assets such as gold and Japanese yen have been weighed down in recent days by ongoing risk-on trade with stocks remaining overall supported (even if the EU indices started today’s session on the back foot) amid US-China trade optimism and central bank support.
- Is today’s weak start for European stocks due to fund managers rebalancing their portfolios? After all, Q3 ended with a bang for global indices. The S&P 500 recovered from a bad August to record its biggest year-to-date gain in more than 20 years. In Europe, too, the indices recovered to end Q3 noticeably higher. With central banks remaining in expansionary policy mode, and optimism rising that a US-China deal might be imminent, the stock market bulls are happy to keep buying every dip – for now.

- At midday in London the GBP and EUR were among the strongest while the AUD, NZD and CHF were the weakest
- The economic calendar is full of data today and so far, the biggest event was the RBA’s rate cut, a decision which was mostly priced in - although the central bank still surprised the markets by providing a more dovish assessment of the economy and indicated rates could be loosened further if needed.
- The EUR rose even though the Eurozone headline CPI fell further in September to 0.9% y/y, when an unchanged reading of 1.0% was expected. Core CPI rose however to 1.0% from 0.9%, in line with expectations. Meanwhile, the latest Manufacturing PMIs from the UK (48.3 vs. 47.0 expected) and Japan (Tankan) both beat, while those from Italy (47.8 vs. 48.2), Spain (47.7 vs. 48.2) and Switzerland (44.6 vs. 46.5) all disappointed. Still, Eurozone final PMI was revised a touch higher (to 45.7) thanks to a small positive revision for Germany. Nevertheless, all the above-mentioned PMIs remained below the boom/bust level of 50.0, pointing to falling economic activity and underscoring the need for further monetary stimulus by major central banks. Among the notable movers in FX, the USD/CHF broke above parity as Switzerland’s retail sales printed -1.4% y/y vs. +1.6% expected and the manufacturing PMI also disappointed as per above.
- The Swiss franc and other safe haven assets such as gold and Japanese yen have been weighed down in recent days by ongoing risk-on trade with stocks remaining overall supported (even if the EU indices started today’s session on the back foot) amid US-China trade optimism and central bank support.
- Is today’s weak start for European stocks due to fund managers rebalancing their portfolios? After all, Q3 ended with a bang for global indices. The S&P 500 recovered from a bad August to record its biggest year-to-date gain in more than 20 years. In Europe, too, the indices recovered to end Q3 noticeably higher. With central banks remaining in expansionary policy mode, and optimism rising that a US-China deal might be imminent, the stock market bulls are happy to keep buying every dip – for now.
Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.


GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.

Australian Dollar Technical Outlook: AUD/USD Breakdown Threatens Deeper Correction 9 23 2026
AUD/USD remains under pressure after breaking key trend support, with the latest decline putting the focus on the next major downside pivot.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.