



Markets Rebound as Tariff Fears Stir, Fed Cuts Eyed
US equities bounced back Monday, led by small caps and tech, even as President Trump warned of steep India tariffs. Fed cut bets persist after dovish remarks from Mary Daly, but a September move remains uncertain. Oil, gold, and copper were flat, while crypto slipped. All eyes turn to today’s ISM and S&P PMI data, with earnings from AMD, Pfizer, and Caterpillar likely to shape short-term sentiment.
Share this:

Market Summary – Tuesday, August 5
- US Stocks Rebound: US equities rose on Monday, recovering from last week’s losses. The small-cap Russell 2000 outperformed, while Communication, Utilities, and Technology sectors led gains. Energy stocks lagged due to falling oil and gas prices, though crude bounced slightly after President Trump threatened steep tariffs on India for reselling Russian oil.
- Tariff Alert: President Trump pledged to "substantially" raise tariffs on India in response to its Russian oil trade. The announcement pressured energy markets early in the session before a partial recovery.
- US Dollar Strengthens: The dollar firmed broadly, especially against the Swiss franc, Australian dollar, and New Zealand dollar, weighing on global market sentiment.
- Fed Outlook: Fed’s Mary Daly reiterated two rate cuts are still likely this year, though a September cut remains uncertain. Goldman Sachs also sees a potential 50bps cut if unemployment rises sharply. Labor market data remains the key driver for Fed policy decisions.
- Japan & BoJ: The Bank of Japan minutes confirmed a cautious tone despite inflation overshooting forecasts. While they’re open to more hikes if data supports it, they're monitoring risks. Japan’s services PMI rose to 53.6, driven by domestic demand, though hiring slowed due to tight budgets.
- China Services Sector Grows: China's July Services PMI climbed to 52.6—highest since May 2024—boosted by domestic demand and tourism. Companies raised prices amid rising input costs, and employment also increased. However, overall economic momentum slowed slightly, with the composite PMI dipping to 50.8.
- Commodities:
- Oil: Crude futures were subdued after recent declines and the OPEC+ output hike, though they recovered from lows on tariff headlines.
- Copper: Copper prices held steady, helped by risk-on sentiment and China's stronger services data.
- Gold: Spot gold traded flat, capped by a firmer US dollar.
- Libya: Libya's NOC signed an MoU with ExxonMobil, restarting exploration activity after a decade.
- Crypto & Regulation:
- Bitcoin edged lower, slipping below $115,000.
- The CFTC will allow spot crypto contracts to trade on registered futures exchanges.
- The US Genius Act will enable businesses to integrate stablecoins, and some brokers have already adopted this feature.
- Key Data Today (US):
- 15:45 – S&P Global Services PMI (Jul): Expected 55.2 (prev. 52.9)
- 16:00 – ISM Non-Manufacturing PMI (Jul): Expected 51.5 (prev. 50.8)
- 16:00 – ISM Non-Manufacturing Prices (Jul): Previous 67.5
- Earnings on Watch:
- AMD (EPS est. $0.48, Revenue $7.41B)
- Arista Networks
- SMC
- Snap Inc.
- Pfizer
- Caterpillar
- Dax Technical Analysis 4 hours
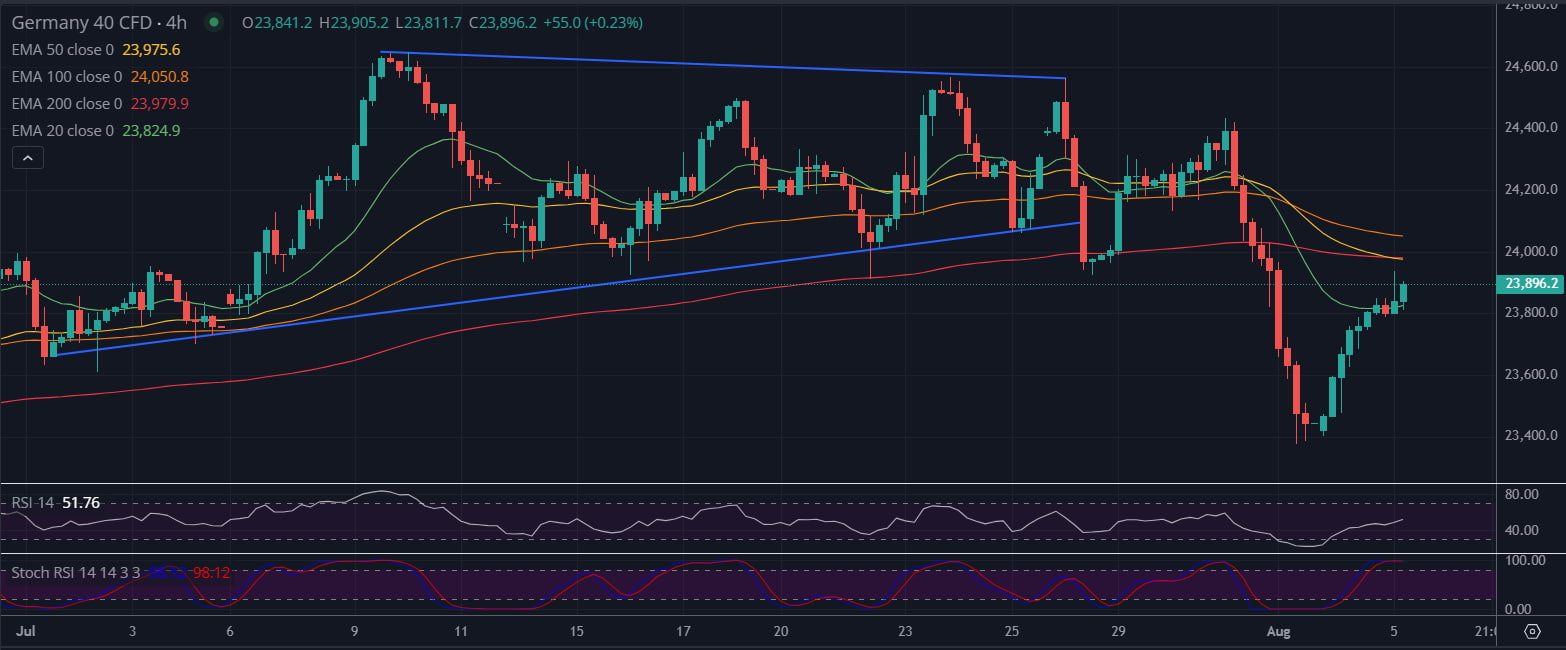
- The DAX is showing a continuation of the recovery that began after the sharp breakdown from the symmetrical triangle. Price action has rebounded strongly from the 23,300 area and is now approaching the key 23,900–24,000 resistance zone. This area also overlaps with the 20-period EMA and prior breakdown level, which could act as short-term resistance.
- Momentum indicators suggest bullish traction is still in play. The RSI has reclaimed the midline near 50 and is heading upward, while the Stochastic RSI has entered overbought territory, hinting that the upside may be facing near-term exhaustion. For bulls to regain full control, a close above 24,000 would be essential, confirming a potential false breakdown and opening the door for a move toward the upper 24,300s. Conversely, failure to clear this area could trigger renewed downside pressure.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.


RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.