



S&P 500 outlook: Stocks approach new highs
In this mostly technically focused S&P 500 outlook article, we are highlighting the upside potential of the US benchmark index, where we think hitting a new all time high might be just a matter of time, with a potential for an extension to the next big level of 7,000 – barring a major setback in US-China trade talks.
Share this:
US markets pushed higher after the open, tracking a firmer risk tone observed elsewhere across financial markets with European stocks, cryptocurrencies and copper all pushing higher. In this mostly technically focused S&P 500 outlook article, we are highlighting the upside potential of the US benchmark index, where we think hitting a new all time high might be just a matter of time, with a potential for an extension to the next big level of 7,000 – barring a major setback in US-China trade talks.
Analysis: What factors are helping the S&P 500 outlook?
The major indices hovered just below record highs, shrugging off a mixed set of US and European earnings today in what has otherwise been a rather good earnings season for the S&P 500 companies thus far. The real headline, however, came from the oil market, as crude prices surged to a two-week high following fresh US sanctions on Russia’s largest producers. The jump in oil prices lifted energy names like BP and Shell, helping to nudge the FTSE 100 to a new record high. Will we see new records on Wall Street? For now, hopes for interest rate cuts continue to underpin the S&P 500 outlook, even as renewed uncertainty around US-China trade relations keeps a lid on broader enthusiasm. Washington’s latest suggestion that it might restrict software exports to China threatens to reignite tensions, but upbeat comments from Trump this week have helped temper those fears. Traders are now watching Friday’s delayed US inflation print closely for fresh clues on the Federal Reserve’s next move. So far, expectations of two more cuts this year has helped to provide support for stocks.

Crude oil steals the spotlight
Oil prices dominated overnight headlines, extending gains after President Trump announced sanctions against major Russian oil companies. The move propelled WTI crude more than $5 higher from last week’s multi-month low near $60 a barrel. Interestingly, this sharp jump has yet to dent overall risk appetite. US equity indices remain buoyant, and even cryptocurrencies have joined the rebound.
Whether these sanctions meaningfully disrupt Russian supply — and thus justify such a swift repricing — remains to be seen. For now, the reaction appears largely contained to the energy market, without spilling over into broader financial sentiment. Still, with energy costs feeding into inflation expectations, traders will be watching closely to see whether this adds a new wrinkle to the S&P 500 outlook in the coming days.
Technical picture: Key S&P 500 levels to watch
From a technical perspective, the S&P 500 outlook remains firmly bullish. After a 2.5% pullback in early October, the index briefly slipped below several short-term moving averages and key support zones, luring in short sellers. But last week’s swift rebound served as a reminder of one of the market’s timeless truths — the trend is still your friend.
Despite some choppy sessions this week, the S&P 500 continues to trade above reclaimed moving averages and previous support areas, keeping the broader uptrend intact. The index, along with other major global benchmarks, continues to form higher highs and higher lows — a classic sign of sustained bullish momentum.
A genuine trend reversal would require a decisive break below critical supports and a confirmed topping formation, neither of which has emerged yet. As it stands, dip-buying remains the strategy of choice among traders betting on further strength in the S&P 500 outlook.
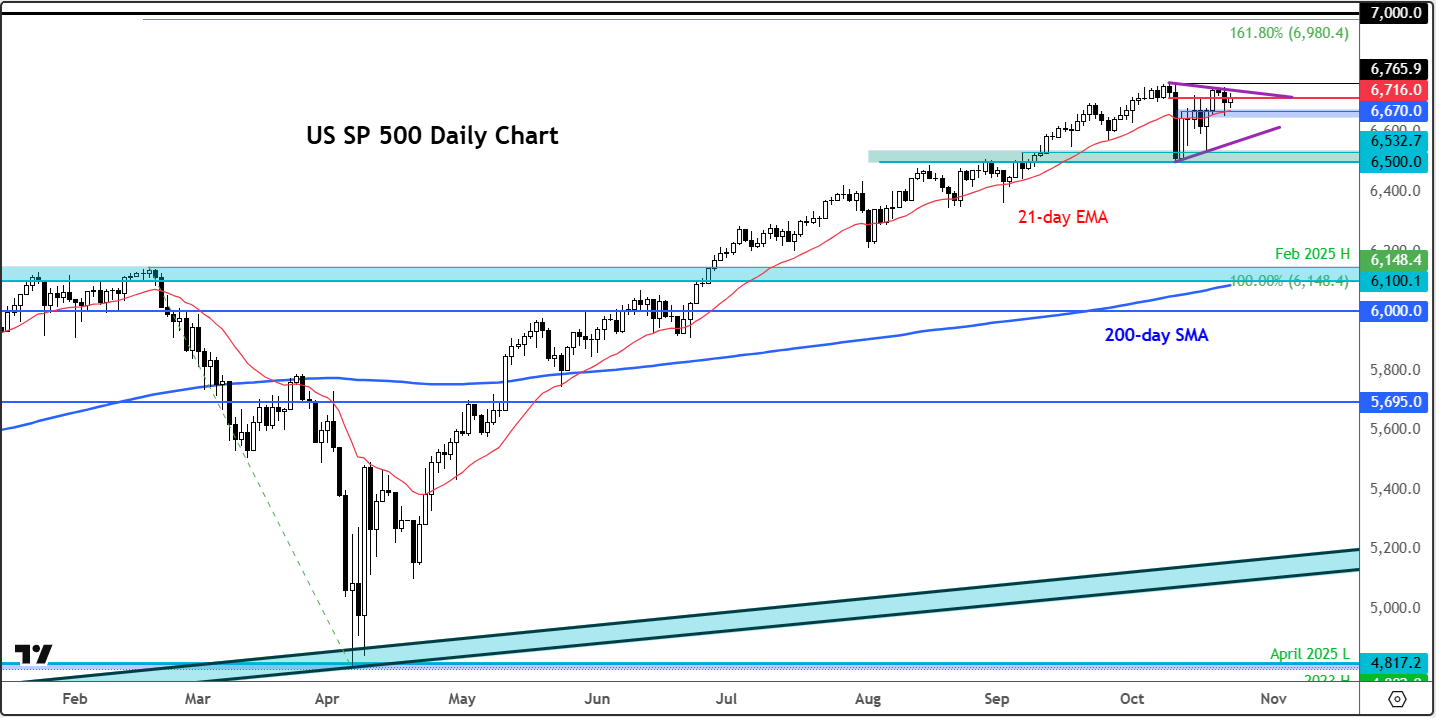
Immediate support sits around 6670-80 area on our US SP 500 chart, which is derived from the underlying S&P 500 futures — a zone reinforced by last week’s daily highs and the 21-day exponential moving average. Below that 6,600 is another key zone, while the month’s low at 6,500 marks a crucial line in the sand where many stop orders are likely clustered.
On the upside, resistance is seen around 6,716-6723 area, which had acted as both prior support and marks Tuesday’s low. A clear move above that zone would open the path towards the all-time high at 6766, followed by the next round handles of 6,800 and 6,900, and then the psychologically important 7,000 level beyond that.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.

The RBA Hiked Rates and the Australian Dollar Still Fell
AUD/USD fell after the RBA rate hike because the central bank's hawkish stance was already priced in while the U.S. dollar stayed firm.

EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.