



S&P 500 forecast - stocks edge higher ahead of data: US Open
Stocks edge cautiously higher, despite oil posting further gains. US factory orders and JOLTS job openings will be in focus.
Share this:

US futures
Dow futures +0.08% at 33593
S&P futures +0.25% at 4133
Nasdaq futures +0.3% at 13183
In Europe
FTSE +0.18% at 7685
Dax +0.96% at 15715
- US factor orders & JOLTS job opening in focus
- Oil prices extend gains
- GBP rises with BoE Hue Pill due to speak
JOLTS job openings & US factory orders due
US stocks are pointing to a modestly higher start after a mixed closed yesterday, as investors continue to digest rising oil prices which could impact the Fed’s path for interest rates and look ahead to more data.
The rise in oil prices makes the Fed’s job to rein in inflation more complicated. This could ultimately mean higher interest rates for longer. That said, the market is still pricing in two rate cuts by the end of the year. Although the market is pricing in a 58% chance of a rate hike in May, following the OPEC cut.
Looking ahead, attention is on US factory orders which are expected to fall -0.5% MoM in February, down from -1,5% in January. The data comes after the US manufacturing PMI fell to an almost 2-year low.
US JOLTS job openings are also in focus and are expected to show a small decline to 10.4 million, down from 10.8 million. The data is inline with a tight labour market and comes ahead of Frida’s non-farm payroll report.
Corporate news
Virgin Orbit drops 24% pre-market after the cash-strapped space-launch firm filed for Chapter 11 bankruptcy.
Walmart will be under the spotlight as a two-day investor and analyst meeting begins. This comes amid reports that the retail giant is set to cut 2000 jobs.
Tesla rises 0.8% after steep losses yesterday and after the EV maker sold 88,869 China-made vehicles in March, up 35% year on year.
Where next for the S&P?
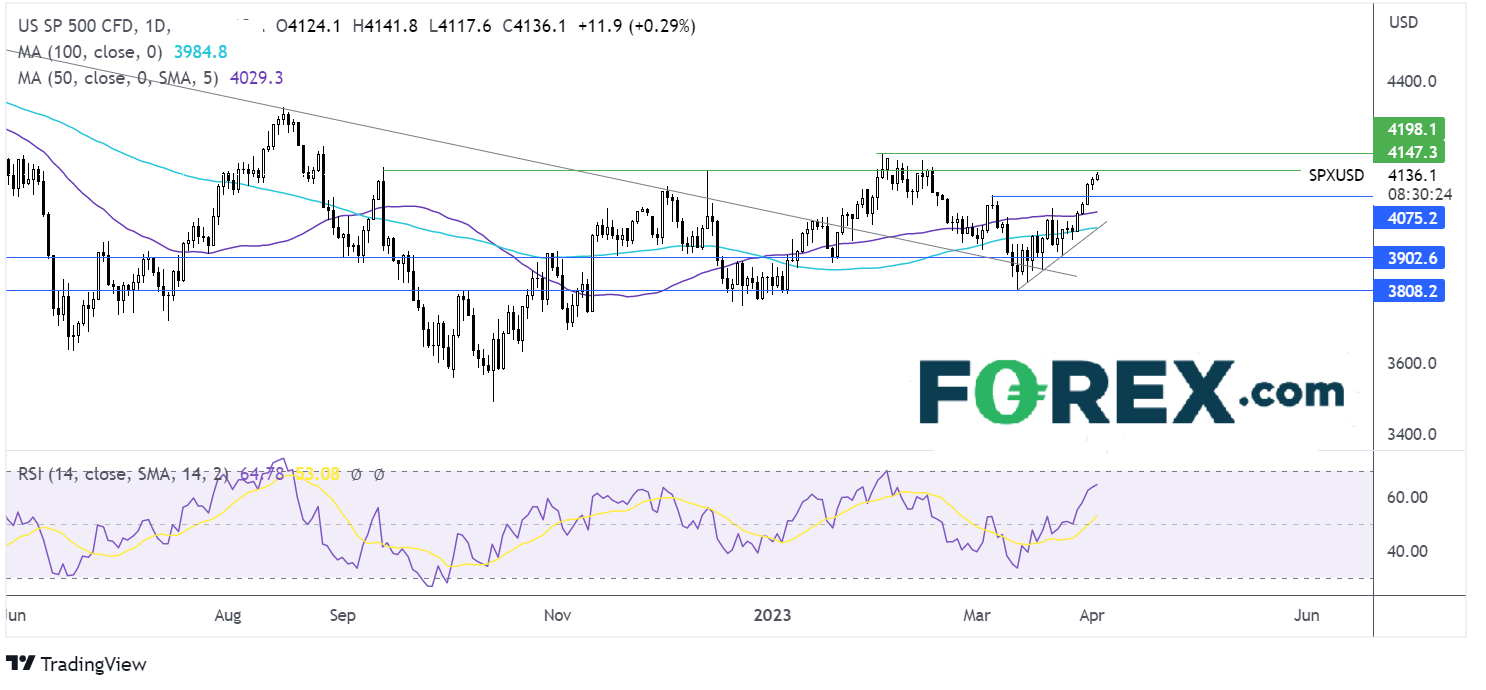
The S&P500 is approaching a key resistance level at 4145, the December high. Break above here is needed to bring 4200, the 2023 high into target. Meanwhile, a break below the 50 sma at 4030 opens the door to 3980, the 100 sma, and the rising trendline resistance. A break below here negates the near-term uptrend.
FX markets – USD falls, GBP jumps
The USD is falling, extending losses from yesterday as the markets bet that the end of the Fed’s rate hiking cycle is near. US data and Fed speakers will provide further clues.
EUR/USD is flat around 1.09 after the eurozone PPI cooled by more than expected to 13.2% YoY in February, down from 15% in January. Eurozone consumer inflation expectations fell to a one-year low at 4.6%, and inflation in three years’ time to be 2.4%.
GBP/USD is rising, adding to 1% gains from yesterday, supported by BoE – Fed divergence. April is also typically a strong month for the cable, given it has risen 8 of the past 10 years in April. BoE Chief Economist Huw Pill is due to speak today.
EUR/USD +0.08% at 1.09
GBP/USD +0.5% at 1.2482
Oil extends gain
Oil prices are extending gains after the OPEC+ oil production cut announcement at the weekend. Oil prices trade over 7% higher this week and are up 16% across the past 10 days.
UBS is forecasting Brent will rise to $100 the barrel by the end of the coming quarter. Goldman Sachs also upwardly revised the oil prices forecast.
WTI crude trades +0.8% at $81.05
Brent trades at +0.8% at $85.44
Looking ahead
15:00 US factory orders
15:00 Job openings
US futures
Dow futures +0.08% at 33593
S&P futures +0.25% at 4133
Nasdaq futures +0.3% at 13183
In Europe
FTSE +0.18% at 7685
Dax +0.96% at 15715
- US factor orders & JOLTS job opening in focus
- Oil prices extend gains
- GBP rises with BoE Hue Pill due to speak
Learn more about trading indices
JOLTS job openings & US factory orders due
US stocks are pointing to a modestly higher start after a mixed closed yesterday, as investors continue to digest rising oil prices which could impact the Fed’s path for interest rates and look ahead to more data.
The rise in oil prices makes the Fed’s job to rein in inflation more complicated. This could ultimately mean higher interest rates for longer. That said, the market is still pricing in two rate cuts by the end of the year. Although the market is pricing in a 58% chance of a rate hike in May, following the OPEC cut.
Looking ahead, attention is on US factory orders which are expected to fall -0.5% MoM in February, down from -1,5% in January. The data comes after the US manufacturing PMI fell to an almost 2-year low.
US JOLTS job openings are also in focus and are expected to show a small decline to 10.4 million, down from 10.8 million. The data is inline with a tight labour market and comes ahead of Frida’s non-farm payroll report.
Corporate news
Virgin Orbit drops 24% pre-market after the cash-strapped space-launch firm filed for Chapter 11 bankruptcy.
Walmart will be under the spotlight as a two-day investor and analyst meeting begins. This comes amid reports that the retail giant is set to cut 2000 jobs.
Tesla rises 0.8% after steep losses yesterday and after the EV maker sold 88,869 China-made vehicles in March, up 35% year on year.
Where next for the S&P?
The S&P500 is approaching a key resistance level at 4145, the December high. Break above here is needed to bring 4200, the 2023 high into target. Meanwhile, a break below the 50 sma at 4030 opens the door to 3980, the 100 sma, and the rising trendline resistance. A break below here negates the near-term uptrend.

FX markets – USD falls, GBP jumps
The USD is falling, extending losses from yesterday as the markets bet that the end of the Fed’s rate hiking cycle is near. US data and Fed speakers will provide further clues.
EUR/USD is flat around 1.09 after the eurozone PPI cooled by more than expected to 13.2% YoY in February, down from 15% in January. Eurozone consumer inflation expectations fell to a one-year low at 4.6%, and inflation in three years’ time to be 2.4%.
GBP/USD is rising, adding to 1% gains from yesterday, supported by BoE – Fed divergence. April is also typically a strong month for the cable, given it has risen 8 of the past 10 years in April. BoE Chief Economist Huw Pill is due to speak today.
EUR/USD +0.08% at 1.09
GBP/USD +0.5% at 1.2482
Oil extends gain
Oil prices are extending gains after the OPEC+ oil production cut announcement at the weekend. Oil prices trade over 7% higher this week and are up 16% across the past 10 days.
UBS is forecasting Brent will rise to $100 the barrel by the end of the coming quarter. Goldman Sachs also upwardly revised the oil prices forecast.
WTI crude trades +0.8% at $81.05
Brent trades at +0.8% at $85.44
Learn more about trading oil here.
Looking ahead
15:00 US factory orders
15:00 Job openings
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.


RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.