



The Hang Seng rises on soft inflation data from China
China’s consumer and producer prices continued to deflate in March, which helped further boost sentiment in today’s Asian session.
Share this:
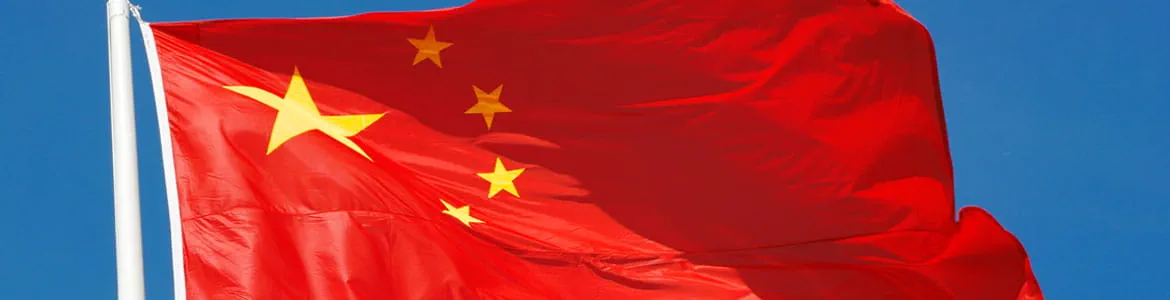
China’s inflation data for March
- CPI fell to an 18-month low of 0.7% y/y (below 1% prior, 1% forecast)
- Consumer prices contracted for a second consecutive month at -0.3% m/m (-0.5% prior, 0% forecast)
- Producer prices fell -2.5% y/y, its fastest rate of deflation since June 2020
- Food prices fell -1.4% m/m (2.5% y/y)
- Non-food items rose 0.3% y/y
China’s inflation data is an encouraging sign for deflation in general, because if prices are lower in key export countries like China then it places less upwards pressure on global prices. CPI contracted for a second consecutive month by 0.3% m/m, and headline CPI is at an 18-month low.
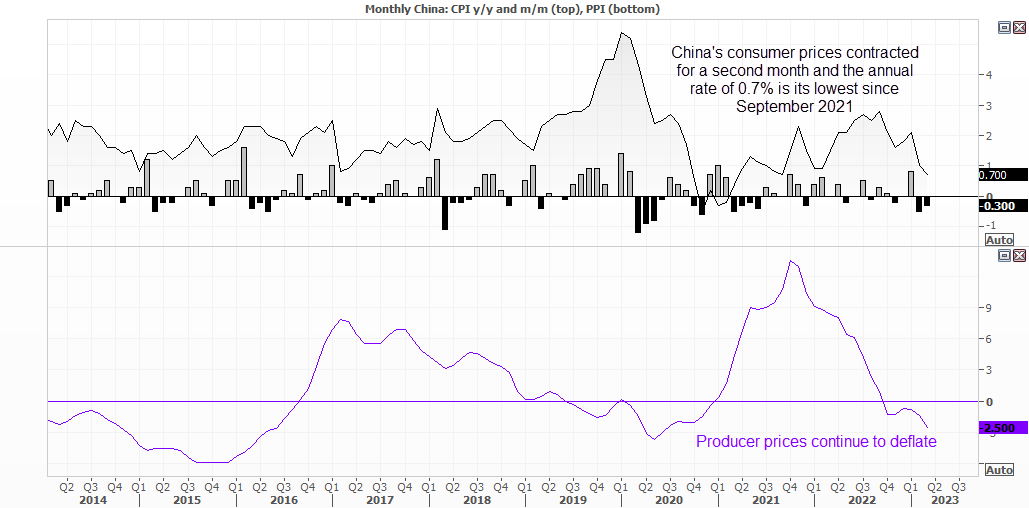
Hang Seng daily chart:
We’re getting a few mixed signals on the Hang Seng, although near-term risks appear skewed to the upside. The daily chart shows a bullish trend is developing, although daily volumes have been trending lower and below the 20-day average, which suggests weakness to this leg of the trend. We’ll need to wait for the daily close to confirm what we see on the OBV indicator (on balance volume), which is yet to break above its prior cycle high despite today’s rally on price action.
However, the pullback from last week’s highs found support at the moving average cluster it recently broke above, and a swing low appears to have formed on Thursday wit a Rikshaw man Doji. Therefore, we prefer to buy dips above 20,000 to see if it can move to 21,000 / February’s VPOC (volume point of control). And if a move higher is accompanied with an increase in daily trading volume and the OBV confirms the price action, we’ll have more confidence it can head for the January high.

-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
The RBA Hiked Rates and the Australian Dollar Still Fell
AUD/USD fell after the RBA rate hike because the central bank's hawkish stance was already priced in while the U.S. dollar stayed firm.


EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.

AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.