



US March CPI highest since December 1981
The large increase over last month’s reading was primarily due to an increase in food and energy prices.
Share this:

The US released March inflation data earlier today. The headline CPI print was 8.6% YoY vs 8.5% YoY expected and 7.9% in February. This was the highest inflation reading since December 1981! The large increase over last month’s reading was primarily due to an increase in food and energy prices. The core CPI for March, which excludes these volatile components, was “only” 6.5% YoY vs an expectation on 6.6% YoY and 6.4% YoY in February. This was the highest level since August 1982. These result help to further Fed Governor Evans claim from yesterday that a 50bps hike is highly likely at the May FOMC meeting.
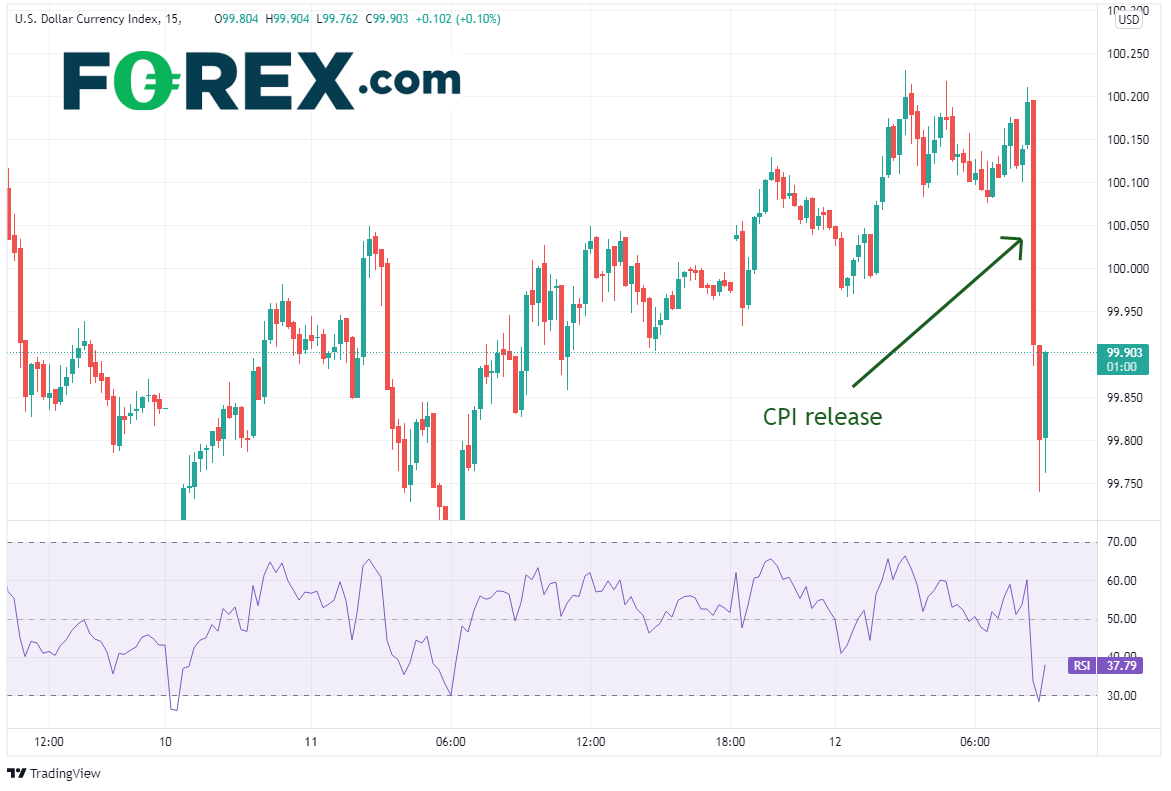
Yesterday, the White House warned the markets that these numbers would be strong, which led many to believe they would be stronger than estimates. However, after the release of the data, the markets felt a sense of relief (fearing the prints could be worse) and the US Dollar moved lower. Price traded from 100.20 down to 99.74 before bouncing.
Source: Tradingview, Stone X
On a 240-minute timeframe, DXY has been moving higher in an orderly channel since March 31st. However, yesterday the US Dollar Index began moving sideways and traded out of the channel. Although it reached a near-term new high today at 100.23, the RSI is diverging, which was a signal price may have been ready for a pullback. Support is at the March 28th highs near 99.37. Below there, price can fall to the lows from March 30th at 97.74. First resistance is at the bottom trendline of the upward sloping channel and the 161.8% Fibonacci extension level from the highs of March 28th to the low of March 30th near 100.41. Above there price can trade to the highs from April 2020 at 100.93.

Source: Tradingview, Stone X
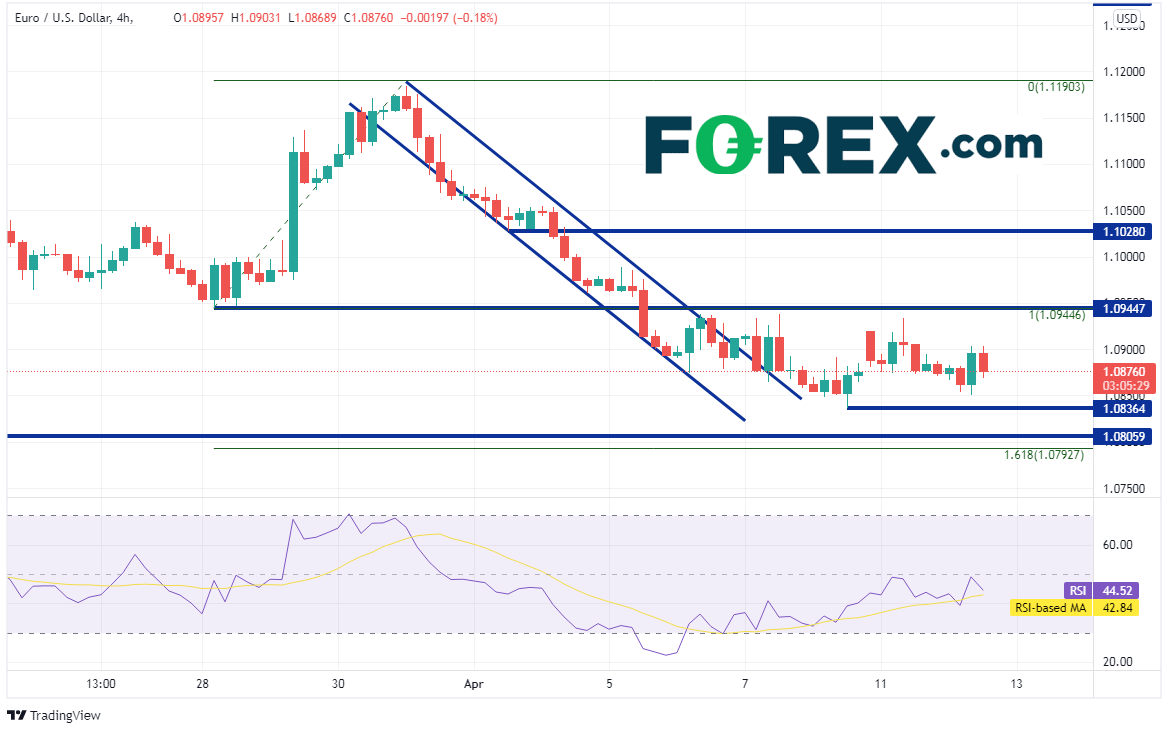
EUR/USD has been moving in a similar, but opposite direction of DXY. Price had been moving lower in an orderly channel since March 31st and traded sideways, out of the channel. However, unlike the DXY, EUR/USD did not make a new near-term low today. First support is at the lows from April 8th near 1.0836, then the lows from March 7th at 1.0806. Just below there, support is at the 161.8% Fibonacci extension from the lows of March 28th to the highs of March 31st, near 1.0792. Resistance is at the March 28th lows near 1.0945, then horizontal resistance at 1.1028. If price breaks above there, it can run to the highs of March 31st at 1.1190.
Source: Tradingview, Stone X
US CPI came in hot today! However, markets may have expected it, thanks to a warning from the White House yesterday. Therefore, traders may have sensed a little relief that the number wasn’t worse and markets did the opposite of what one may expect. Watch to see if the markets correct themselves over the next few days, especially if more talks of a 50bps hike at the May FOMC meeting begin to make the rounds!
The US released March inflation data earlier today. The headline CPI print was 8.6% YoY vs 8.5% YoY expected and 7.9% in February. This was the highest inflation reading since December 1981! The large increase over last month’s reading was primarily due to an increase in food and energy prices. The core CPI for March, which excludes these volatile components, was “only” 6.5% YoY vs an expectation on 6.6% YoY and 6.4% YoY in February. This was the highest level since August 1982. These result help to further Fed Governor Evans claim from yesterday that a 50bps hike is highly likely at the May FOMC meeting.
Yesterday, the White House warned the markets that these numbers would be strong, which led many to believe they would be stronger than estimates. However, after the release of the data, the markets felt a sense of relief (fearing the prints could be worse) and the US Dollar moved lower. Price traded from 100.20 down to 99.74 before bouncing.

Source: Tradingview, Stone X
Trade DXY now: Login or Open a new account!
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
On a 240-minute timeframe, DXY has been moving higher in an orderly channel since March 31st. However, yesterday the US Dollar Index began moving sideways and traded out of the channel. Although it reached a near-term new high today at 100.23, the RSI is diverging, which was a signal price may have been ready for a pullback. Support is at the March 28th highs near 99.37. Below there, price can fall to the lows from March 30th at 97.74. First resistance is at the bottom trendline of the upward sloping channel and the 161.8% Fibonacci extension level from the highs of March 28th to the low of March 30th near 100.41. Above there price can trade to the highs from April 2020 at 100.93.

Source: Tradingview, Stone X
Trade EUR/USD now: Login or Open a new account!
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
EUR/USD has been moving in a similar, but opposite direction of DXY. Price had been moving lower in an orderly channel since March 31st and traded sideways, out of the channel. However, unlike the DXY, EUR/USD did not make a new near-term low today. First support is at the lows from April 8th near 1.0836, then the lows from March 7th at 1.0806. Just below there, support is at the 161.8% Fibonacci extension from the lows of March 28th to the highs of March 31st, near 1.0792. Resistance is at the March 28th lows near 1.0945, then horizontal resistance at 1.1028. If price breaks above there, it can run to the highs of March 31st at 1.1190.
Source: Tradingview, Stone X
US CPI came in hot today! However, markets may have expected it, thanks to a warning from the White House yesterday. Therefore, traders may have sensed a little relief that the number wasn’t worse and markets did the opposite of what one may expect. Watch to see if the markets correct themselves over the next few days, especially if more talks of a 50bps hike at the May FOMC meeting begin to make the rounds!
Learn more about forex trading opportunities.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.