



US open: Stocks fall after disappointing earnings & ahead of PMI data
Stocks falls as weak Home Depot and Walmart guidance knock risk sentiment. US PMI data awaited.
Share this:

US futures
Dow futures -0.65% at 33500
S&P futures -0.55% at 4043
In Europe
FTSE -0.38% at 79988
Dax -0.45% at 15440
- Walmart & Home Depot's guidance disappoints
- PMI data is expected to rise to 47.5
- GBP/USD rallies after private sector return to growth
- oil holds steady as investors weigh up recession concerns and China's reopening
Retailer earnings in focus
US stocks are set to open lower as investors digest disappointing earnings and rising concerns of a more hawkish Fed, while also looking ahead to US PMI data later in the session.
U.S. markets are set to extend losses from last week amid ongoing concerns that the Federal Reserve will need to raise interest rates higher and for longer in order to tame high inflation after a series of stronger-than-expected macro data releases last week, including hotter-than-forecast inflation.
The PMI data due later today is expected to shed further light on the health of the US economy. Expectations are for the composite PMI to improve by 47.5 in February, up from 46.8 in January. Existing home sales are also expected to improve. Stronger than forecast data fuel bets of a more aggressive Fed. It is worth noting that the PMI data in Europe was significantly stronger than forecast.
Separately geopolitical concerns are back under the spotlight as President Putin gave a keynote speech, which showed no hint of the Ukraine war coming to an end soon. Instead, Putin threatened the west with a nuclear response, hurting risk appetite.
In addition to Fed fears, earnings are less than impressive as the focus turns to retailers, which points to a struggling consumer.
Corporate news
Home Depot falls 4% pre-market after warning over profits as soaring inflation hits demand. The US home improvements chain posted a surprise fall in Q4 sales which comes after the boom years across the pandemic.
Walmart falls pre-market after earnings topped forecasts in the holiday quarter as it drew in shoppers but forecast annual earnings below estimates. EPS was $1.71 against $1.51 forecast, and revenue of $164.05 billion against $159.72. However, they are cautious on the year ahead as consumers remain under pressure.
Where next for the Nasdaq?
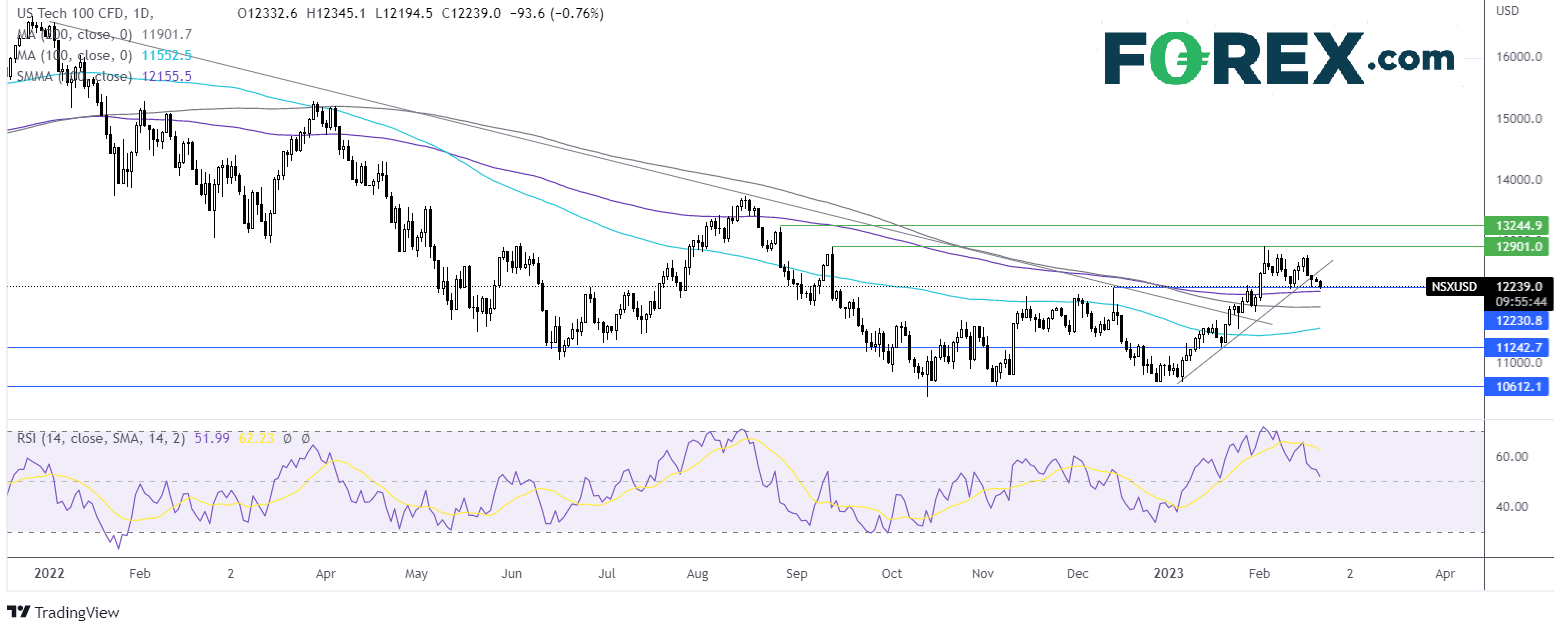
After forming a double top at 12750 the Nasdaq has fallen, breaking below the rising trendline dating back to the start of the year. Bears are looking to test support around the 12200 level, which has offered support and resistance over the past few months. A break below here, and the 100 sma exposes the 200 sma at 11900 with a break below here negating the near-term uptrend and bringing the 50 sma at 115265 into focus. Buyers need a break above 12750 and 12900 the February high to extend the bullish trend.
FX markets – USD & GBP rises
The USD is rising, tracking treasury yields higher as investors’ price in US interest rates rising higher and for longer to tackle inflation.
EUR/USD is falling owing to the stronger U.S. dollar and despite an impressive recovery in Eurozone PMIs. The flash composite rose to 52.3 in February, its highest level in nine months and well above the 50.6 level forecasts. The flash composite readings were positive in both France and Germany. German ZEW economic sentiment was also higher than forecast at 28.1, up from 16.9 as recession worries ease.
GBP/USD rebounding after stronger-than-expected UK PMI data. The composite PMI surged to 53 in February, up from 48.5 in January, calming fears of a recession in the UK. The dominant service sector drove the rebound in activity. The price sub-index, a good guide for inflation, cooled further, with costs rising at the slowest pace since April last year. The goldilocks report comes as the BoE weighs up another possible rate hike in March.
EUR/USD -0.30% at 1.0649
GBP/USD +0.51% at 1.21
Oil holds steady after yesterday’s gains
Oil prices holding steady, paring earlier losses and reversing gains from the previous session as investors weigh up stronger-than-expected PMI data against expectations of higher interest rates for longer, dampening global growth and hurting the demand outlook.
The focus of the financial markets in the Fed and the risk of the US central bank keeping rates elevated. This is also being offset by optimism surrounding China reopening and dim and ramping up.
Meanwhile, on the supply side, data shows that file flies to China hit the highest level since the start of the Ukraine war, surpassing a record set in April 2020.
WTI crude trades +0.25% at $77.50
Brent trades at +0.15% at $83.82
Looking ahead
14:45 US Composite PMI
15:00 US Existing home sales
19:00 ECB President Lagarde to speak
US futures
Dow futures -0.65% at 33500
S&P futures -0.55% at 4043
Nasdaq futures -0.92% at 12200
In Europe
FTSE -0.38% at 79988
Dax -0.45% at 15440
Learn more about trading indices
- Walmart & Home Depot's guidance disappoints
- PMI data is expected to rise to 47.5
- GBP/USD rallies after private sector return to growth
- oil holds steady as investors weigh up recession concerns and China's reopening
Retailer earnings in focus
US stocks are set to open lower as investors digest disappointing earnings and rising concerns of a more hawkish Fed, while also looking ahead to US PMI data later in the session.
U.S. markets are set to extend losses from last week amid ongoing concerns that the Federal Reserve will need to raise interest rates higher and for longer in order to tame high inflation after a series of stronger-than-expected macro data releases last week, including hotter-than-forecast inflation.
The PMI data due later today is expected to shed further light on the health of the US economy. Expectations are for the composite PMI to improve by 47.5 in February, up from 46.8 in January. Existing home sales are also expected to improve. Stronger than forecast data fuel bets of a more aggressive Fed. It is worth noting that the PMI data in Europe was significantly stronger than forecast.
Separately geopolitical concerns are back under the spotlight as President Putin gave a keynote speech, which showed no hint of the Ukraine war coming to an end soon. Instead, Putin threatened the west with a nuclear response, hurting risk appetite.
In addition to Fed fears, earnings are less than impressive as the focus turns to retailers, which points to a struggling consumer.
Corporate news
Home Depot falls 4% pre-market after warning over profits as soaring inflation hits demand. The US home improvements chain posted a surprise fall in Q4 sales which comes after the boom years across the pandemic.
Walmart falls pre-market after earnings topped forecasts in the holiday quarter as it drew in shoppers but forecast annual earnings below estimates. EPS was $1.71 against $1.51 forecast, and revenue of $164.05 billion against $159.72. However, they are cautious on the year ahead as consumers remain under pressure.
Where next for the Nasdaq?
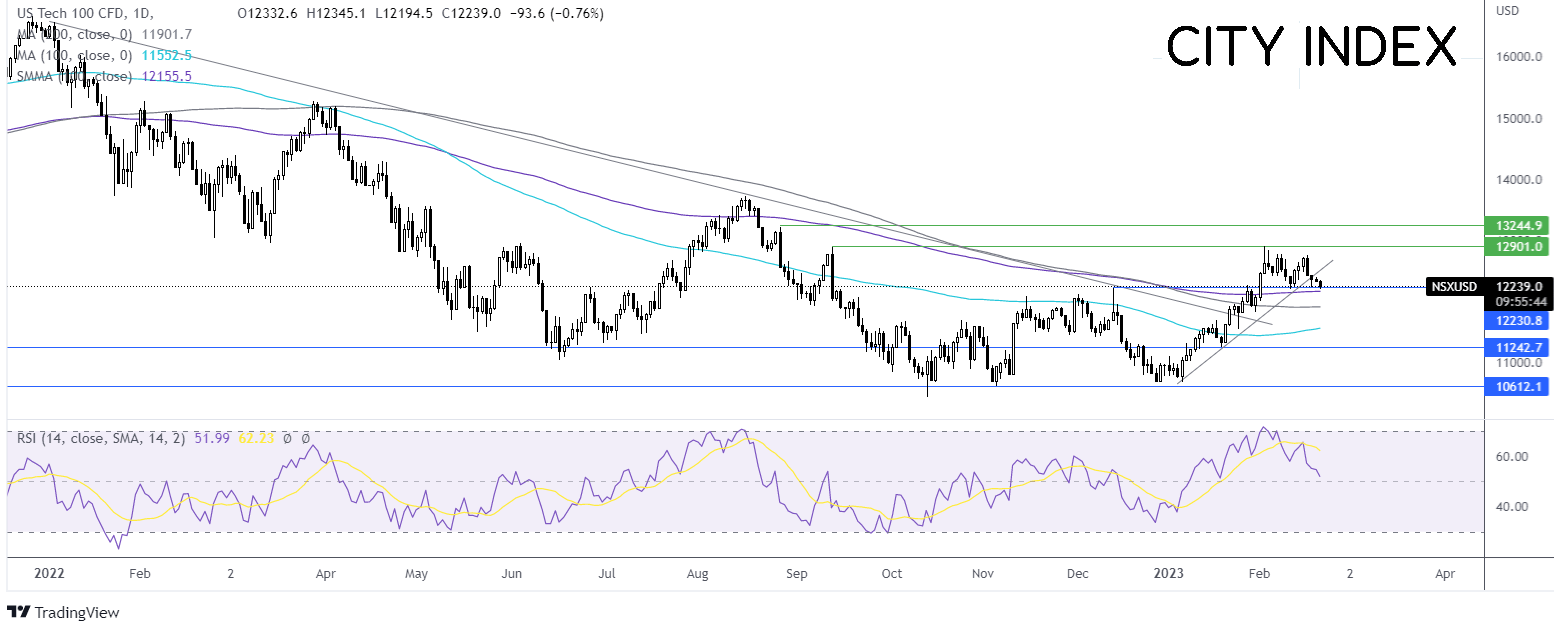
After forming a double top at 12750 the Nasdaq has fallen, breaking below the rising trendline dating back to the start of the year. Bears are looking to test support around the 12200 level, which has offered support and resistance over the past few months. A break below here, and the 100 sma exposes the 200 sma at 11900 with a break below here negating the near-term uptrend and bringing the 50 sma at 115265 into focus. Buyers need a break above 12750 and 12900 the February high to extend the bullish trend.
FX markets – USD & GBP rises
The USD is rising, tracking treasury yields higher as investors’ price in US interest rates rising higher and for longer to tackle inflation.
EUR/USD is falling owing to the stronger U.S. dollar and despite an impressive recovery in Eurozone PMIs. The flash composite rose to 52.3 in February, its highest level in nine months and well above the 50.6 level forecasts. The flash composite readings were positive in both France and Germany. German ZEW economic sentiment was also higher than forecast at 28.1, up from 16.9 as recession worries ease.
GBP/USD rebounding after stronger-than-expected UK PMI data. The composite PMI surged to 53 in February, up from 48.5 in January, calming fears of a recession in the UK. The dominant service sector drove the rebound in activity. The price sub-index, a good guide for inflation, cooled further, with costs rising at the slowest pace since April last year. The goldilocks report comes as the BoE weighs up another possible rate hike in March.
EUR/USD -0.30% at 1.0649
GBP/USD +0.51% at 1.21
Oil holds steady after yesterday’s gains
Oil prices holding steady, paring earlier losses and reversing gains from the previous session as investors weigh up stronger-than-expected PMI data against expectations of higher interest rates for longer, dampening global growth and hurting the demand outlook.
The focus of the financial markets in the Fed and the risk of the US central bank keeping rates elevated. This is also being offset by optimism surrounding China reopening and dim and ramping up.
Meanwhile, on the supply side, data shows that file flies to China hit the highest level since the start of the Ukraine war, surpassing a record set in April 2020.
WTI crude trades +0.25% at $77.50
Brent trades at +0.15% at $83.82
Learn more about trading oil here.
Looking ahead
14:45 US Composite PMI
15:00 US Existing home sales
19:00 ECB President Lagarde to speak
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Analysis The Index Rebounds After Tariff Suspension
Although the Nasdaq 100 started the session with a clear bearish bias, it showed a solid recovery toward the close, posting gains of more than 1.8% and moving back toward the 25,500-point area.
Dow Jones Forecast: DJIA falls after weak data & Trump's trade tariff update
U.S. stocks are falling after weaker-than-expected data raises concerns over the health of the US economy, and as Trump rattles the markets with more trade tariff uncertainty. Data showed that US jobless claims were higher than expected, rising to 248K up from 247K and defying expectations of a decline to 240K. Meanwhile, US producer price inflation also remained muted in May, another sign that tariffs have yet to increase prices.
Tariff Tantrum: SPX, Gold, USD, EUR/USD, USD/JPY
It’s been an eventful past week and we’re still not out of the woods. This webinar looked at a wide range of markets across stocks, gold and FX pairs.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.