



US open: Stocks fall ahead of ISM manufacturing data
Stocks fall at the start of the new quarter as recession fears remain. Manufacturing data is due.
Share this:

US futures
Dow futures -0.4% at 30695
S&P futures -0.5% at 3775
Nasdaq futures -0.6% at 11511
In Europe
FTSE -0.25% at 7167
Dax -2% at 13034
Euro Stoxx -2.22% at 3518
A weak start to the new quarter
US stocks are pointing to a weaker start on the first day of trading in the new quarter and adding to losses from earlier in the week.
Hot inflation has fueled aggressive rate hike and recession fears hurting demand for stocks across the quarter and across the first half.
The SP&P500 fell 20% across the first half of the year in its worst start to a year since 1970 whilst the Nasdaq plunged 30% in its worst H1 performance since 2002.
The Federal Reserve is widely expected to hike interest rates by 75 basis points in its July meeting to tame inflation.
What we are starting to see is that the 10-year treasury yield is edging lower, as recession fears rise. This could help stem the selloff in equities going forwards.
Looking ahead, attention is turning to ISM manufacturing PMI, which is expected to fall to 55 in June down from 56 in May. The tick lower represents the slowing growth and deteriorating industry expectations. However, the PMI is set to remain well above 50, which separates expansion from contraction.
In corporate news:
Micron Technologies is falling after disappointing with quarterly guidance. The chip maker expects slower sales as the boom for chips could be coming to an end.
Where next for the Nasdaq?
The Nasdaq failed to retake the multi-month falling trendline resistance and rebounded lower. The fall below the 20 sma and support at 11700 keeps the bears hopeful of further downside, as does the RSI below 50. Sellers are testing support at 11490, the May low, with a break below here opening the door to 11035 the 2022 low. Buyers will look for a move over 12225, the weekly high, to create a higher high and expose the 50 sma at 12315. A move above here opens the door to 12630, the mid-June high.

FX markets – USD rises, EUR falls.
USD is rising after losses in the previous session. The USD is set to gain across the week as aggressive Fed bets have ramped up sand on safe-haven flows as fears of slower global growth pick up.
EURUSD is falling towards 1.04, despite rising inflation. Eurozone inflation rose to 8.6% YoY, a record high, although core inflation fell. Energy and food price spikes were the main contributors. Given that energy prices could continue rising and that PPPI remains elevated, EZ inflation is unlikely to fall anytime soon. The data piles pressure on the ECB to raise interest rates at a faster pace in order to tame price rises. The ECB’s July interest rate announcement could see the central bank opt for a 50-basis point rate hike. However, they would be doing so as economic growth slows considerably and risk tipping the eurozone into recession.
GBP/USD is falling again, after weaker than expected UK manufacturing PMI data. Manufacturing activity fell to 52.8 in June, down from 54.6 in May. Rising inflation dampened new orders which doesn’t bode well for the outlook.
GBP/USD -1.2% at 1.2030
EUR/USD -0.57% at 1.0574
Oil rises on tight supply
Oil prices heading high, recapturing losses from the previous session, owing to outages in Libya and shutdowns in Norway, which overshadowed recession fears hurting the demand outlook.
Oil prices are not set to end the week higher, after two straight weeks of declines.
WTI crude trades +2.4% at $108.67
Brent trades +2.3% at $110.72
Looking ahead
15:00 ISM manufacturing PMI
US futures
Dow futures -0.4% at 30695
S&P futures -0.5% at 3775
Nasdaq futures -0.6% at 11511
In Europe
FTSE -0.25% at 7167
Dax -2% at 13034
Euro Stoxx -2.22% at 3518
Learn more about trading indices
A weak start to the new quarter
US stocks are pointing to a weaker start on the first day of trading in the new quarter and adding to losses from earlier in the week.
Hot inflation has fueled aggressive rate hike and recession fears hurting demand for stocks across the quarter and across the first half.
The SP&P500 fell 20% across the first half of the year in its worst start to a year since 1970 whilst the Nasdaq plunged 30% in its worst H1 performance since 2002.
The Federal Reserve is widely expected to hike interest rates by 75 basis points in its July meeting to tame inflation.
What we are starting to see is that the 10-year treasury yield is edging lower, as recession fears rise. This could help stem the selloff in equities going forwards.
Looking ahead, attention is turning to ISM manufacturing PMI, which is expected to fall to 55 in June down from 56 in May. The tick lower represents the slowing growth and deteriorating industry expectations. However, the PMI is set to remain well above 50, which separates expansion from contraction.
In corporate news:
Micron Technologies is falling after disappointing with quarterly guidance. The chip maker expects slower sales as the boom for chips could be coming to an end.
Where next for the Nasdaq?
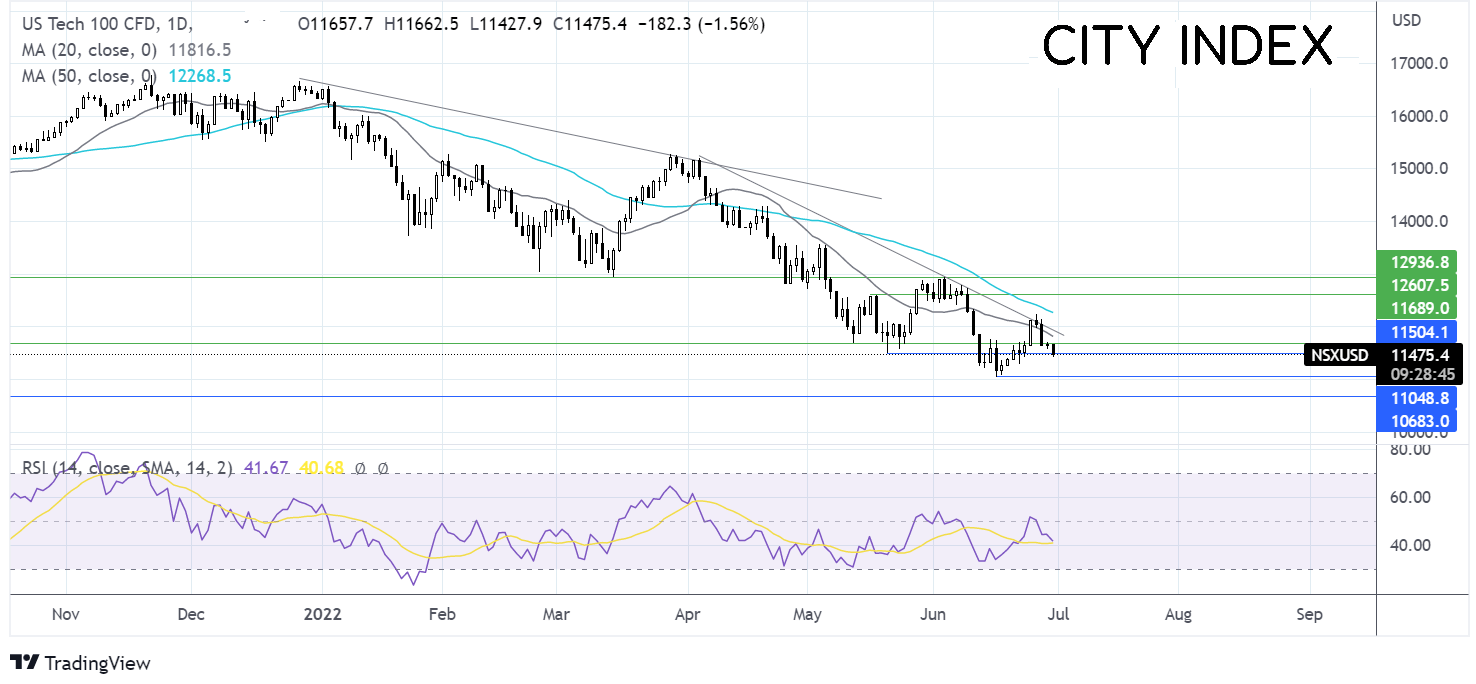
The Nasdaq failed to retake the multi-month falling trendline resistance and rebounded lower. The fall below the 20 sma and support at 11700 keeps the bears hopeful of further downside, as does the RSI below 50. Sellers are testing support at 11490, the May low, with a break below here opening the door to 11035 the 2022 low. Buyers will look for a move over 12225, the weekly high, to create a higher high and expose the 50 sma at 12315. A move above here opens the door to 12630, the mid-June high.
FX markets – USD rises, EUR falls.
USD is rising after losses in the previous session. The USD is set to gain across the week as aggressive Fed bets have ramped up sand on safe-haven flows as fears of slower global growth pick up.
EURUSD is falling towards 1.04, despite rising inflation. Eurozone inflation rose to 8.6% YoY, a record high, although core inflation fell. Energy and food price spikes were the main contributors. Given that energy prices could continue rising and that PPPI remains elevated, EZ inflation is unlikely to fall anytime soon. The data piles pressure on the ECB to raise interest rates at a faster pace in order to tame price rises. The ECB’s July interest rate announcement could see the central bank opt for a 50-basis point rate hike. However, they would be doing so as economic growth slows considerably and risk tipping the eurozone into recession.
GBP/USD is falling again, after weaker than expected UK manufacturing PMI data. Manufacturing activity fell to 52.8 in June, down from 54.6 in May. Rising inflation dampened new orders which doesn’t bode well for the outlook.
GBP/USD -1.2% at 1.2030
EUR/USD -0.57% at 1.0574
Oil rises on tight supply
Oil prices heading high, recapturing losses from the previous session, owing to outages in Libya and shutdowns in Norway, which overshadowed recession fears hurting the demand outlook.
Oil prices are not set to end the week higher, after two straight weeks of declines.
WTI crude trades +2.4% at $108.67
Brent trades +2.3% at $110.72
Learn more about trading oil here.
Looking ahead
15:00 ISM manufacturing PMI
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.

Gold forecast: Rising yields become too hot for gold, but the outlook is far from bearish
Gold and silver prices took a plunge today, with the former down 3% and the latter falling some 5% by mid European session, before bouncing off their lows. The losses come after the metals remained largely supported until last week, despite the big dollar rally and surging bond yields as we have seen in recent weeks. But it simply got too much, and the metals succumbed to pressure today.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.