



US open: Stocks fall as the bond sell-off eases
Stocks are heading lower after strong gains yesterday when the bond market saw a record sell-off on expectations of a more hawkish Fed. Oil prices rise.
Share this:

US futures
Dow futures -0.44% at 34700
S&P futures -0.5% at 4494
Nasdaq futures -0.8% at 14553
In Europe
FTSE -0.3% at 7480
Dax -1.4% at 14350
Euro Stoxx -1.56% at 3886
Learn more about trading indices
Stocks pare yesterday’s gains
US stocks are pointing to a softer open as investors continue digesting the more hawkish stance adopted by the Fed and ahead of President Biden’s trip to Europe to discuss more sanctions on Russia.
Fed speakers across the spectrum, from the typically more dovish leaning officials to the hawks, support a more aggressive path to hiking interest rates. The bond market bore the brunt of the more hawkish Fed outlook yesterday, with a record selloff in treasuries. Instead, investors are putting their money into stocks, resulting in the three leading indices on Wall Street posting substantial gains.
Today the sell-off in the bond market is stabilizing, and yields are rising; stocks are falling. Fed speakers will remain in focus amid a relatively light economic calendar.
President Biden is also due to meet with his European peers to discuss further measures to pressurize Moscow as the Ukraine war continues.
Oil prices are climbing again, which is adding to concerns over already high inflation, hurting market sentiment.
In corporate news:
Tencent ADR’s trade lower after reporting 8% revenue growth, the slowest growth since its listing as it grapples with a regulatory crackdown.
Where next for the S&P500?
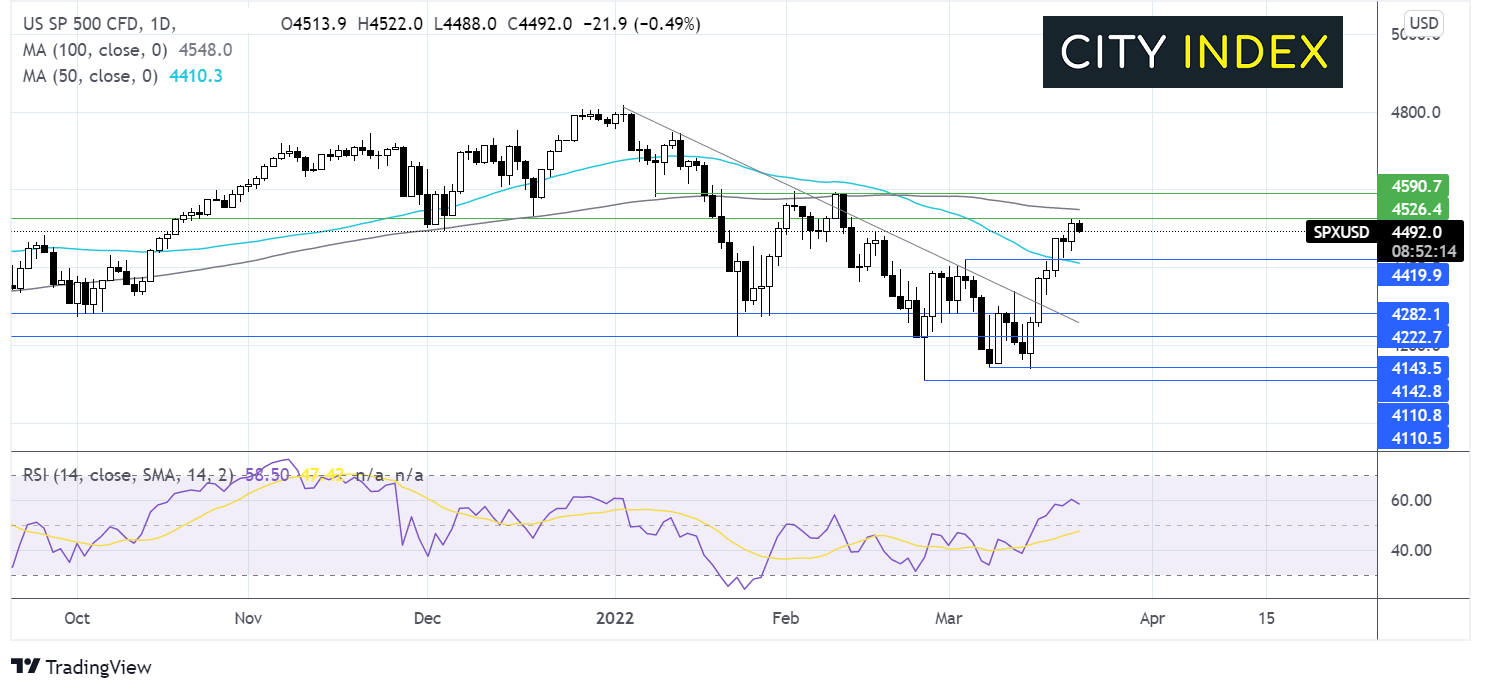
The S&P 500 has been extending its rebound from 4150 the March 15 low, breaking above the 50 SMA but ran into resistance at 4530, the December 20 low. The RSI remains in bullish territory, suggesting that there could be more upside to be had. Buyers would need to break above 4530 to expose the 100 sma at 4550 before looking to 4590, the February high. Meanwhile, support can be seen at 4420, March 3 high, and 50 sma, a move below here could negate the near-term uptrend, opening the door towards 4280, the October & late January low.
FX markets USD rises, GBP drops.
USD is heading higher for a fourth straight session on rising expectations of a more hawkish Fed. Fed speakers this week have been clear that they are on a mission to tame rising inflation. The market is now pricing in a 70% probability of a 50 basis point interest rate rise in the next FOMC meeting in May.
GBPUSD is falling after data showed that UK CPI jumped to 6.2% YoY in February, well above the 5.5% recorded in January and above the 6% forecast. The 30-year high inflation will add pressure to the BoE to hike rates again for a fourth time in May. The pound is falling on fears that higher rates could hit the UK, the growth outlook hard.
GBP/USD -0.4% at 1.3171
EUR/USD -0.16% at 1.0999
Oil rises on supply concerns, falling inventories.
Oil prices are rising on Wednesday as concerns about oversupply continue to haunt the market. Not only is the market concerned about the ongoing supply hit from the Russian war, but now Kazakhstan’s crude exports via the CPC pipeline are also under the spotlight.
Oil supply through the CPC pipeline on Russia’s Black sea coast has stopped completely after damage caused by a storm. Repairs are expected to take around six weeks. The pipeline carries about 1 million barrels per day, equating to around 1% of the global oil supply.
Less supply in an already tight market is a recipe for higher oil prices. Add into the mix the latest API crude oil stockpile data, which shows that inventories fell by 4.3 million barrels well below the estimated 100k barrel rise, and it’s easy to see why oil trades over $115 per barrel.
EIA crude oil inventory data is due later today.
WTI crude trades +2.5% at $112.06
Brent trades +2.58% at $115.87
Learn more about trading oil here.
Looking ahead
N/A
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
US futures
Dow futures -0.44% at 34700
S&P futures -0.5% at 4494
Nasdaq futures -0.8% at 14553
In Europe
FTSE -0.3% at 7480
Dax -1.4% at 14350
Euro Stoxx -1.56% at 3886
Stocks pare yesterday’s gains
US stocks are pointing to a softer open as investors continue digesting the more hawkish stance adopted by the Fed and ahead of President Biden’s trip to Europe to discuss more sanctions on Russia.
Fed speakers across the spectrum, from the typically more dovish leaning officials to the hawks, support a more aggressive path to hiking interest rates. The bond market bore the brunt of the more hawkish Fed outlook yesterday, with a record selloff in treasuries. Instead, investors are putting their money into stocks, resulting in the three leading indices on Wall Street posting substantial gains.
Today the sell-off in the bond market is stabilizing, and yields are rising; stocks are falling. Fed speakers will remain in focus amid a relatively light economic calendar.
President Biden is also due to meet with his European peers to discuss further measures to pressurize Moscow as the Ukraine war continues.
Oil prices are climbing again, which is adding to concerns over already high inflation, hurting market sentiment.
In corporate news:
Tencent ADR’s trade lower after reporting 8% revenue growth, the slowest growth since its listing as it grapples with a regulatory crackdown.
Where next for the S&P500?
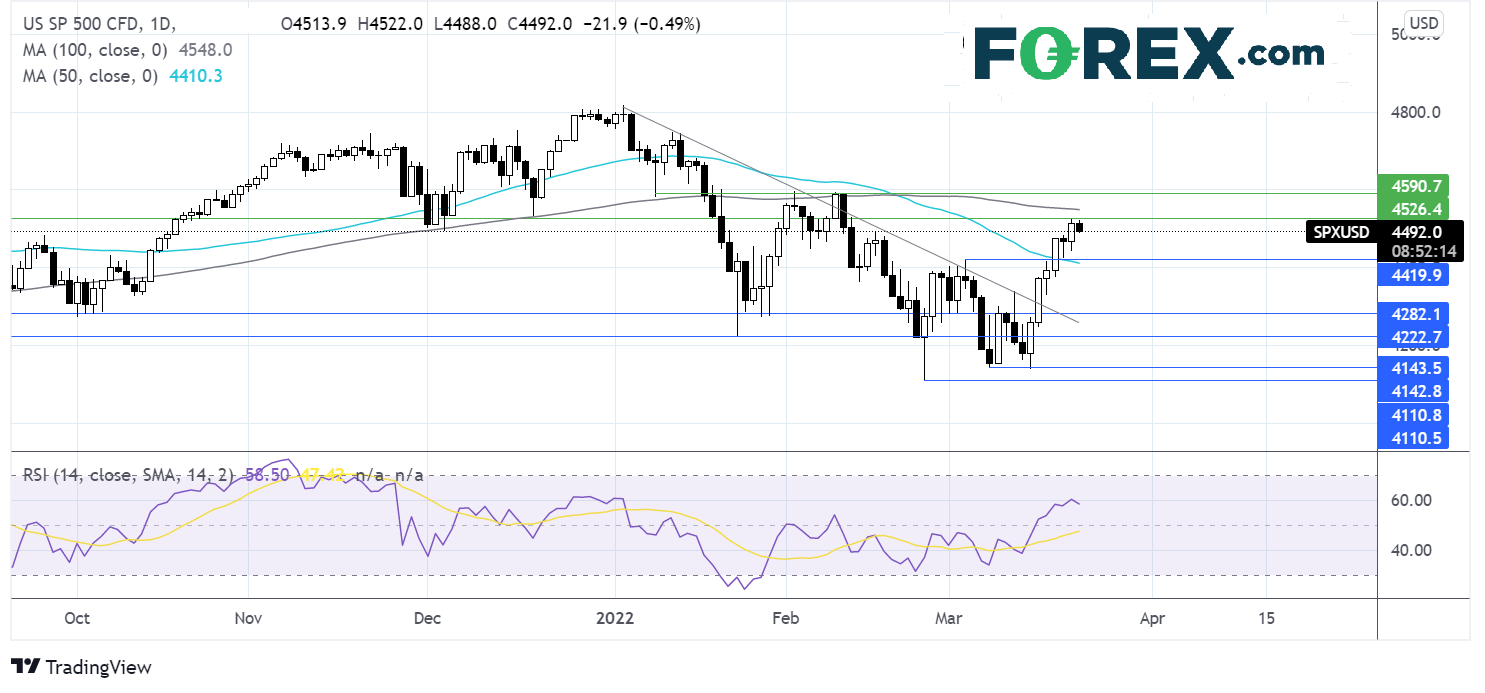
The S&P 500 has been extending its rebound from 4150 the March 15 low, breaking above the 50 SMA but ran into resistance at 4530, the December 20 low. The RSI remains in bullish territory, suggesting that there could be more upside to be had. Buyers would need to break above 4530 to expose the 100 sma at 4550 before looking to 4590, the February high. Meanwhile, support can be seen at 4420, March 3 high, and 50 sma, a move below here could negate the near-term uptrend, opening the door towards 4280, the October & late January low.
FX markets USD rises, GBP drops.
USD is heading higher for a fourth straight session on rising expectations of a more hawkish Fed. Fed speakers this week have been clear that they are on a mission to tame rising inflation. The market is now pricing in a 70% probability of a 50 basis point interest rate rise in the next FOMC meeting in May.
GBPUSD is falling after data showed that UK CPI jumped to 6.2% YoY in February, well above the 5.5% recorded in January and above the 6% forecast. The 30-year high inflation will add pressure to the BoE to hike rates again for a fourth time in May. The pound is falling on fears that higher rates could hit the UK, the growth outlook hard.
GBP/USD -0.4% at 1.3171
EUR/USD -0.16% at 1.0999
Oil rises on supply concerns, falling inventories.
Oil prices are rising on Wednesday as concerns about oversupply continue to haunt the market. Not only is the market concerned about the ongoing supply hit from the Russian war, but now Kazakhstan’s crude exports via the CPC pipeline are also under the spotlight.
Oil supply through the CPC pipeline on Russia’s Black sea coast has stopped completely after damage caused by a storm. Repairs are expected to take around six weeks. The pipeline carries about 1 million barrels per day, equating to around 1% of the global oil supply.
Less supply in an already tight market is a recipe for higher oil prices. Add into the mix the latest API crude oil stockpile data, which shows that inventories fell by 4.3 million barrels well below the estimated 100k barrel rise, and it’s easy to see why oil trades over $115 per barrel.
EIA crude oil inventory data is due later today.
WTI crude trades +2.5% at $112.06
Brent trades +2.58% at $115.87
Looking ahead
N/A
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.