



US open: Stocks rise and look to first weekly gain in a month
US stocks rise and are set for a weekly rise after several weeks of losses. With little reaction from Powell's speech and falling treasury yields could peak inflation now be priced in.
Share this:

US futures
Dow futures +0.7% at 31978
S&P futures +0.8% at 4035
Nasdaq futures +0.9% at 12447
In Europe
FTSE 1.5% at 7328
Dax 1.45% at 13093
Euro Stoxx 1.3% at 3670
Fed speaks up next
US stocks are heading higher and are set to end the week higher for the first time in a month as the market mood improves. Investors are shrugging off Powell’s comments from yesterday that the Fed will continue fighting inflation until the job is done.
With oil prices set to fall again across the week and treasury yields also declining, we could be getting to the stage when peak inflation has been priced in.
CPI inflation data next week could help the markets determine whether cooling inflation is a new trend.
With no big data release expected, Fed official Waller is due to speak later and could provide further direction for what to expect from the September FOMC.
Corporate news:
DocuSign jumps 16% pre-market after posting better than expected Q2 results. The software firm also raised its revenue guidance for the year.
Where next for the S&P500?
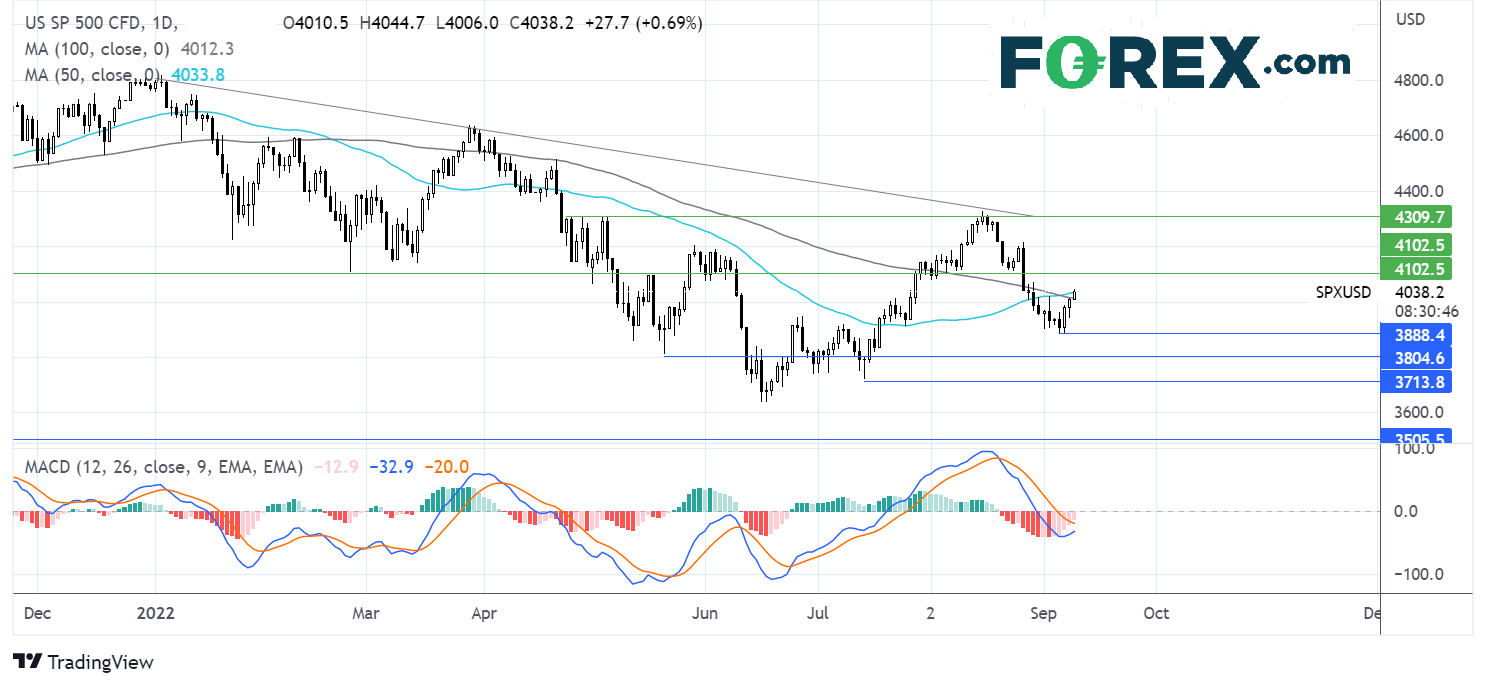
The S&P500 is extending the rebound from 3880, rising above the 100 sma and testing resistance of the 50 sma. The receding bearish bias on the MACD keeps buyers hopeful of further upside. Buyers need to break above the 50 sma at 4035 to extend the recovery to 4000 round number and 4100 the February low. A rise above here negates the near-term downtrend. Sellers could look at the 50 sma crossing below the 100 sma as a sell signal, with a move below 3880 creating a lower low and brings 3720 the July 14 low into focus.
FX markets – USD falls, EUR rises
The USD is falling, extending losses from the previous session as investors reassess the hawkishness of other central banks such as the ECB alongside the Fed. Optimism that inflation could cool further as next week’s CPI comes into view adds to the drag on USD. USD/JPY falls 1% as the BoJ says that it is watching the exchange rate closely.
EUR/USD is rising as ECB policymakers continue to hammer home the hawkish stance after hiking interest rates by 75 basis points yesterday. Today. In a speech, Lagarde reaffirmed that taming inflation was the central bank’s top priority. She added that the ECB is prepared to provide liquidity to banks but not energy firms
GBP/USD is rising, capitalizing on the weaker USD as investors continue to digest Liz Truss’ ene5rgy relief package. Credit Suisse has upwardly revised the UK economic forecasts for 2023 on the back of the announcement and now expects GDP -0.2%, up from 2023. The BoE will postpone the MPC to September 22nd due to the period of national mourning.
GBP/USD +0.57% at 1.1570
EUR/USD +0.5% at 1.0042
Oil falls to 8-month lows.
Oil prices are rising today but are set for a second straight week of losses. Demand worries as central banks across the globe rate interest rates, slowing growth and hitting the demand outlook. The ongoing, strict zero-COVID policy in China is dragging on the demand outlook further.
Oil has lost around 18% since the start of August as demand worries dominated. However, supply concerns remain. As talks surrounding a price cap on Russian oil and gas gather momentum the risk of Russia withdrawing supply completely rises.
WTI crude trades +1.6% at $84.5
Brent trades +2.7% at $90.20
Looking ahead
17:00 Fed Waller speech
18:00 US Baker Hughes Rig count
US futures
Dow futures +0.7% at 31078
S&P futures +0.8% at 3900
Nasdaq futures +0.67% at 12167
In Europe
FTSE +1% at 73283
Dax +1.3% at 12960
Euro Stoxx +1.3% at 3670
Learn more about trading indices
Fed speaks up next
US stocks are heading higher and are set to end the week higher for the first time in a month as the market mood improves. Investors are shrugging off Powell’s comments from yesterday that the Fed will continue fighting inflation until the job is done.
With oil prices set to fall again across the week and treasury yields also declining, we could be getting to the stage when peak inflation has been priced in.
CPI inflation data next week could help the markets determine whether cooling inflation is a new trend.
With no big data release expected, Fed official Waller is due to speak later and could provide further direction for what to expect from the September FOMC.
Corporate news:
DocuSign jumps 16% pre-market after posting better than expected Q2 results. The software firm also raised its revenue guidance for the year.
Where next for the S&P500?
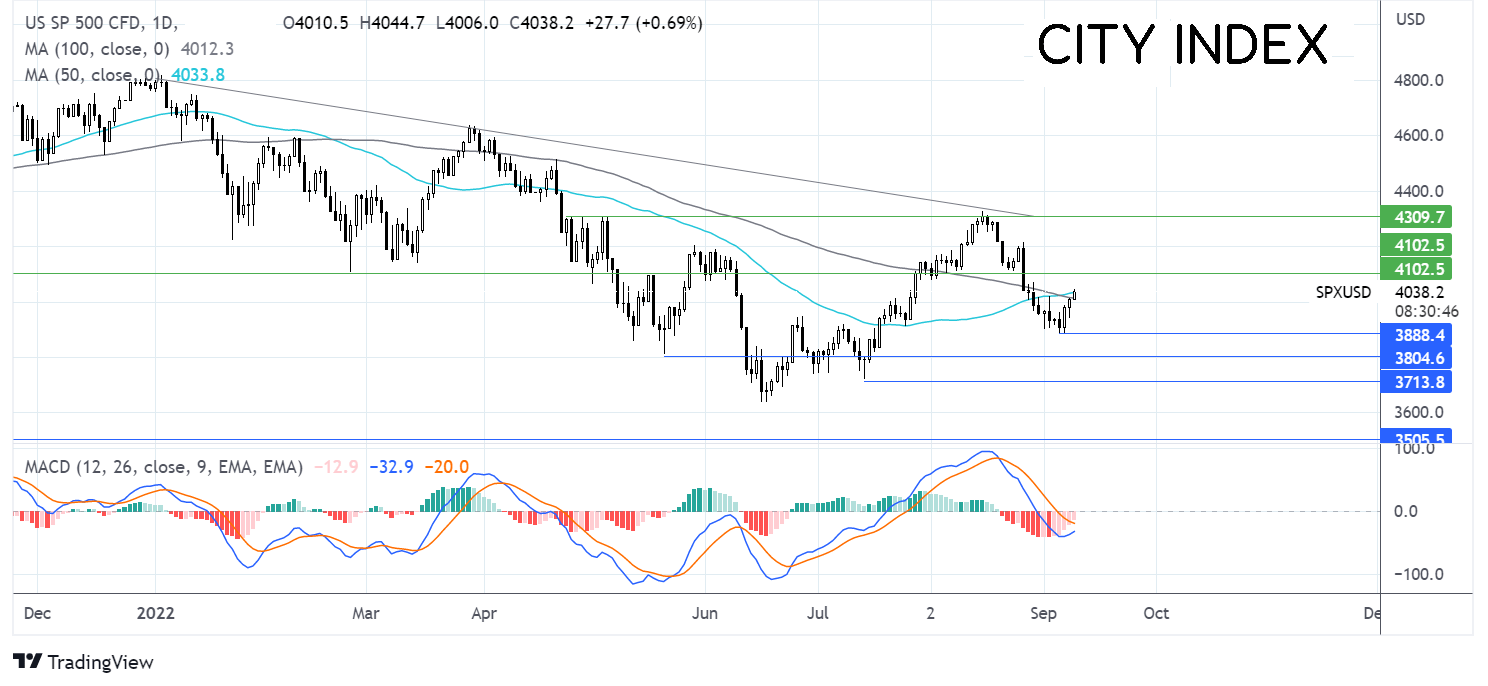
The S&P500 is extending the rebound from 3880, rising above the 100 sma and testing resistance of the 50 sma. The receding bearish bias on the MACD keeps buyers hopeful of further upside. Buyers need to break above the 50 sma at 4035 to extend the recovery to 4000 round number and 4100 the February low. A rise above here negates the near-term downtrend. Sellers could look at the 50 sma crossing below the 100 sma as a sell signal, with a move below 3880 creating a lower low and brings 3720 the July 14 low into focus.
FX markets – USD falls, EUR rises
The USD is falling, extending losses from the previous session as investors reassess the hawkishness of other central banks such as the ECB alongside the Fed. Optimism that inflation could cool further as next week’s CPI comes into view adds to the drag on USD. USD/JPY falls 1% as the BoJ says that it is watching the exchange rate closely.
EUR/USD is rising as ECB policymakers continue to hammer home the hawkish stance after hiking interest rates by 75 basis points yesterday. Today. In a speech, Lagarde reaffirmed that taming inflation was the central bank’s top priority. She added that the ECB is prepared to provide liquidity to banks but not energy firms
GBP/USD is rising, capitalizing on the weaker USD as investors continue to digest Liz Truss’ ene5rgy relief package. Credit Suisse has upwardly revised the UK economic forecasts for 2023 on the back of the announcement and now expects GDP -0.2%, up from 2023. The BoE will postpone the MPC to September 22nd due to the period of national mourning.
GBP/USD +0.57% at 1.1570
EUR/USD +0.5% at 1.0042
Oil falls to 8-month lows.
Oil prices are rising today but are set for a second straight week of losses. Demand worries as central banks across the globe rate interest rates, slowing growth and hitting the demand outlook. The ongoing, strict zero-COVID policy in China is dragging on the demand outlook further.
Oil has lost around 18% since the start of August as demand worries dominated. However, supply concerns remain. As talks surrounding a price cap on Russian oil and gas gather momentum the risk of Russia withdrawing supply completely rises.
WTI crude trades +1.6% at $84.5
Brent trades +2.7% at $90.20
Learn more about trading oil here.
Looking ahead
17:00 Fed Waller speech
18:00 US Baker Hughes Rig count
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.