



Week Ahead: Nvidia Earnings, Delayed US Data, and Fed Repricing Keep Markets Cautious
A data-heavy week lies ahead as investors await Nvidia’s earnings and delayed US releases following the government shutdown. Fed cut odds have slipped below 50%, pressuring tech and lifting the dollar, while gold holds near $4,060/oz. The DAX remains weak below 24,000 amid a bearish setup, and UK gilts sold off on fiscal concerns. Semiconductor momentum stays strong, led by Korea’s DRAM surge, while China’s macro slowdown and Japan’s GDP contraction weigh on Asia. Overall tone: cautious into midweek earnings and US jobs data.
Share this:
Week-Ahead: Key Items
- Top events:
- Nvidia earnings: Wed, after US close. Crucial AI read-through after outsized rally.
- Delayed US data: Sep NFP Thu (Nov 20); Sep real earnings Fri (Nov 21).
- Other US releases: Aug construction spending Mon (Nov 17); Aug manufacturers’ orders Tue (Nov 18); Aug international trade (Census + BEA) Wed (Nov 19).
- Market setup:
- Asia softer into data/earnings.
- December Fed cut odds <50% after hawkish Fedspeak; tech under pressure.
- China–Japan friction hit Tokyo travel/retail; stimulus chatter pressured JGBs.
- Dollar firmer; gold ~$4,060/oz; oil softer; bitcoin weak after worst week since March.
Europe/UK
- UK Gilts under strain: Fiscal credibility doubts after reports Reeves may drop income-tax hike and extend allowance freeze.
- 10Y Gilt +13 bp to 4.57%.
- GBP fell to a 2.5-year low vs EUR.
- Risk: further pressure if Autumn Statement (Nov 26) relies on optimistic growth.
Germany 40 - DAX Technical Outlook 4 H
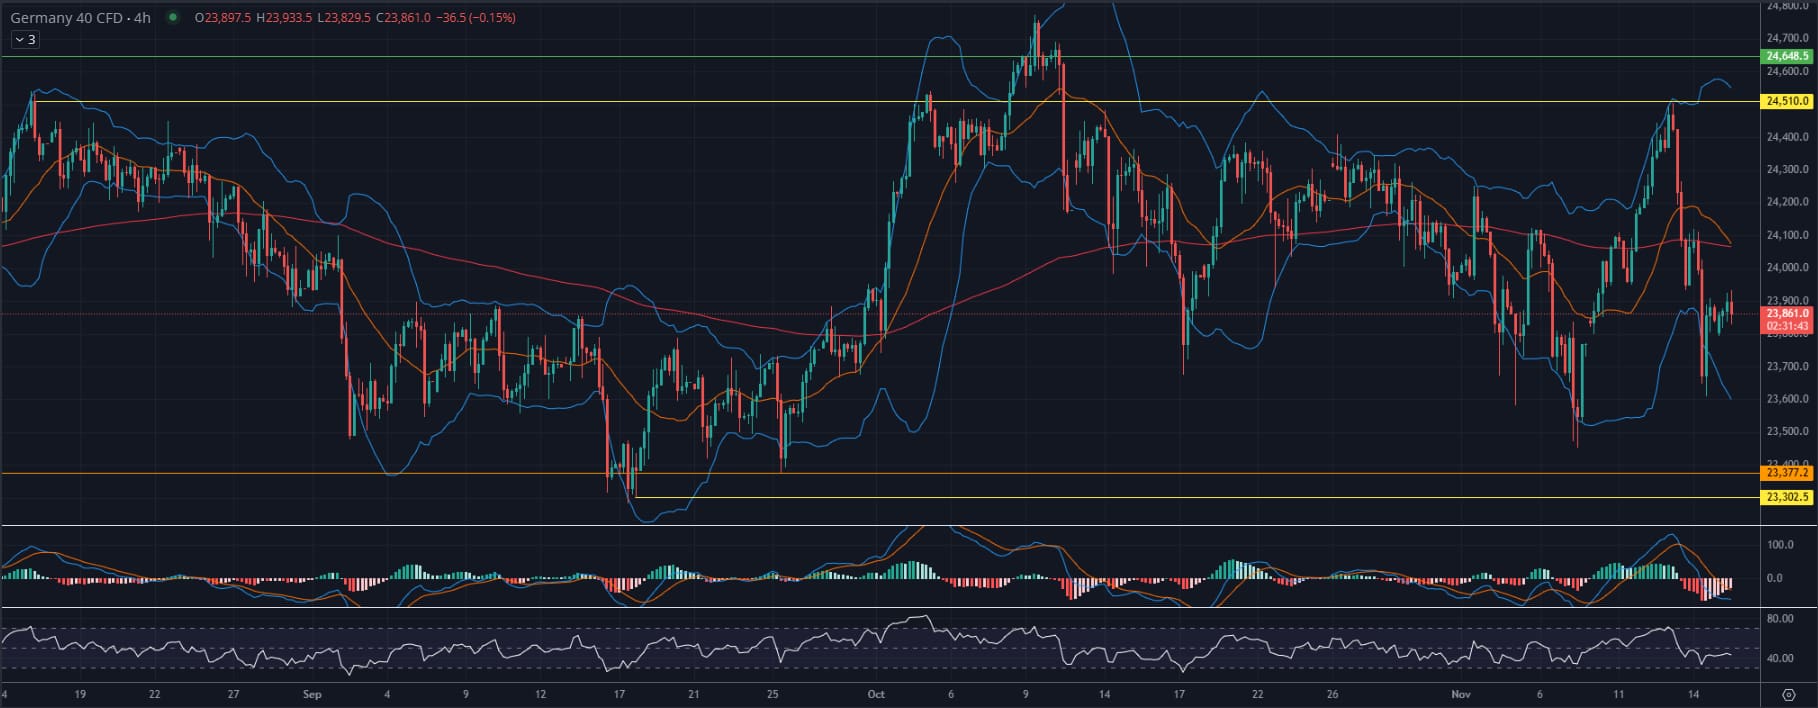
The Germany 40 CFD (4H) remains under pressure after repeated rejections at 24,510 resistance. Price action has turned choppy around 23,850, with both the 50 EMA and 200 EMA converging overhead near 24,000–24,100, forming a resistance cluster. The RSI (around 40) shows weak momentum, while the MACD is still below the signal line, suggesting bearish bias persists despite slight short-term stabilization.
Key support lies at 23,800, followed by 23,377–23,300. A drop below 23,800 would likely accelerate selling toward the lower support band, while a recovery above 24,100 could neutralize pressure and reopen a path to 24,
Semis/AI Supply Chain
- DRAM surge: Q4’25 contract prices seen ~+20% QoQ; more than tripled since April.
- Server demand locking contracts to 2027; potential allocation squeeze for PCs/phones.
- Profit mix: HBM ~60% margin vs DRAM ~40% now; gap likely narrows in 2026.
- Korea dominance: ~70% DRAM / ~80% HBM share; KOSPI strength; 2026 EPS upgrades >9% MoM, now ~+30% y/y.
China Macro
- Oct slowdown: IP 4.9% y/y, services 2.9% y/y; investment weaker on housing slump.
- Largest monthly home-price drop YTD.
- One-offs: high base (post-Sep’24 stimulus), US–China trade flare-up hit exports temporarily.
- New ~€120bn fiscal support expected to aid a sequential pickup next months.
Earnings Focus (This Week)
- US: Medtronic, Palo Alto Networks, NVIDIA (Wed), Walmart, Intuit.
- Europe: Imperial Brands, ORLEN, Halma, Sage, Severn Trent, Allegro.eu, Diploma, CTS Eventim, Babcock, Investec.
- Asia: Tokio Marine, Sompo, MS&AD; Trip.com, Xiaomi, Baidu, Lenovo, NetEase.
Macro Diary (local dates as stated)
- Mon (Nov 17): US Aug construction spending. Japan Q3 GDP advance (consensus QoQ −0.6%).
- Wed: UK Oct CPI (headline seen 3.6%, core 3.4%).
- Thu (Nov 20): US Sep NFP (first post-shutdown federal release; likely soft); US S&P Global Nov flash PMIs Fri.
- Fri: US Sep real earnings.
Crypto/Payments
- JPM Coin (USD deposit token) live; Mastercard testing.
- US SOL ETFs: 10 straight inflow days; ~$342m since Oct 28.
- Corporate BTC buy: +487 BTC (~$50m) at ~$102.6k; total holdings 641,692 BTC (~3% of supply).
- Czech central bank pilot: ~$1m in BTC/crypto for transaction/testing use cases.
- Market: Bitcoin briefly erased 2025 gains, near $93k over weekend.
US Trade/Tariffs
- China rare-earths framework: Bessent “hopefully” by Thanksgiving; leverage if non-compliance.
- No further tariff rollbacks expected per Trump; soybean talks ongoing.
- Tariff “dividend” checks would need Congress.
- US–Switzerland/Liechtenstein: reciprocal tariff cap ≤15%, sectoral cuts/quotas; ≥$200bn Swiss/Liechtenstein investment into US (incl. $67bn in 2026).
- USTR: deals with other Western partners “very close.”
- Scope tweak to reciprocal ag tariffs effective 00:01 ET, Nov 13, 2025.
- Tesla telling suppliers to exclude China-made parts for US builds.
APAC Tape
- ASX 200: mixed; IT/Energy up, Defensives lag.
- Nikkei 225: choppy around 50k; modest loss post GDP contraction; China travel warning hit Japan travel names.
- KOSPI: +1.5% outperformance on chip strength (reports of Samsung price hikes).
- HK/Shanghai: modest declines, in line with region ex-Korea.
Notables
- Samsung: New Pyeongtaek fab; mass production 2028; FläktGroup exploring Korea plant.
- Alibaba Qwen: public beta as ChatGPT competitor.
- Japan: considering ~JPY 17tn stimulus; ~JPY 14tn supplementary budget.
Bottom line: Cautious tone into Nvidia Wednesday and Sep NFP Thursday. Re-pricing of Fed cuts, UK fiscal uncertainty, and semiconductor pricing dynamics are the near-term macro drivers.
--Philip Papageorgiou – Market Analyst
-X: PhilipForexCom


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100 Forecast: NDX rebounds as oil prices fall and ahead of Apple earnings
U.S. stock indices are moving higher on Monday as tech and AI-related stocks steady following a shocking October. The mood remains cautious following the AI wobble, with more tech earnings due this week, U.S. midterm elections and a full U.S. economic data calendar.

Gold forecast: XAU/USD stabilised after recent falls – for now
Gold has started the first week of the new month trying to recover some ground after another bruising week. Oil prices have taken a sharp drop and that has allowed risk assets to bounce back, which has clearly helped the precious metal too. However, with sentiment remaining bearish towards the metals, and with $4000 level having been taken out last week, the path of least resistance is to the downside for gold.

Have Markets Found a Turning Point Ahead of the Elections?
Fed rate-hike bets topping 70% have pressured markets, including precious metals and U.S. indices, toward key support levels. Could these levels signal a turning point ahead of the U.S. midterm elections?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.