US index futures pushed higher in the first half of Friday’s session, taking cues from a strong performance from European equities. Both European and US equity futures extending yesterday’s impressive recovery after the sharp sell-off earlier in the week. But the lingering concerns around the AI investment cycle remain, while bond markets were easing lower again, lifting yields. Heading into the last day of the week, we are cautious that the recovery could lose steam, leading to fresh falls. As such, the risks to our short-term Nasdaq 100 forecast remain tilted to the downside, as I am not convinced the markets have bottomed just yet. Today, there isn’t much in the way of scheduled data to provide fresh direction.
Let’s have a look at the chart of Nasdaq 100 first then discuss my concerns about the tech sector later.
Technical Nasdaq 100 forecast and key levels to watch
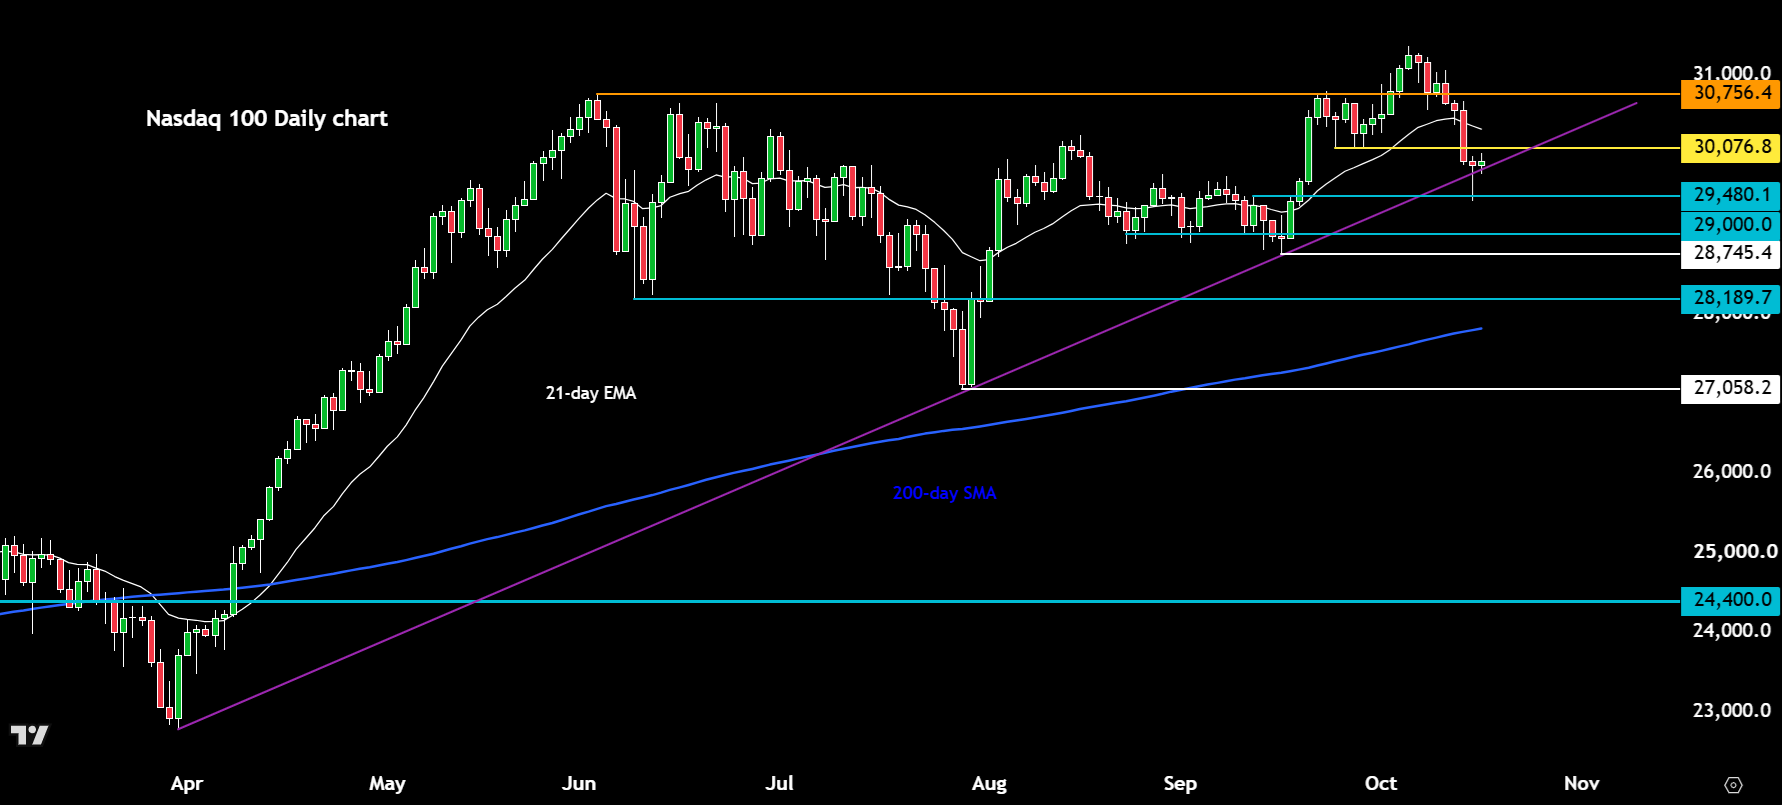
Following the kickback rally from the lows yesterday, the index ended back above the trendline going back to the end of March. However, it has created a couple of bearish-looking price candles leading into yesterday’s drop, so I don’t think the bulls are out of the woods just yet.
For that reason, I remain cautious that we could see some further selling in the Nasdaq 100, particularly as the index may have signalled a more meaningful topping signal when it failed to hold the breakout above the June high of around 30,755 earlier this month.
The recent breakdown below support at 30,075 is an additional bearish sign, with that level potentially now turning into resistance. Another resistance level to watch is around 30,500.
Support at 29,480 held yesterday, but another test of that level could lead to a breakdown towards 29,000. Below that, there’s not much in the way of obvious support until around 28,190, so there is potential for a larger correction.
AI concerns linger
CoreWeave was among the names caught up in the recent sell-off, although the stock recovered yesterday after Nvidia CEO Jensen Huang said the company’s financial position was improving and its cost of capital was falling. That is hardly an impartial endorsement, given Nvidia’s sizeable interest in CoreWeave, so the more important question is whether the recovery can be sustained once the immediate reassurance fades.
More broadly, this week’s price action suggests the market debate is beginning to shift. The question is no longer simply how large the AI opportunity can become, but how profitable the enormous investment required to realise it will ultimately be.
Demand for chips and computing capacity remains exceptionally strong. But that is only one side of the equation. Investors also need to see adequate returns on the vast sums being committed to data centres, power generation, networking and other infrastructure.
There are some signs that these concerns are spilling into credit markets, particularly around highly indebted technology companies. Businesses with large capital requirements are particularly vulnerable if financing costs remain elevated for longer.
That creates a difficult combination for the AI trade. Higher interest rates reduce the present value of future cash flows, while simultaneously increasing the cost of financing the infrastructure needed to support the next phase of AI growth.
Crude oil on the rise again as yields bounce back
Unless something fundamentally changes, which I don’t think has this week, I remain cautious on the Nasdaq 100 forecast.
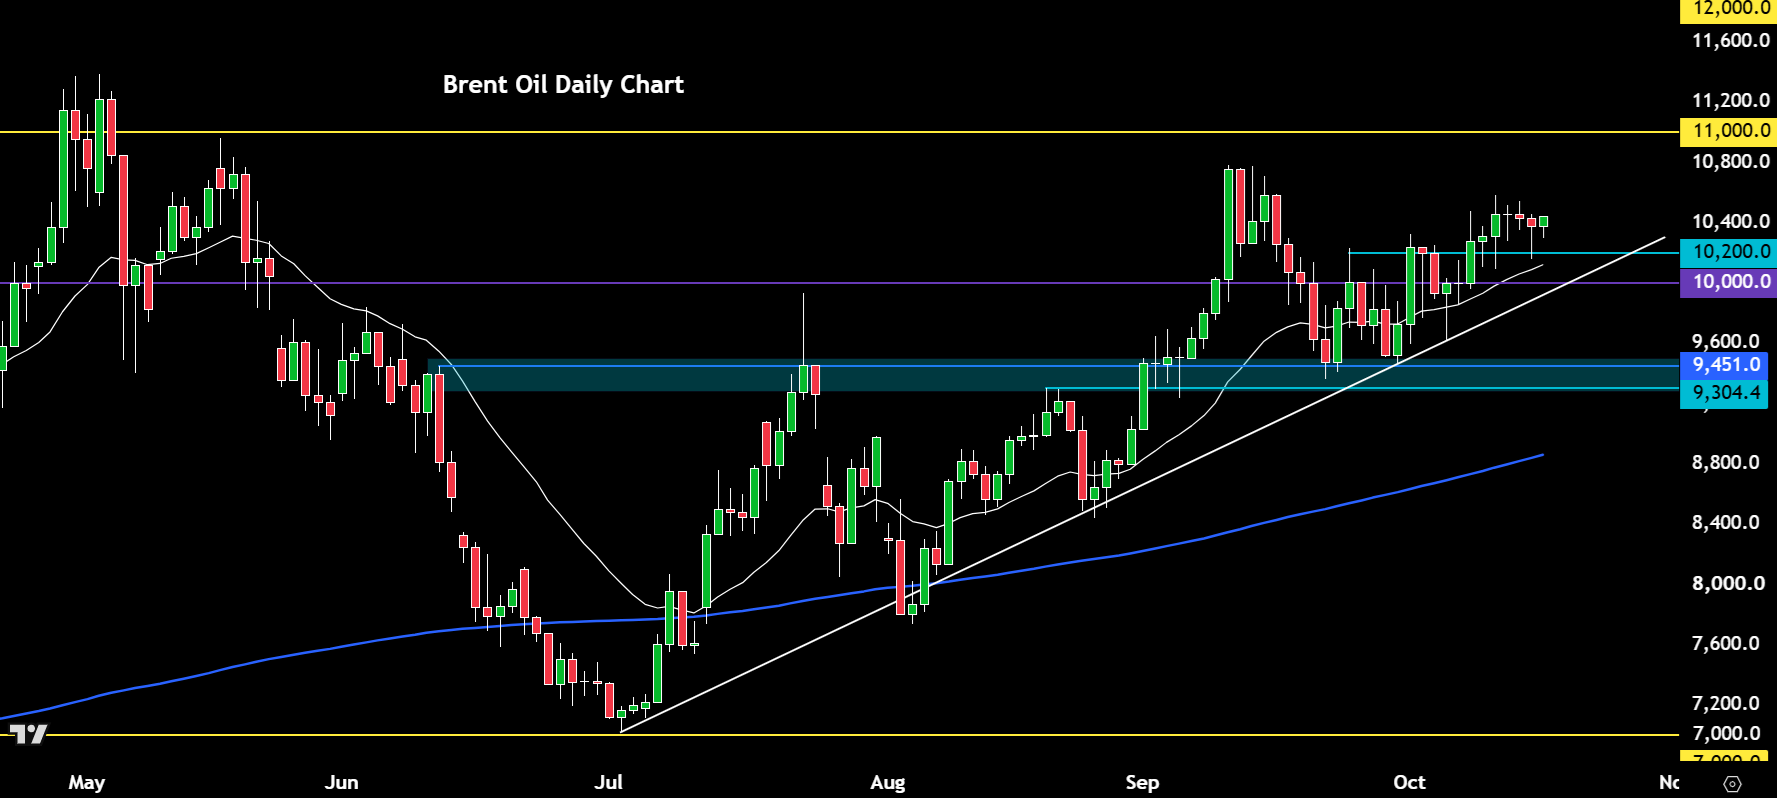
Crude oil prices have extended their gains….
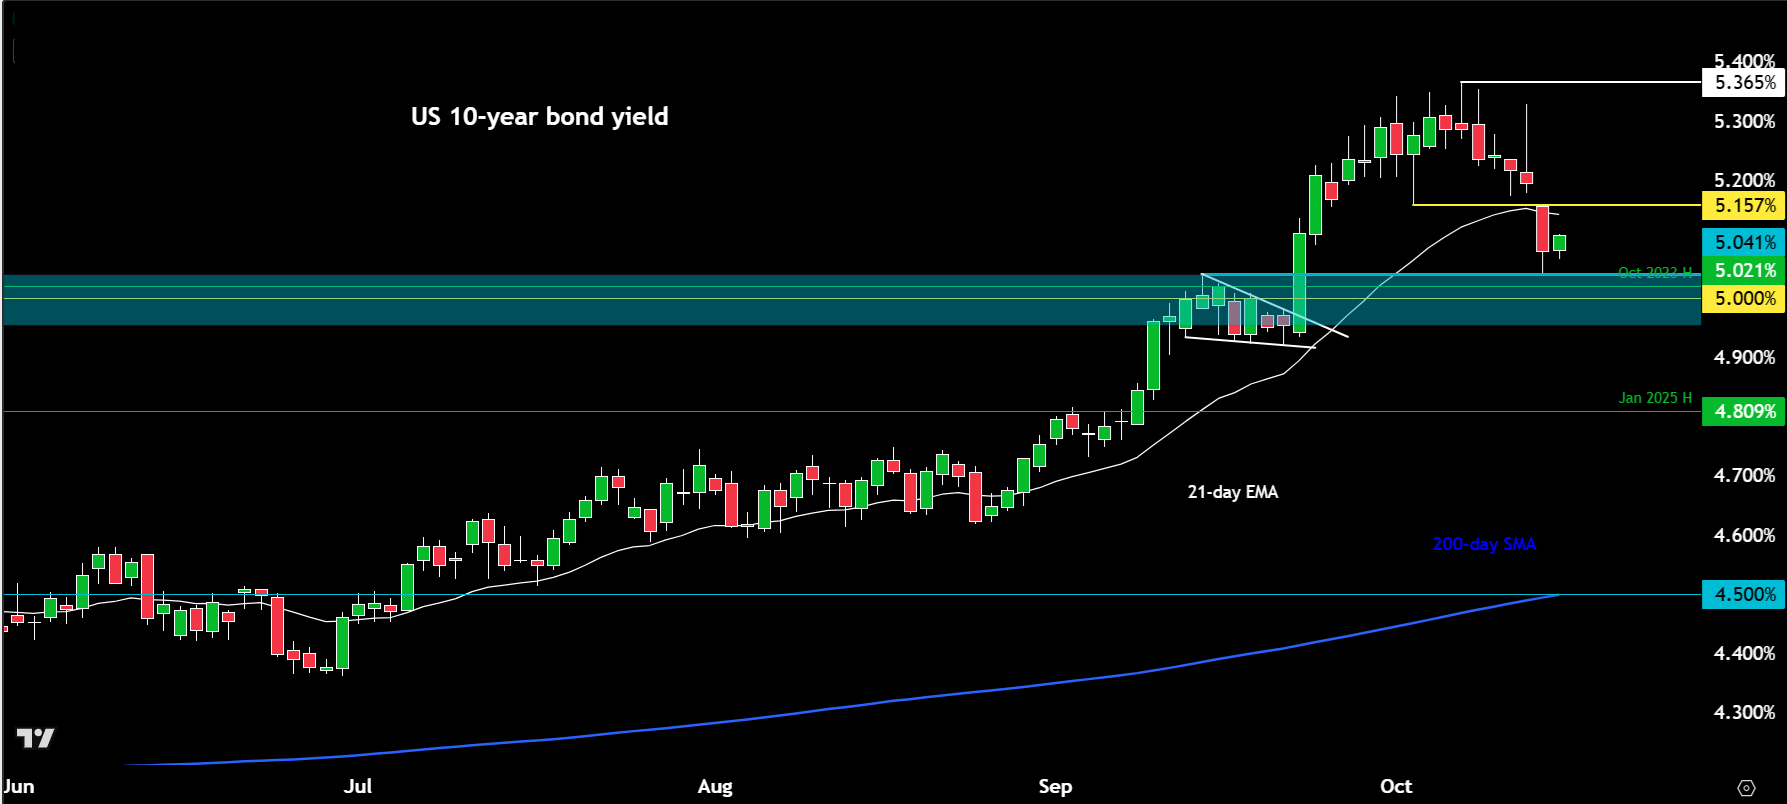
While bond yields are starting to bounce back again….
Meanwhile, the broader AI-related concerns remain unresolved. So, in many respects, I think we are back to square one.