- Bullish engulfing candle warns of potential NZD/USD reversal
- USD-rates relationship shows tentative signs of re-engagement
- October Fed tightening pricing has fallen sharply
- RBNZ swaps still imply an aggressive tightening cycle
A softer US payrolls report last Friday and less aggressive hawkish language from key Fed officials has seen expectations for an October rate hike from the FOMC pared back sharply.
However, entering early October, the US dollar showed little interest in the partial unwind of the historic surge in front-end yields seen through September, suggesting its previously strong relationship with rates had temporarily broken down.
But there are now tentative signs that relationship may be starting to re-engage, and with markets still pricing an aggressive RBNZ tightening cycle over the coming year, the combination has helped trigger a reversal pattern in NZD/USD that warns the bearish move from mid-August may have run its course.
NZD/USD turning point may be approaching
Source: TradingView
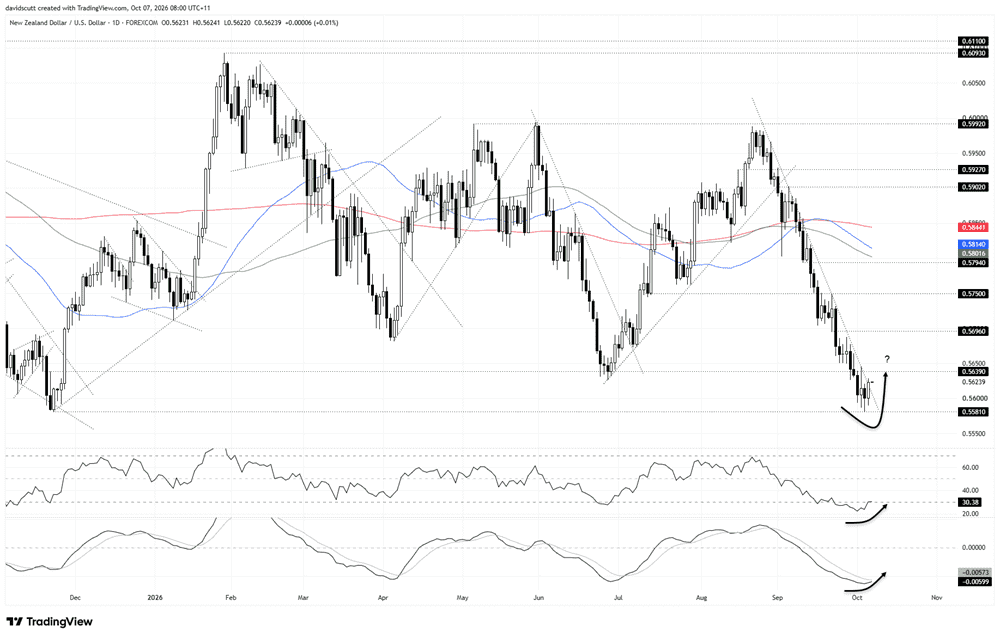
NZD/USD has undergone a pronounced bearish move since the highs set in mid-August, sliding from just shy of 0.6000 to below 0.5600 as downside pressure intensified.
After such a sizeable move that has taken the pair beneath its key medium and long term moving averages, the price action over the past few sessions suggests a turning point may be approaching.
The pair initially bounced from 0.5581, the swing low set in November last year, before Tuesday produced a clear bullish engulfing candle. Coming after such an extended bearish move, the pattern warns that directional risk may be starting to skew higher.
The latest daily candle has the price trading above the downtrend running from the August highs, further bolstering the case for near-term upside.
That view is backed by the oscillators. RSI (14) has established higher lows and is pushing out of oversold territory, while MACD is curling towards the signal line and appears close to a bullish crossover, albeit in negative territory, suggesting peak downside momentum may already have passed.
Overhead, 0.5639 has been respected on several occasions going back to late last year, making it the immediate focal point. A break above would bring 0.5696, a breakdown level from mid-September, into play, followed by 0.5750, which has acted as both support and resistance over recent months.
Below, 0.5581 remains the immediate point of interest. A break beneath would point to the potential for a deeper unwind towards the Liberation Day low of 0.5486 from April 2025 and the COVID low at 0.5470.
Dollar-rates breakdown may have been temporary
Suggesting the potential turning point may not be Kiwi-specific, similar reversal patterns have emerged across a range of G10 currencies against the US dollar so far this week.
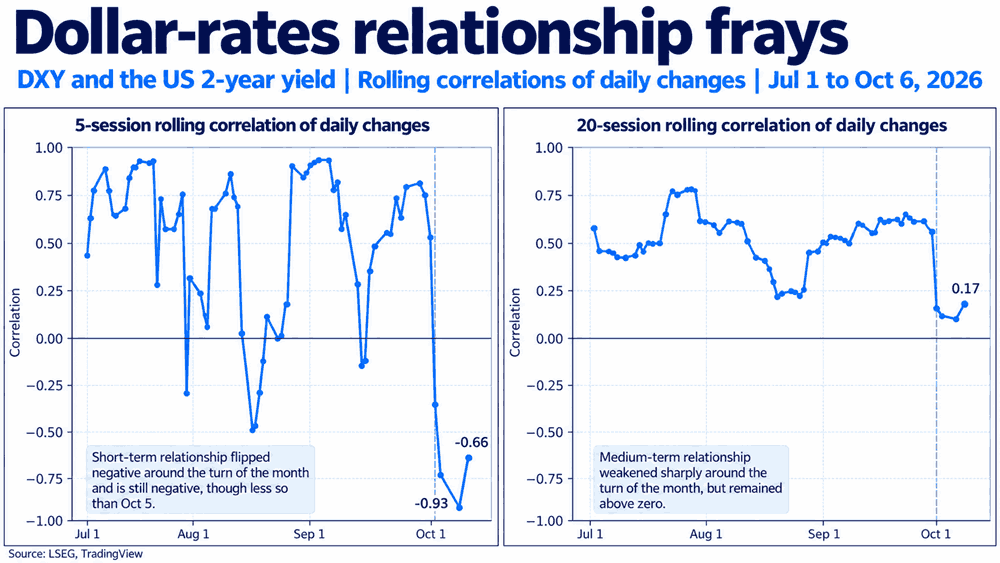
As shown in the graphic below, DXY had maintained a strong positive relationship with front-end US yields for several months, particularly over the 20-session window.
That relationship collapsed abruptly around the quarter turn. The five-session correlation between daily changes in DXY and the US 2-year yield fell from +0.83 on September 28 to -0.93 by October 5, while the 20-session measure also dropped sharply towards zero.
Source: LSEG
The abruptness and timing of the breakdown of this long-standing relationship suggests it may have been driven by window dressing and capital flows around the turn of the month, rather than a fundamental change in the dollar's relationship with front-end rates.
It's not concrete at this point, but there are tentative signs the relationship may be starting to re-engage. The five-session correlation has recovered to -0.66, while the 20-session measure has edged back to +0.17.
Neither is strong enough to suggest the relationship has reconnected, but combined with the reversal patterns across the G10 FX complex, it raises the possibility the broader dollar may also be approaching a turning point.
Fed pricing turns less hawkish
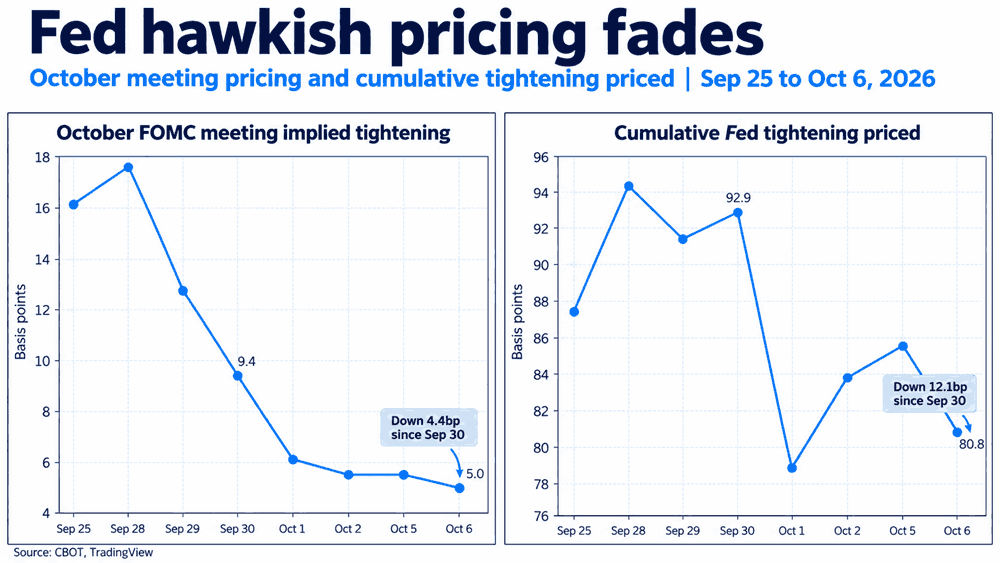
After an historic surge in September, a partial reversal has also taken place in US 2-year yields, coinciding with a sharp pullback in hawkish pricing for the Fed's October meeting.
At one point in late September, more than 17 basis points of tightening was priced for that meeting. Less aggressive hawkish language from New York Fed President John Williams and Vice Chair Philip Jefferson, helped by the softer payrolls print last Friday, has seen that fall to just five basis points.
Cumulative tightening over the next year has also come off the boil, falling from more than 94 basis points of hikes priced through the Fed funds futures curve in late September to just above 80 basis points at the time of writing.
Source: TradingView
FOMC minutes could test the reversal
In an otherwise quiet data week, the key risk for the US dollar today is the release of the September FOMC minutes.
Put bluntly, the tone is likely to be hawkish. The meeting delivered a unanimous 25 basis point hike, the Fed’s first in three years, alongside stronger growth forecasts, lower projected unemployment and an upward revision to the core PCE inflation outlook compared with June.
The dot plot also showed most officials expected at least one further hike this year, with some signalling moves in both October and December. That goes some way to explaining why markets continue to fully price another 25 basis point increase by December, even as expectations for an October move have been pared back sharply.
Given how hawkish the meeting was, the bar for the minutes to surprise in that direction looks high. But if there’s even a sprinkling of doubt over that outlook, it could add to the pullback in front-end yields and exacerbate the reversal already underway in the US dollar.
Kiwi still has domestic tailwinds
While the potential turning point for the dollar looks largely US-specific, that’s not to say there aren’t prevailing tailwinds also helping underpin the Kiwi.
The latest NZIER Quarterly Survey of Business Opinion, released on Tuesday, showed a significant improvement in sentiment, with a net 40% of firms expecting the economic outlook to improve, up from 14% previously. Investment and hiring intentions also strengthened, while there were signs spare capacity may be starting to dissipate, especially in the labour market.
Of course, that does not mean the Kiwi economy is suddenly roaring back to life. Hard data remains inconsistent and soft, fitting with a recovery still in its infancy.
But with inflation the RBNZ’s sole mandate, and persistently elevated energy prices combining with a softer New Zealand dollar to fuel imported inflation, swaps markets continue to price an aggressive outlook from the bank. A rate hike in October is deemed marginally more likely than not at around 60%, while a move by the December meeting after the general election is fully priced, with roughly a one-in-three chance of two hikes by then.
By the August meeting next year, more than four full 25 basis point hikes are priced, which would leave the overnight cash rate at 3.75% or higher, levels the RBNZ currently considers restrictive.