



DAX forecast: Markets remain sceptical and headline driven | Technical Tuesday
Markets remain firmly at the mercy of geopolitical headlines, and Trump’s constant social posts delivering mixed messages. The US dollar, stock indices, gold and crude oil are all continuing to swing on every update tied to the Middle East conflict. Traders are hanging on any signals around whether ceasefire talks are even remotely on the table. Until there’s something concrete, it’s hard to see risk appetite improving in any meaningful way.
Share this:
Markets remain firmly at the mercy of geopolitical headlines, and Trump’s constant social posts delivering mixed messages. The US dollar, stock indices, gold and crude oil are all continuing to swing on every update tied to the Middle East conflict. Traders are hanging on any signals around whether ceasefire talks are even remotely on the table. Until there’s something concrete, it’s hard to see risk appetite improving in any meaningful way. But there is a glimmer hope that we might be nearing the end of the conflict and that has allowed risk assets to take a pause from falling. Still, market will want clearer confirmation from Iran that talks are genuinely a) taking place and b) progressing — because, in this case, it takes two to tango TACO, and sentiment can shift quickly, as we’ve seen repeatedly over the past few weeks. So, while there has been a modest improvement in tone, it’s essential that we hear a similarly constructive message from Iran before drawing firm conclusions. Early signs are encouraging, but further confirmation is needed for us to turn bullish in our DAX forecast.
Headline-driven trading shows no sign of easing
Fighting between Iran and the US-Israeli alliance shows little sign of slowing, despite claims from Donald Trump that negotiations are underway. The result is that equity markets are still struggling for direction, while oil continues to remain supported as traders try to price in a wide range of outcomes.
As we have seen in recent days – actually, recent years - Donald Trump can single handedly cause major swings in markets. He posted on Truth Social yesterday about questionable talks with Iran, and that was enough to spark a fairly sharp rally in equity markets. At the same time, oil prices fell back as investors began unwinding risk-off positions. Markets were understandably quite volatile in the immediate aftermath of that post.
But there remains a lot of uncertainty over whether Iran is genuinely prepared to enter talks with the US. Still, the key takeaway for markets is that Trump appears willing to negotiate and potentially bring the conflict to an end. For now, that’s been sufficient for markets to start pricing in a de-escalation scenario.
Yet there is not a lot of conviction in that because of Trump’s constant flip-flopping. This has made it almost pointless to watch economic data releases in trying to determine what it might mean for markets. Nothing seems to matter right now but the Iran conflict and oil prices.
European PMI drop to 10-month low
The latest Eurozone PMIs print paints a fragile picture, with economic activity slipping to a 10-month low of 50.5 in March (composite PMI). While still just about in expansion territory, the drop signals that momentum is fading quickly.
It looks like the escalation in the Middle East has unsettled what was shaping up to be a modest recovery. Rising input costs and renewed supply chain disruptions are already feeding into inflation expectations, complicating the European Central Bank’s policy path. For markets, that raises the risk of rates staying higher for longer.
There’s a clear divergence between manufacturing and services. Manufacturing is holding up for now, but sentiment has turned cautious, while services activity, which is more exposed to consumer demand, is weakening sharply. With energy prices rising again, household spending could soften despite wage growth.
Ultimately, the economic outlook and therefore the DAX Forecast hinges heavily on geopolitics. A prolonged conflict risks derailing growth further, while a swift resolution could stabilise sentiment and limit inflationary pressure.
Technical DAX forecast: Key levels to watch
Equity indices, which have been under significant pressure during this conflict due to the surge in oil prices, enjoyed a bit of relief yesterday. One notable example was the DAX index, which attempted to reclaim the previously broken support level at 22,900. Ultimately however, it finished the session below this key hurdle yesterday. If it can manage a daily close above this level in the coming days, that would be a constructive — and indeed bullish — development from a technical standpoint. Of course, a lot can still change given the situation in the Middle East, but purely on the charts, that could prove to be a meaningful turning point, if it happens.
In terms of levels to watch, Friday’s high sits at 23,177, is another potential resistance. Above that you have the 23,500 area, which also aligns with Monday’s high and marks the base of the prior breakdown. Beyond that, we have last week’s key swing high at 23,961 and a break above that level in the coming days would go a long way towards confirming a broader reversal.
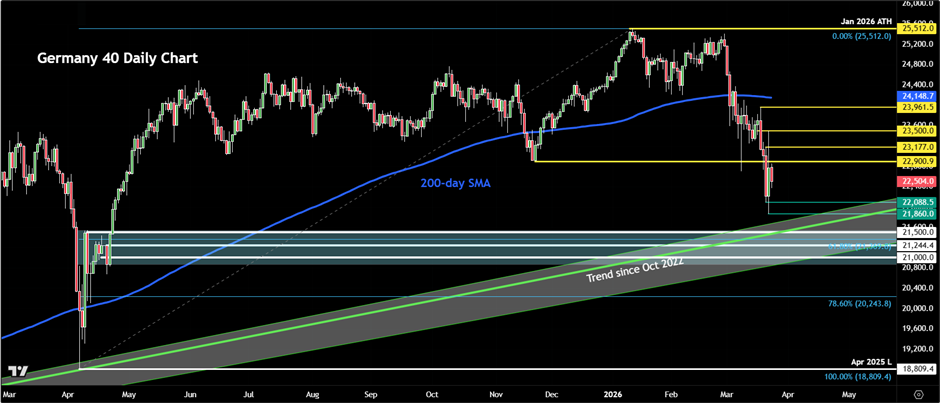
From a more cautious perspective, if the DAX were to fail to climb back above 22,900 on a daily closing basis in the coming days, that would keep bullish traders on the sidelines.
For now, markets have taken Trump’s social post yesterday as mildly positive — and let’s see whether it proves to be the beginning of a more lasting de-escalation.
If stocks resume selling, then the stops now resting below this week’s low of 21,860 will be in trouble. Below that the long term support area of 21,000 - 21,500 will come into focus next.
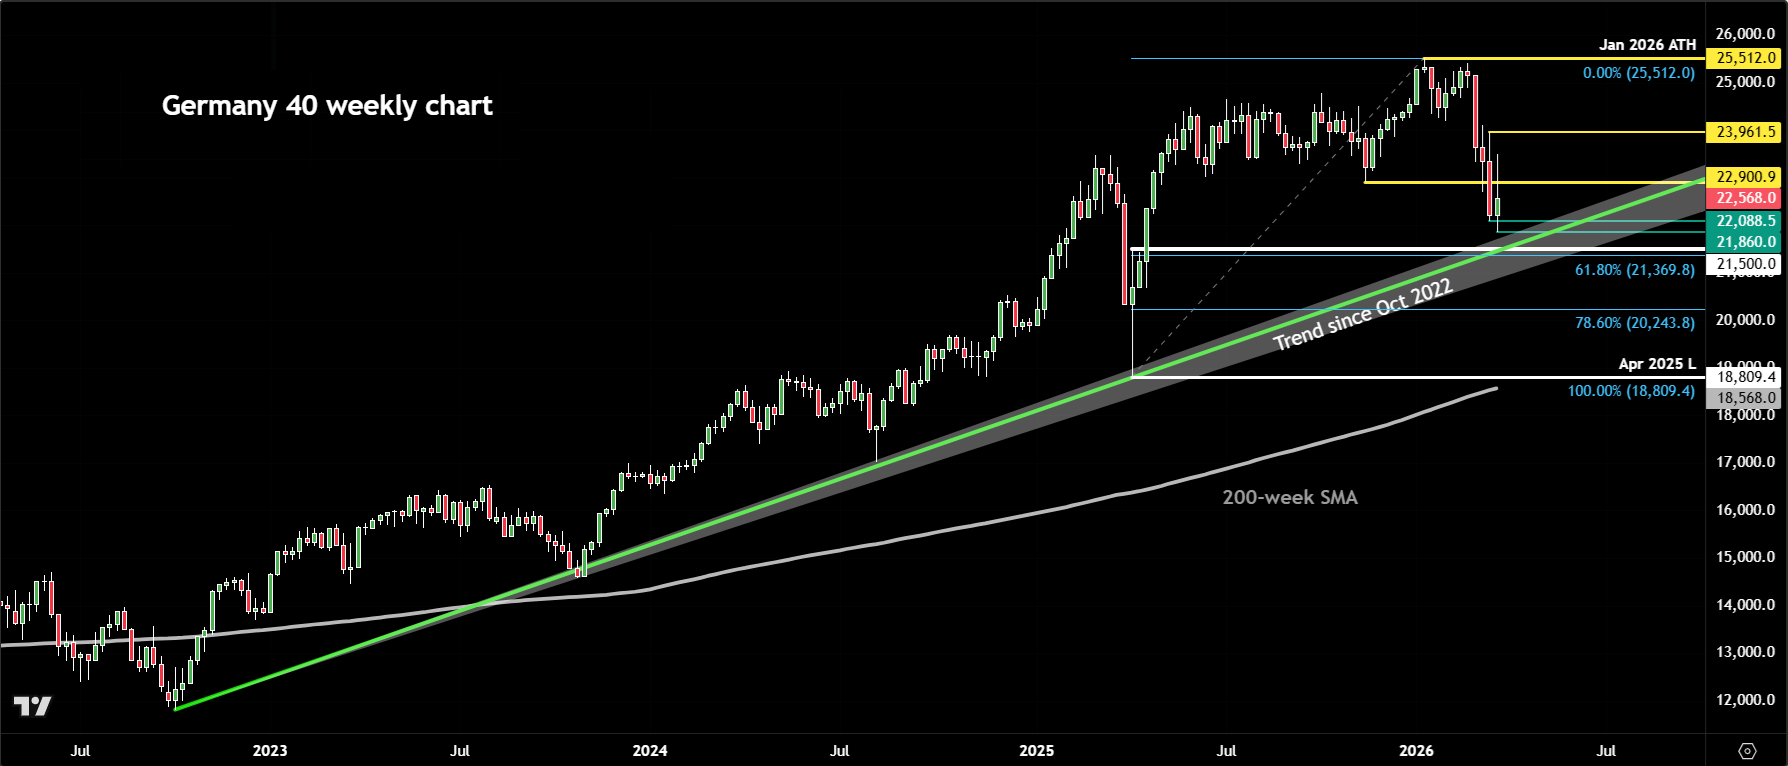
This is where a long term bullish trend line cuts through a prior support/resistance zone. We also have the 61.8% Fibonacci retracement level of the entire post-tariff bounce from April 2025.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.