



DJI outlook: Getting down with the Dow
Today we look at the Dow Jones which has seen momentum turn swiftly lower, in line with appetite for risk.
Share this:
It seems the days of simply buying the dip and hoping for the best are ‘long’ gone, with rallies petering out and reversing as market oscillate within weird and wonderful ranges. Whilst this is less than ideal for trend traders of higher timeframes, it can provide swing trading opportunities in both directions for bulls and bears. Today we look at the Dow Jones which has seen momentum turn swiftly lower, in line with appetite for risk.
US indices YTD returns:
- Nasdaq 100: 16%
- S&P 100: 8.7%
- S&P 500: 6.5%
- Dow Jones: 0.5%
- Russell 2000: -2.2%
Tech stocks have been the clear winner so far in 2023, thanks in part to a weaker US dollar, bets that the Fed are approaching their terminal rate and that they could potentially cut rates this year. Yet as this earnings season has so far highlighted, tech stocks are not a good representation of the broader market with around half of the S&P 500 companies trading lower for the year. Furthermore, mega-cap stocks such as NVIDIA and Meta have supported the broader index with 84.5% and 74% rallies YTD respectively. Therefore, to bet on a broader market upswing is to bet that underperforming stocks can rally higher whilst the love of tech stocks remains in place. That doesn’t look particularly likely over the near-term.
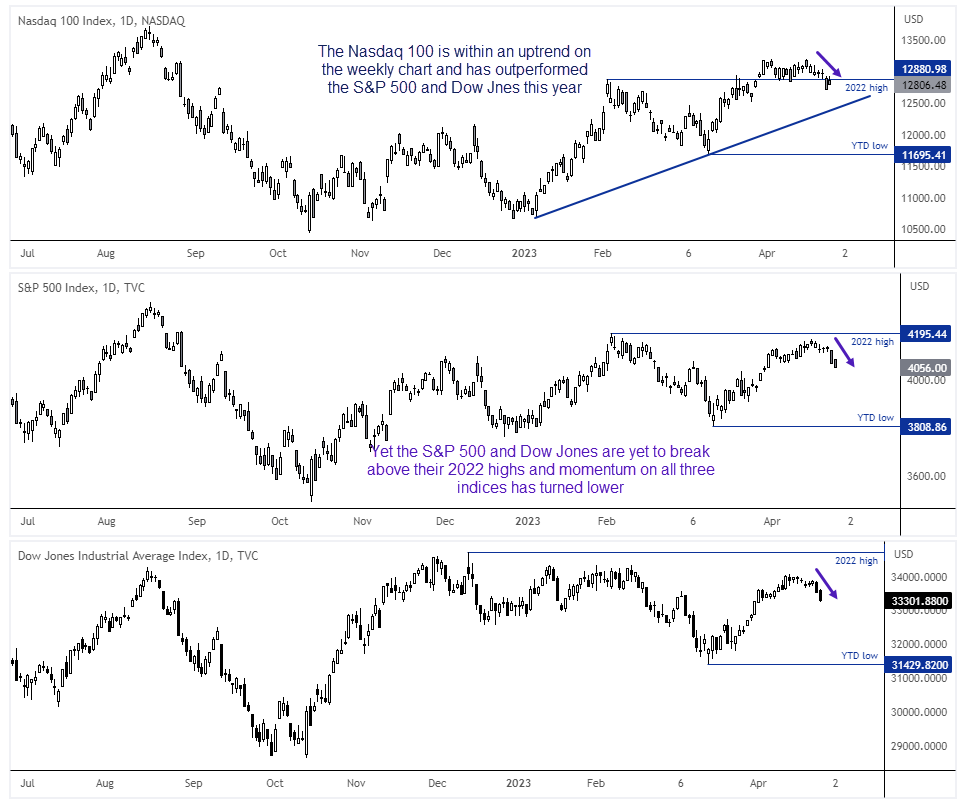
Momentum turns lower on Wall Street indices:
A look at the weekly charts of the three major Wall Street indices reveals a couple of points. The Nasdaq has carved out a bullish trend this year and broken above its 2022 highs, which is something the S&P 500 and Dow Jones has failed to do. And with momentum pointing lower for all three indices, the Nasdaq is now back beneath its 2022 high. Perhaps its bullish trend will remain intact and prices will now retrace towards trend support, which could provide bears with short opportunities over the near-term.
But we would prefer to short the underperformers during downturns (such as the Dow or S&P 500) before seeking bullish opportunities on the outperformer (the Nasdaq 100) should momentum turn higher for all three indices.
As the Dow has been the weaker performer this year, remains beneath its December low and has made the weakest attempt to test the 2022 high, we prefer short opportunities on the Dow.
Dow Jones (DJI) daily chart:
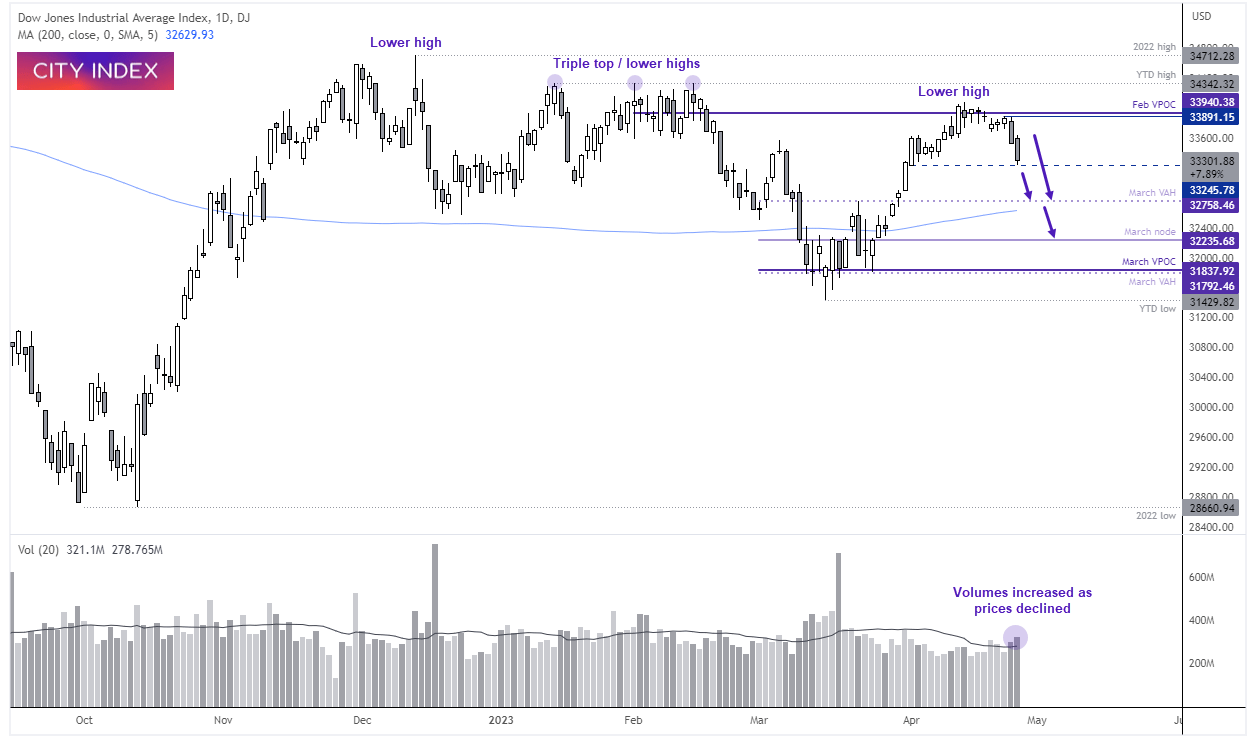
The Dow produced a prominent rally in October before topping out in December – a level it has struggled to retest since. January and February provided very choppy trading conditions and a triple top around 34,300. And despite an 8.5% from the March low, it has struggled to retest those highs. Also note that the recent rally petered out around the February VPOC (volume point of control) and daily trading volumes are increasing with falling prices, as bears step into the market. Ultimately, each rally produces a lower high and choppy trade as the market lacks the ambition to follow the Nasdaq higher.
- The bias remains bearish below 33900 and for a move down to 32,370
- We’d consider fading into rallies within the range of the past two days (which could help increase the potential reward to risk ratio)
- A break below 33,000 brings the 33,2758 high into focus (near the March VAH – value area high) and 200-day MA
- Should we see widespread risk-off across global markets, we could then consider lower targets around 33,265, 31,837-32,000 (March VPOC) and YTD low
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.