



Dow Jones Forecast: DJIA slips amid renewed US-Iran hostilities
U.S. stocks are set to open lower, easing back from record highs as rising oil prices and a flare-up in hostilities in the Middle East dent risk sentiment.
Share this:


US futures
Dow futures 0.94%, S&P futures -0.17% & Nasdaq futures 0.18%
In Europe
FTSE -0.18% & DAX -0.84%
- U.S stocks ease back from record highs
- Renewed US-Iran hostilities & a stalemate in talks hurt sentiment
- ADP payrolls beat forecasts, ISM services PMI data up next
- Oil rises as Middle East worries rise
U.S. stocks ease from record highs as Middle East tensions flare
U.S. stocks are set to open lower, easing back from record highs as rising oil prices and a flare-up in hostilities in the Middle East dent risk sentiment.
Oil prices have risen after Iran attacked neighbouring regions and the U.S. military carried out strikes close to the Strait of Hormuz. This, combined with a lack of progress in U.S.-Iran peace talks, raises concerns over ongoing supply disruptions, which could stoke broader inflationary pressures.
Optimism that the war would end sooner rather than later, combined with strong corporate updates and AI enthusiasm, had helped lift U.S. stocks to record highs. All three major indices closed at record highs on Tuesday, with the S&P 500 rising above 7,600 for the first time.
On the data front, ADP payrolls rose by 122,000, broadly in line with expectations for 117,000. This follows stronger-than-expected JOLTS job openings data yesterday, pointing to a resilient U.S. labour market ahead of Friday's non-farm payroll report.
Later today, the U.S. ISM Services PMI will be released and is expected to show that activity in the dominant services sector accelerated in May, rising to 53.8 from 53.6.
Solid economic data, a resilient labour market and inflation above target continue to support the view that the Federal Reserve could keep interest rates higher for longer.
Corporate movers
Private equity firms are under pressure after Bloomberg reported that Swiss-based investment group Partners Group capped withdrawals from one of its private equity funds. Blackstone is down 6%, while KKR has fallen 5.5%.
Palo Alto Networks is down 2% despite issuing stronger-than-expected revenue guidance for the current quarter and raising its full-year outlook. The company also beat earnings expectations, posting EPS of $0.85 versus forecasts of $0.80.
Marvell is rising on Wednesday, extending gains of 32% from Tuesday after Nvidia CEO Jensen Huang said the company could become the next trillion-dollar technology firm.
Macy's is up 1.5% after posting its strongest first-quarter growth in four years. Revenue came in at $4.68 billion, ahead of forecasts for $4.61 billion.
GameStop is rising 13% after reporting adjusted earnings of $0.30 per share in Q1, comfortably ahead of estimates of $0.16. Revenue also rose 14% year-on-year.
Dow Jones forecast – technical analysis
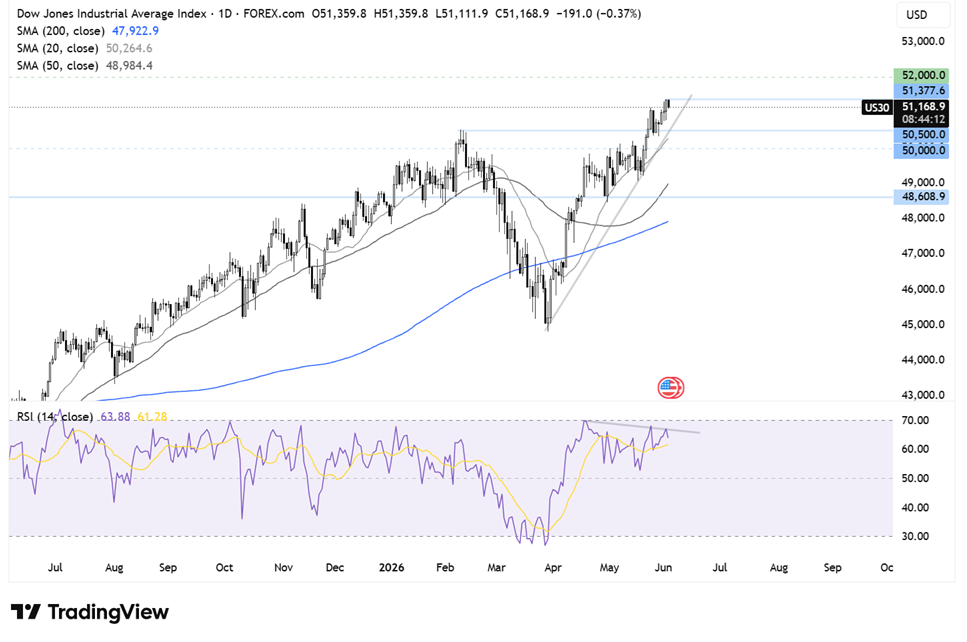
The Dow Jones has extended its recovery from the 44,826 low to a record high of 51,370. The index continues to trade above its rising trendline and the 20, 50 and 200 SMAs, keeping the broader bullish structure intact.
However, momentum is showing early signs of fatigue, with a bearish RSI divergence emerging. While this warrants some caution, there are currently few other signs of a reversal.
Buyers will look for a move above 51,370 to bring fresh record highs into focus, with 52,000 the next logical upside target.
On the downside, immediate support can be seen around 50,500, where the February high and rising trendline support converge, followed by 50,000, the psychological level. Below here, 49,000 comes into focus.
FX markets – USD rises, EUR/USD falls
The U.S. dollar is rising, tracking Treasury yields higher amid renewed tensions in the Middle East and resilient U.S. economic data. Elevated oil prices are helping to sustain inflation concerns, while solid economic data continues to support expectations that the Fed could keep rates higher for longer.
EUR/USD is under pressure amid the stronger dollar and as eurozone business activity contracted at the fastest pace in 18 months. The composite PMI fell to 48.5 in May from 48.8 in April, with a reading below 50 signalling contraction.
Meanwhile, input costs rose at their fastest pace in three and a half years, while prices charged to customers climbed to a 38-month high, marking a third consecutive month of accelerating output price inflation. The combination of weaker growth and persistent inflation highlights the difficult balancing act facing the ECB ahead of next week's meeting.
GBP/USD is under pressure around 1.3450 amid a stronger U.S. dollar and after data showed UK services sector activity contracted in May for the first time this year as the Iran conflict pushed costs higher and weighed on demand.
Meanwhile, Bank of England policymaker Megan Greene said she sees a growing case for further rate increases, a more hawkish stance than Governor Andrew Bailey's comments earlier this week that there was no rush to move on rates.
Oil extends gains on Middle East concerns
Oil prices are rising around 2% on Wednesday, extending gains from the previous session as hostilities in the Middle East and stalled talks between Tehran and Washington raise concerns that a deal remains some way off.
The conflict has now entered its fourth month, and oil prices may still be underestimating the risks associated with the continued closure of the Strait of Hormuz. With peak summer demand approaching, concerns are growing that global inventories could tighten further if supply disruptions persist.
Data released yesterday showed that U.S. crude inventories fell for a seventh straight week, according to API figures. Crude stockpiles declined by 6.8 million barrels, pointing to robust demand and tighter market conditions.
Attention now turns to the government's EIA inventory report due later today for confirmation of the drawdown.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 Forecast: SPX tanks as tech rout resumes
U.S. trade sharply lower investors resume the chip selloff as the post-election euphoria is quickly unwound and as attention turns to upcoming economic data.
US Dollar Technical Outlook: DXY Bulls Fight to Hold Critical Support Ahead of NFP 11 5 2026
DXY bulls are attempting to defend a pivotal technical threshold, with the next reaction likely to determine whether the broader recovery survives.

Crude Oil, DXY Outlook: Geopolitical Risks Halt Sell-Offs in the Dollar and Oil
The U.S. Dollar Index, Brent and WTI are rebounding from key support levels and oversold conditions after steep sell-offs. U.S.–Iran tensions, inflation risks and rate expectations remain in focus.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.