

Equities Weekly Outlook: Q3 Banks Earnings - JPM, GS, WFG
Q3 Earnings Season kicks off with JP Morgan, Goldman Sachs and Wells Fargo Group on October .
Share this:
U.S. banks kick off the Q3 earnings season next week, with investors looking beyond potentially strong headline results for signs that surging Treasury yields are beginning to weigh on dealmaking, lending and credit quality.
JPMorgan, Goldman Sachs, Citigroup and Wells Fargo are due to report before the market opens on October 13, followed by Bank of America and Morgan Stanley on October 14.
Expectations are high, with third-quarter earnings for the largest banks forecast to rise around 20% year on year, supported by stronger investment banking and trading revenue. However, the outlook is becoming more complicated as Treasury yields climb to multi-decade highs, tightening financial conditions and raising questions about the sustainability of capital markets activity.
The 10-year Treasury yield has risen to 5.3%, its highest level since 2002, while the 30-year yield has moved above 6%, its highest level in 24 years. Against this backdrop, the KBW Bank Index has fallen 13% from its August record high.
The key question is whether stronger trading activity and investment banking revenue can offset the pressure from higher funding costs, softer lending demand and potential deterioration in credit quality. Markets will also be assessing the likelihood of further Federal Reserve rate hikes before year-end and the implications for bank profitability.
Investment banking revenue in focus
Investment banking fees will be a key focus, particularly following the rise in bond yields and the cancellation or postponement of several IPOs in late September, including those of Aura, Southbank AI and SB Energy.
Investors will be looking for guidance on fourth-quarter deal pipelines to determine whether recent uncertainty is translating into a more sustained slowdown in advisory and underwriting activity.
Bank of America’s CEO warned last month that investment banking fees across the industry could decline by at least 10% in Q3. JPMorgan, however, has indicated that investment banking revenue should increase, highlighting the divergence in expectations across the sector.
Banks with diversified retail and commercial banking operations could prove more resilient if capital markets activity disappoints. Nevertheless, higher rates may also increase deposit costs, constrain credit demand and place pressure on borrowers.
As an early indicator of U.S. financial conditions, corporate confidence and consumer resilience, the major banks’ results could have broader implications for the economic and market outlook.
JPMorgan Chase
JPMorgan is expected to report earnings per share of $5.94, up from $5.07 in Q3 2025, on revenue of approximately $50.1 billion.
Second-quarter results delivered record revenue and profitability, supported by exceptionally strong markets and investment banking activity. The bank has maintained expectations for investment banking fees and trading revenue to rise in the mid-to-high teens year on year.
Net interest income will also be closely watched, with expectations of $26.84 billion compared with $24.07 billion a year earlier. Higher interest rates can support lending margins, although the ultimate benefit will depend on deposit pricing, asset repricing and loan demand.
Costs and profitability will remain in focus amid wage inflation, technology investment and rising AI-related expenditure. Investors will want to see whether revenue growth is translating into sustainable earnings growth or being absorbed by higher operating costs.
How to trade JPM earnings
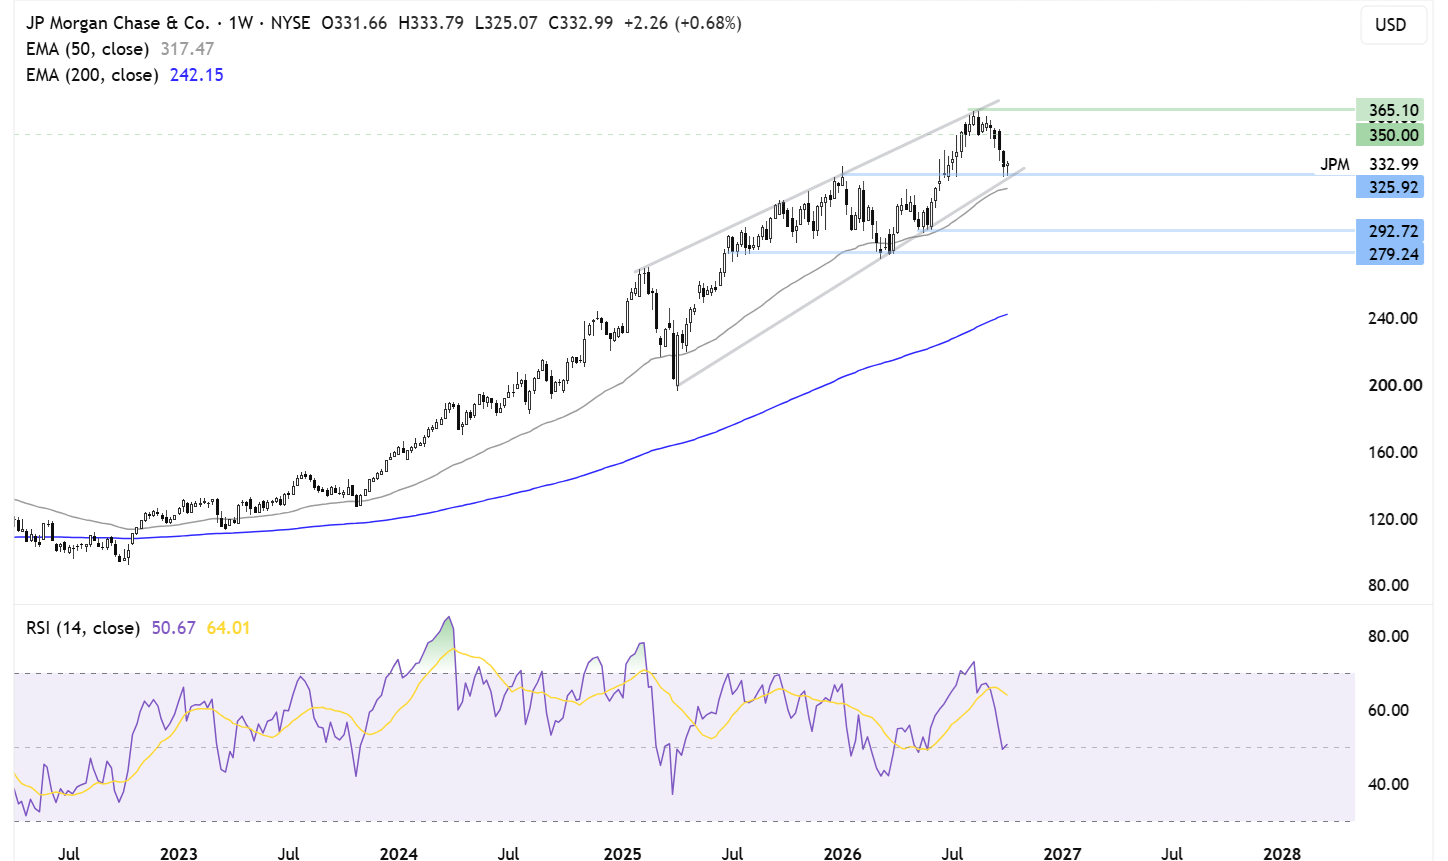
JPMorgan is trading within a rising wedge pattern. After reaching resistance at the record high of $363, the share price pulled back towards rising trendline support, while holding above $330, the January high.
Sellers would need to break below $330 and $325, where horizontal and trendline support converge, to strengthen the case for a bearish reversal. Below these levels, attention would turn to the 50-day EMA at $316, followed by $300.
If support holds, buyers will look towards $350 before retesting $363 and potentially establishing fresh record highs.
Goldman Sachs Earnings Preview
Goldman Sachs is expected to report earnings per share of $12.44 on revenue of approximately $16.8 billion. This compares with EPS of $20.98 on revenue of $20.34 billion in Q2 and EPS of $12.25 in Q3 2025.
CEO David Solomon has indicated that investment banking activity would be more muted in Q3, while fixed income, currencies and commodities (FICC) trading could soften following a strong equities business.
The market will be looking for evidence that investment banking and advisory fees can remain resilient despite higher bond yields and potential IPO delays. The strength of equities trading will also be crucial in determining whether it can offset weaker FICC revenue.
Goldman remains particularly sensitive to capital markets conditions, making the sustainability of M&A activity, underwriting fees and trading revenue central to its earnings outlook.
How to trade GS earnings
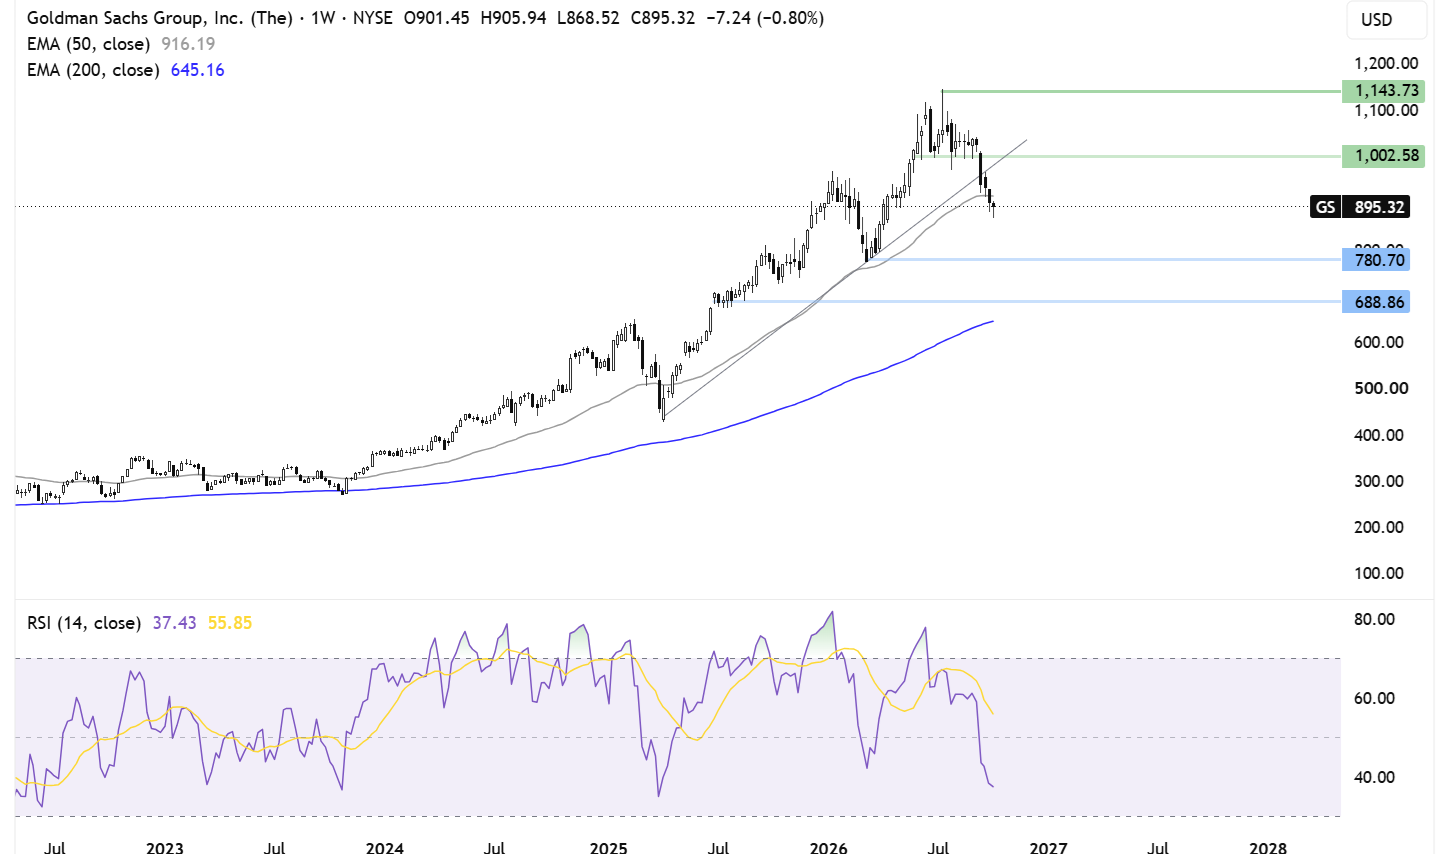
After reaching a record high of $1,148, Goldman Sachs has retreated sharply, breaking below rising trendline support and the 50-day EMA before falling to $868. The RSI below 50 reinforces the bearish near-term momentum.
Sellers will look to extend losses towards the 2026 low of $775, followed by $683, the July 2025 low.
A recovery would need to reclaim the 50-day EMA at $915 to improve the technical outlook. Above this level, attention would turn towards $1,000 and the broken rising trendline resistance.
Wells Fargo
Wells Fargo is expected to report EPS of $1.85 on revenue of $22.15 billion, compared with EPS of $1.66 and revenue of $22.42 billion in Q3 2025.
Loan growth will be a key focus, with analysts looking for evidence that demand remains healthy. Net interest margin will also be closely watched as the bank rebuilds its balance sheet, adds lower-yielding assets and shifts towards lower-cost customer deposits.
The central question is whether Wells Fargo can deliver a sustained recovery in net interest margin rather than simply beat quarterly earnings expectations.
The removal of its regulatory asset cap provides greater scope to expand lending and other assets. However, the benefit will depend on the returns generated by new assets relative to their funding costs. Higher Treasury yields could complicate that process by increasing competition for deposits and raising borrowing costs.
How to trade WFC
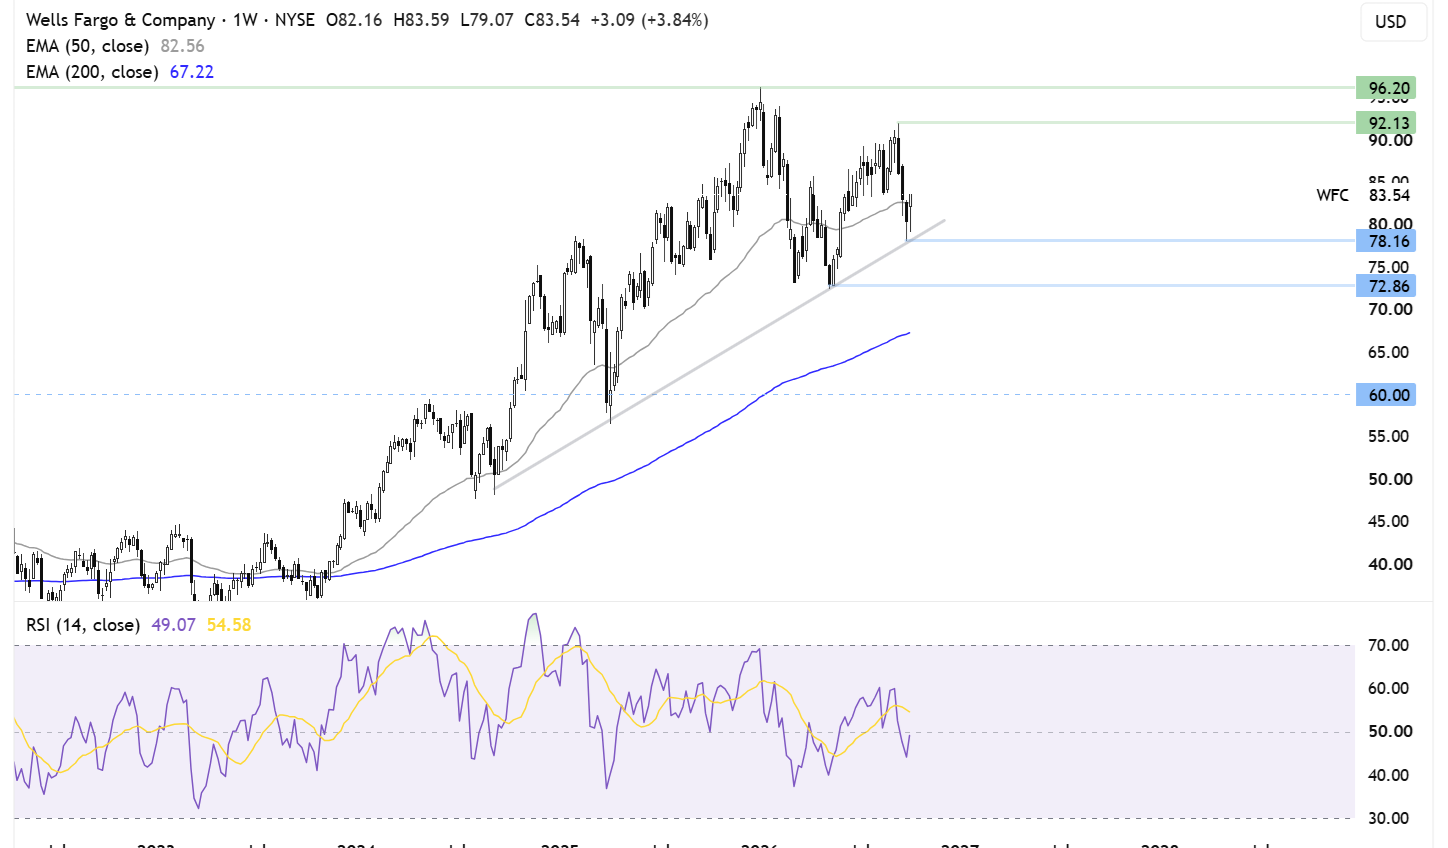
Wells Fargo reached a record high of $96 at the start of 2026 before pulling back. The share price remains above its rising trendline and both its 50- and 200-day EMAs, keeping the broader technical outlook constructive.
Buyers will look to extend gains towards $92, the September high. A break above this level would bring $96 back into focus.
Conversely, a break below rising trendline support would weaken the outlook and expose $78, followed by $72. A further decline would bring the 200-day EMA at $67 into focus.
The bottom line
The major U.S. banks enter Q3 earnings season with expectations for strong year-on-year earnings growth, supported by trading and investment banking activity. However, rising Treasury yields present a growing challenge.
Investors will be looking beyond headline earnings beats for evidence that higher funding costs are not eroding margins, that capital markets activity can withstand tighter financial conditions and that credit quality remains resilient.
For JPMorgan, the focus is on the durability of broad-based revenue growth. For Goldman Sachs, the key test is whether strong equities trading and advisory activity can offset softer FICC revenue. For Wells Fargo, the priority is evidence of a sustainable recovery in net interest margin.
Ultimately, forward guidance may matter more than the headline numbers, particularly if banks begin to signal that elevated yields are weighing on lending, dealmaking and the wider U.S. economy.
Related tags:
Latest market news
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Equities Weekly Outlook: Q3 Banks Earnings - JPM, GS, WFG
Q3 Earnings Season kicks off with JP Morgan, Goldman Sachs and Wells Fargo Group on October .
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.