





Equity brief Trade trepidation and Fed fatigue
Earnings disappointment was exacerbated by Trump tweets downplaying the chances of a trade breakthrough
Share this:
Stock market snapshot as of [30/7/2019 6:11 PM]
- Some solid if not stellar European heavyweight earnings failed to offset a similarly sized raft of disappointment whilst the session on both sides of the Atlantic was garnished by Trump tweets downplaying the chances of a trade breakthrough
- Sentiment was damped further on The Continent by further data prints pointing to a slowing German economy; several German states reported monthly inflation that missed forecasts, though the Federal-level result for July beat. French growth was similarly lacklustre in the second quarter
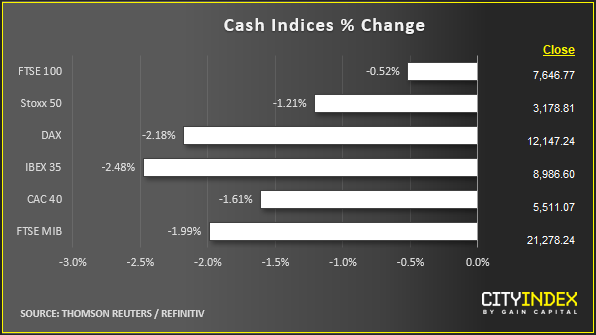
- Germany’s DAX and related contracts are seeing their worst day since the end of May with the cash gauge down 2.2%
- The Fed’s preferred inflation series was also quite weak in June. With probability of a 25-basis point rate cut on Wednesday tracking around 100%, positive indications of a move back towards the central bank’s target is a silver-lining that’s already priced in
Corporate News
- Oil at least is a positive story—sort of—with key contracts on course for a seventh rising session in eight, underpinning the U.S. energy sector. The S&P 500’s Energy sub-index rose 0.4% a while ago on a combination of tensions over state-backed actions in the critical Strait of Ormuz and seasonal refinery shutdowns
- A raft of giant European—particularly German—groups also darkened the mood. Lufthansa weighed German markets most, losing 6%, as it remains at the epicentre of European travel sector woes; Chemicals group Bayer was down 3.7% after warning on crop product weakness whilst litigation drags on; Delivery Hero slid, though Britain’s Just Eat fell more, as the German online takeaway app said it wasn’t bidding for its rival after all; FTSE 100 consumer product maker Reckitt slumped 3.2% after missing estimates and reducing guidance; BP was a relative star, topping the UK benchmark with a solid if not spectacular set of earnings, earning the shares a 3% rise
Upcoming corporate highlights
Upcoming economic highlights

Stock market snapshot as of [30/7/2019 6:11 PM]
- Some solid if not stellar European heavyweight earnings failed to offset a similarly sized raft of disappointment whilst the session on both sides of the Atlantic was garnished by Trump tweets downplaying the chances of a trade breakthrough
- Sentiment was damped further on The Continent by further data prints pointing to a slowing German economy; several German states reported monthly inflation that missed forecasts, though the Federal-level result for July beat. French growth was similarly lacklustre in the second quarter
- Germany’s DAX and related contracts are seeing their worst day since the end of May with the cash gauge down 2.2%
- The Fed’s preferred inflation series was also quite weak in June. With probability of a 25-basis point rate cut on Wednesday tracking around 100%, positive indications of a move back towards the central bank’s target is a silver-lining that’s already priced in
Corporate News
- Oil at least is a positive story—sort of—with key contracts on course for a seventh rising session in eight, underpinning the U.S. energy sector. The S&P 500’s Energy sub-index rose 0.4% a while ago on a combination of tensions over state-backed actions in the critical Strait of Ormuz and seasonal refinery shutdowns
- A raft of giant European—particularly German—groups also darkened the mood. Lufthansa weighed German markets most, losing 6%, as it remains at the epicentre of European travel sector woes; Chemicals group Bayer was down 3.7% after warning on crop product weakness whilst litigation drags on; Delivery Hero slid, though Britain’s Just Eat fell more, as the German online takeaway app said it wasn’t bidding for its rival after all; FTSE 100 consumer product maker Reckitt slumped 3.2% after missing estimates and reducing guidance; BP was a relative star, topping the UK benchmark with a solid if not spectacular set of earnings, earning the shares a 3% rise
Upcoming corporate highlights
Upcoming economic highlights
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Midterm Fallout: What Does the “Blue Tsunami” Mean for the S&P 500?
Democrats made sweeping gains in the US midterm elections, winning control of both the House and Senate - what does it mean for the S&P 500 and the AI trade?

S&P 500 forecast: Democrats’ midterm victory rattled markets before dip buyers stepped in
Markets had a wild overnight session, with futures initially plunging before staging a sharp reversal and turning decisively higher. Global equity markets also bounced back, alongside gold and silver, while the US dollar has weakened. Oil prices fell on hopes of a deal between the US and Iran, providing another boost to market sentiment. The key question is why have markets rebounded so strongly and, more importantly, whether the recovery can last, given the prior assumption that a blue sweep would have been net negative for stocks?


Silver, Nasdaq Outlook: Democratic Win Supports Risk-Asset Rebounds
A Democratic win in the U.S. midterm elections is supporting rebounds in risk assets, including precious metals, currency pairs, cryptocurrencies and U.S. indices. This reaction appears to align with changing sentiment around the war and its inflationary impact.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.