


EUR/USD Slides as French Unrest Returns. What Has Really Changed?
French unrest has sent EUR/USD lower, but with sovereign risk already priced into bonds, hedge funds heavily short and the US dollar struggling to rally, how much bad news is left to sell?
Share this:
- EUR/USD opens lower following widespread civil unrest in France
- French sovereign spreads widened sharply before stabilising last week
- Net short positioning approached the extremes reached in July
- Hot US inflation failed to produce sustained dollar strength
- Buyers have repeatedly emerged on EUR/USD dips beneath 1.1200
EUR/USD opened lower in Asia on Monday following scenes of widespread civil unrest across France over the weekend, with some of the most violent clashes, looting and vandalism taking place in Paris.
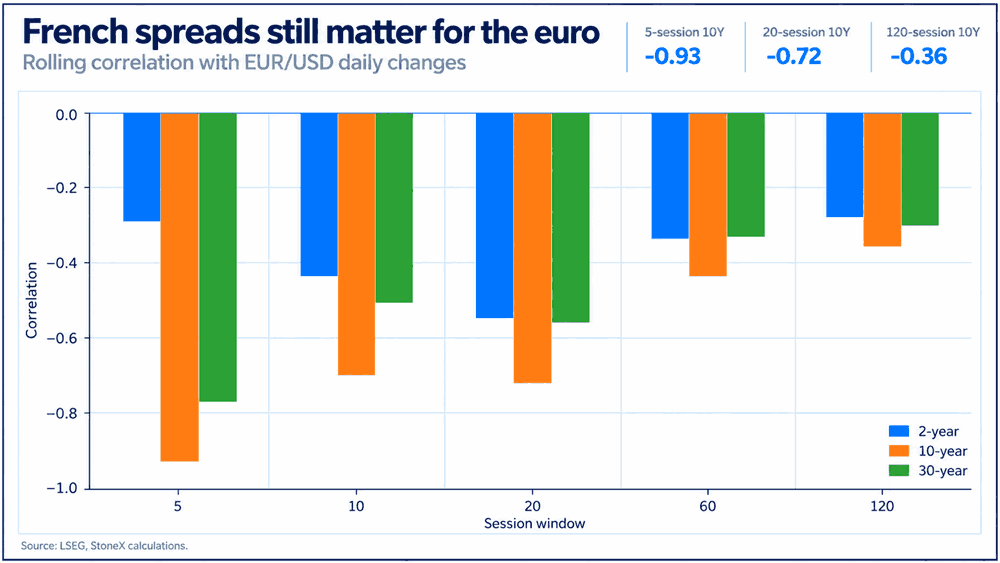
However, it's been the performance of French government debt, rather than political headlines alone, that's had a more powerful influence on the euro recently, as seen in the graphic below tracking the rolling correlation between French OAT-German bunds.
While we won't get a proper assessment of how bond traders are responding to the weekend's developments until European markets open, there's a reasonable question to ask: what exactly have we learned that we didn't already know?
Source: LSEG
France's deteriorating fiscal position, political fragmentation and difficulties pushing through meaningful budget consolidation have been apparent for years, even if they've attracted renewed scrutiny over recent months. French government bond spreads have already widened substantially relative to German Bunds, with political uncertainty hardly a new consideration ahead of next year's presidential election.
While that doesn't mean the situation can't deteriorate further, for the latest unrest to drive a sustained reassessment of the euro, markets arguably need evidence that France's fiscal or political outlook is becoming materially worse than investors had already anticipated.
And when you consider this pair faces political uncertainty not only in Europe but also in the United States ahead of the US midterm elections, it's difficult to see why this weekend's unrest alone would justify another sustained bout of aggressive euro selling.
French spreads show stress, but little fresh deterioration
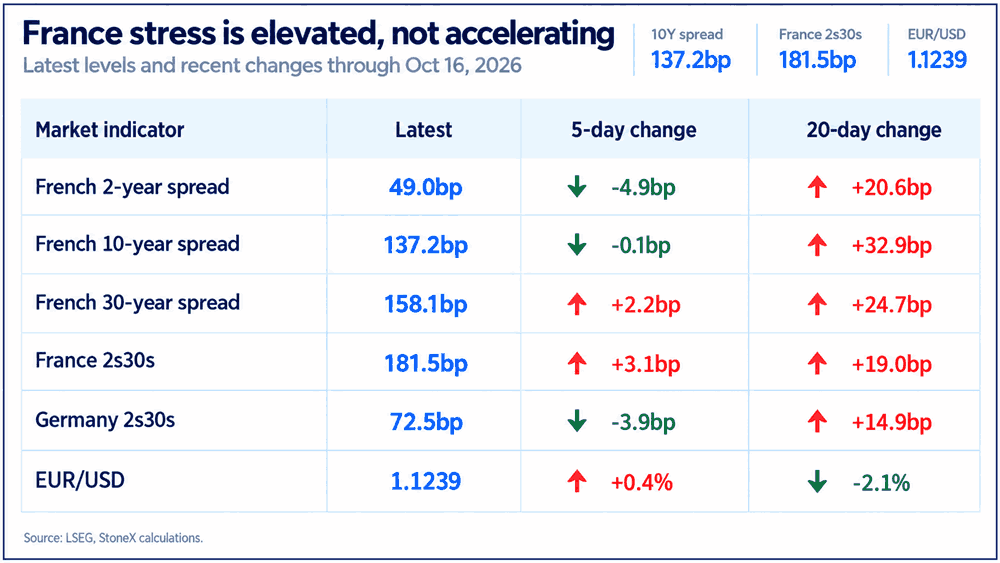
There's no question French debt has been under the pump recently. Over the past 20 sessions, the yield premium to own French bonds over comparable German Bunds has widened by roughly 21, 33 and 25 basis points at the two, 10 and 30-year tenors respectively.
However, that deteriorating trend stalled last week, with the two-year spread narrowing by around five basis points and the 10-year tenor virtually unchanged.
Source: LSEG
One week's price action always needs to be treated with caution, but at face value, it suggests renewed French fiscal concerns and political uncertainty may already be largely baked into the price.
If the weekend's developments fail to spark another meaningful widening in French sovereign spreads, the latest unrest may not lead to an extension of the euro's early weakness in Asia, especially with bearish positioning among leveraged traders already sitting at fairly extreme levels.
Leveraged funds pile into euro shorts
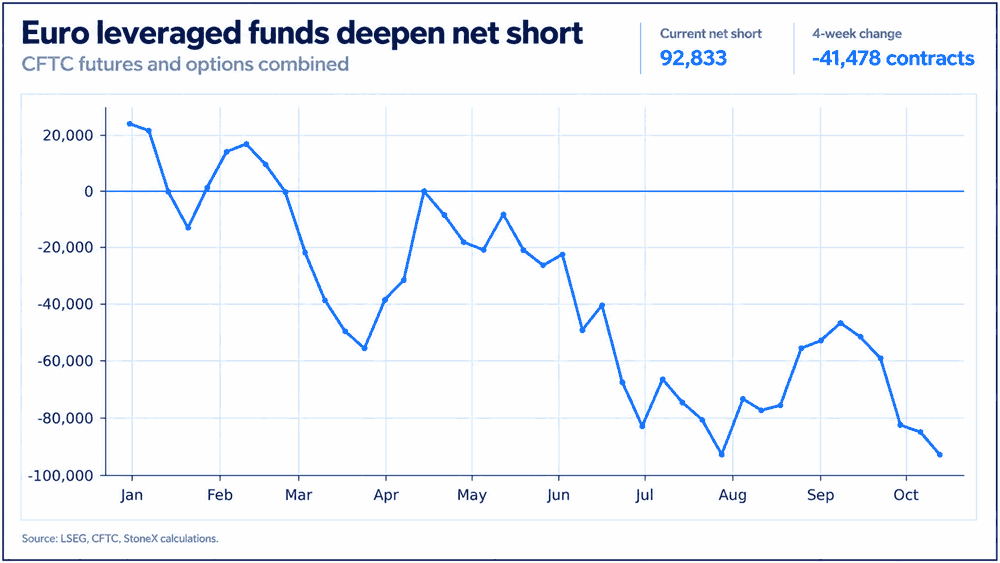
Source: LSEG
According to CFTC data, leveraged funds increased their net short euro exposure by 41,478 contracts over the four weeks to October 13, a shift ranking among the most bearish 5.6% of comparable periods since 2006.
That left net short positioning at 92,833 contracts, almost identical to the levels reached in late July.
Importantly, those figures predate the weekend's unrest, providing a snapshot of positioning as of Tuesday afternoon in New York last week.
But with leveraged funds already heavily positioned short, extending the euro's decline will require existing bears to become even more bearish, or fresh sellers to enter the market. Neither is out of the realms of possibility, clearly, but it does raise the question of how much additional selling pressure the latest developments will generate.
US dollar bulls had their chances
It's not just positioning that raises questions about the potential for a resumption of EUR/USD downside, with the US dollar's performance last week revealing in its own right.
US CPI and PPI data for September both came out way hotter than expected, while sharp declines in tech stocks, driven by renewed AI doubts, provided another source of safe-haven demand, which was seen in Treasury markets.
Yet despite those apparent tailwinds, the dollar struggled, particularly towards the back end of the week, ultimately resulting in EUR/USD breaking out of the downtrend running from the early September highs.
If the dollar is unable to rally on obvious fundamental catalysts, perhaps that's the strongest message of all in terms of its near-term directional risk.
EUR/USD technical analysis
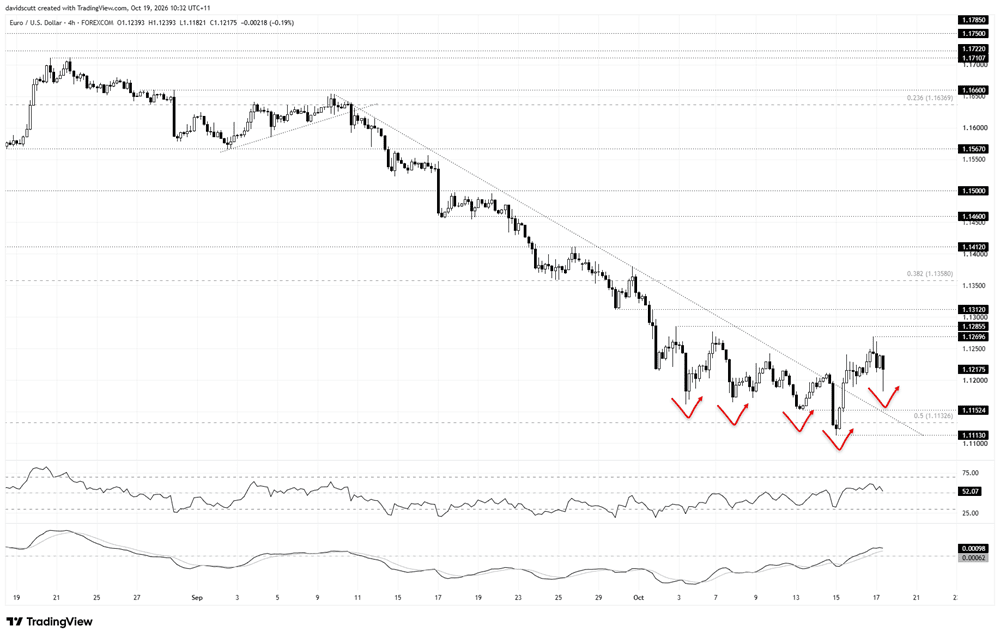
Source: TradingView
EUR/USD broke the downtrend running from the early September highs last week, bouncing strongly from just above 1.1100, which coincides with the 50% retracement of the January 2025 to January 2026 bull move.
From there, the price reclaimed 1.1200 before stalling around 1.1270 late last week. The opening four-hourly candle in Asia on Monday saw EUR/USD dip back beneath 1.1200, but as was the case towards the back end of last week, buyers stepped in aggressively, pushing the pair back above that level.
While the momentum indicators are warning bulls against chasing the move higher, they're not providing a definitively bearish signal either. RSI (14) has been setting lower highs and is back around the neutral 50 level, while MACD is converging towards its signal line but remains in positive territory.
Looking at the price action, what's clear is that dips beneath 1.1200 have been well supported recently, with buyers repeatedly stepping in following sharp declines since the beginning of October.
On the downside, 1.1152 is a minor level to watch beneath Monday's earlier low, followed by 1.1113, the swing low set last week.
Overhead, last week's high around 1.1270 is the first level to watch, followed by minor resistance at 1.1285 and 1.1312, before the 38.2% Fibonacci retracement of the January 2025 to January 2026 bull move at 1.1358.
With little on the economic calendar this week, political headlines could play a larger role in driving short-term price action than would ordinarily be the case, at least until Friday's flash PMI releases.
Related tags:
Latest market news
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
FX Futures Positioning: US Dollar Bulls Face Crowded FX Shorts
US dollar bulls build exposure as EUR, GBP and AUD shorts reach extremes. COT data hints at potential rebounds despite persistent USD strength.
EUR/USD Slides as French Unrest Returns. What Has Really Changed?
French unrest has sent EUR/USD lower, but with sovereign risk already priced into bonds, hedge funds heavily short and the US dollar struggling to rally, how much bad news is left to sell?
AUD/USD: Are Record Short Bets a Breakout Signal or Sentiment Extreme?
Record AUD/USD futures shorts raise the risk of a bearish breakout, but stretched positioning and bullish divergences suggest bears should remain cautious.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.