



EUR/USD: Stalemate deepens as tariff noise clouds directional risks
Fresh tariff threats have revived familiar USD underperformance themes, yet the euro has so far struggled to capitalise. With EUR/USD stuck in a stalemate and the calendar thinning, conviction remains elusive.
Share this:
- Tariff threats revive familiar USD underperformance narrative
- Euro struggles to benefit as EUR/USD stalemate persists
- Conviction fades with calendar offering few catalysts
- Nvidia earnings loom as potential volatility trigger
Summary
Trade tensions have returned, yet EUR/USD continues to drift without conviction. Headline risk, a thinning calendar and fragile technical signals leave directional risks far from straightforward.
Tariff threats revive familiar market themes
Fresh tariff noise from Donald Trump has once again dragged trade tensions back into focus, a theme markets are becoming painfully familiar with. Following the Supreme Court’s decision to strike down his emergency tariffs, Trump warned that countries reconsidering recently negotiated trade deals could face significantly higher duties imposed under alternative legal channels.
The timing of those remarks hardly feels coincidental. In Brussels, the European Parliament opted to delay its vote on the trade agreement struck in Scotland last year. While the revised tariff rate under Section 122 mirrors the level embedded in the deal, the original tariffs themselves were ruled illegal by the highest court in the United States, making it understandable why European lawmakers may prefer to pause ratification.
Trump’s warning reads for what it is: an unambiguous threat directed at the EU and other trading partners. Rather than reducing uncertainty, the messaging reinforces the reality that trade policy remains an active source of volatility, capable of shifting with little warning.
For EUR/USD, the broader playbook remains frustratingly familiar. Periods of sustained trade tension have tended to coincide with bouts of USD underperformance, driven less by macro factors and more by confidence effects, capital flows, and the re-emergence of the sell America narrative. That pattern was evident around last year’s Liberation Day tariff shock and resurfaced earlier this year during the Greenland tariff drama.
The complication, as always, is durability in the ‘TACO’ era. Markets know they are effectively one Truth Social post away from renewed volatility. In theory, that leans supportive for the euro. In practice, conviction is weak.
Given the backdrop, the more likely near-term outcome may be messy, headline-driven price action. The kind that generates plenty of technical signals but very little clarity, placing greater emphasis on follow-through price action for confirmation.
That risk may be amplified by a relatively quiet economic calendar this week, leaving markets with few obvious macro anchors. The standout event arguably comes from outside the traditional data cycle, with Nvidia’s Q4 earnings release due after the market close on Wednesday.
Despite Nvidia’s consistent history of beating expectations across the key metrics, concerns around the sustainability of returns on AI-related capex remain elevated. Any signs of underlying softness could easily trigger renewed turbulence in tech, an outcome that may encourage further capital rotation away from US equities towards other regions, including European markets.
Stalemate defines EUR/USD price action
Source: TradingView
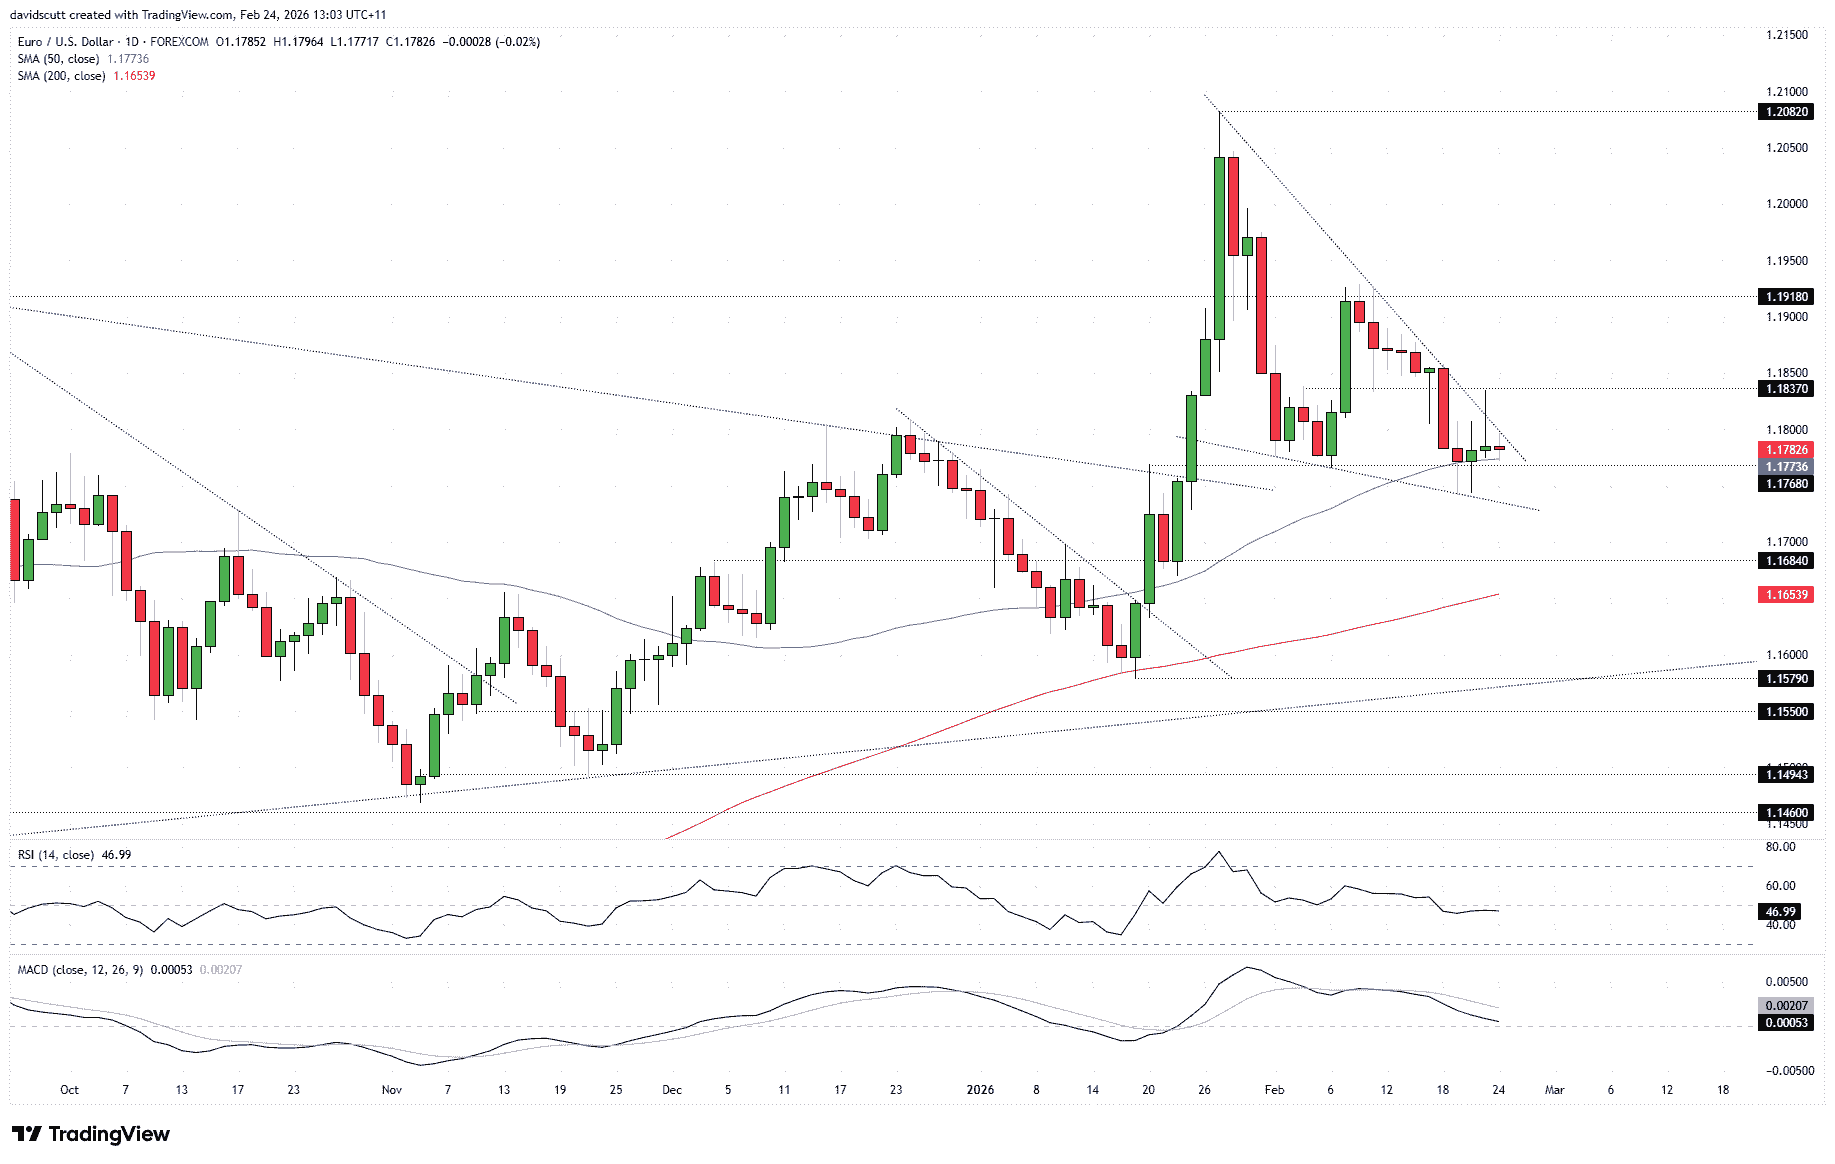
The stalemate in the price action is the first thing that stands out technically, reflecting the uncertain backdrop. Bulls are lurking around the 50DMA/1.1768 support zone given the bounces seen from beneath it over the past week. At the same time, bears are not budging either, as demonstrated by the bearish pin candle that printed Monday after a breakout attempt through the January 27 downtrend flamed out ahead of 1.1837 resistance. That price signal, while not emerging after a prolonged bullish trend, warns that downside risks remain in play.
So, we have a falling wedge structure which, by convention, may eventually be resolved by a bullish breakout and a potential retest of the YTD highs. However, the initial attempt was anything but convincing. From a technical perspective, to get genuinely excited about a sustained upside break, a close above Monday’s high would help validate the signal.
Given the proximity of price to both wedge resistance and the nearby support zone ahead of wedge support, if there is to be a decisive break from the structure, it will likely need to happen soon. Otherwise, upside risks may begin to fade, with the balance of risks skewing sideways to lower.
A break beneath the 50DMA/1.1768 support zone would shift focus towards wedge support. That level has only been tested once since being established, leaving price action there critical for confirmation. Should the pair trade cleanly through it, downside risks would likely increase, placing levels such as 1.1684 and the 200DMA into view.
The trend in RSI (14) and MACD suggests bulls may be running out of time to deliver a meaningful breakout. RSI is now tracking beneath 50, while MACD has crossed below its signal line and is drifting towards negative territory. Should those trends persist, the case for shifting from a neutral to bearish directional bias strengthens.

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.

Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.