


GBP/USD forecast: Currency Pair of the Week | August 17, 2026
There will be some key data from the UK to watch this week, which could set the tone for the pound, while the macro calendar in the US is a lot quieter. Once again, much of the market’s direction may therefore come down to crude oil. The greenback has been weighed down in recent weeks by a softer run of data which has reduced expectations of a Federal Reserve rate hike in September.
Share this:
There will be some key data from the UK to watch this week, which could set the tone for the pound, while the macro calendar in the US is a lot quieter. Once again, much of the market’s direction may therefore come down to crude oil. The greenback has been weighed down in recent weeks by a softer run of data which has reduced expectations of a Federal Reserve rate hike in September. This has allowed currencies such as the pound to climb somewhat more noticeably during this period, owing to a higher yield advantage in the UK than currencies where interest rates are low or zero, such as the Swiss franc. However, looking ahead, the GBP/USD forecast is still far from bullish given the risks oil prices pose to inflation and growth.
Oil holds gains as US-Iran standoff persists
Oil prices are consolidating last week’s sharp gains as the deadlock over the Strait of Hormuz continues. President Donald Trump has warned Americans to prepare for higher fuel prices, underscoring the potential economic fallout from the disruption. While there were some reports that there may be some extension to the ceasefire agreement, this is not the first time we have heard such headlines before they were subsequently denied by Iran.
The standoff around the Strait of Hormuz has caused traffic through the key shipping route to fall sharply. The disruption has been compounded by attacks on tankers operated by Abu Dhabi and on a Saudi Aramco refinery, highlighting concerns over the security of both shipping and oil infrastructure across the region.
For now, oil markets remain firmly in wait-and-see mode. Any fresh escalation around the Strait of Hormuz, could easily send prices sharply higher. Conversely, signs of a return to negotiations could ease supply concerns and leave room for some of last week’s gains to unwind.
Dollar under pressure but dovish Fed pricing factored in
Friday’s softer-than-expected US retail sales data for July has strengthened the argument against a September rate hike. On top of this, we have also had some in-line inflation data last week and a poor jobs report in recent weeks. Markets have not only reduced their tightening expectations for the September meeting, but their expectations for cumulative tightening through next year have fallen to around 35 basis points.
The US data calendar this week offers relatively little that is likely to alter that picture. The main event is Wednesday evening’s release of the minutes from the 29 July FOMC meeting.
That meeting produced a 9-3 vote to leave rates unchanged and was followed by a particularly confusing press conference. Since then, US activity data have softened somewhat. Even if the minutes contain references suggesting that the decision was closer than the headline vote implied, it may be difficult for markets to revert to a firmly hawkish interpretation of the Fed without good support from oil prices. That said, it is also worth pointing out that most of the dovish dollar pricing is already factored into the markets. For the dollar to fall sharply from here, the macro backdrop will have to deteriorate significantly.
Pound supported by yield advantage
The prospect of the Fed keeping rates unchanged for longer has provided further support for global risk assets. Investors appear comfortable maintaining long positions in carry and commodities, funded in part by lower-yielding currencies such as the Swiss franc. This has allowed currencies where interest rates are comparatively higher to outperform. The UK base rate is currently similar to the US at 3.75% and is one of the highest among G10 currencies, with only Australia having a higher base rate of 4.35% at the moment. As a result, the GBP/USD has found decent support in this environment.
UK CPI among key data highlights
The markets are currently pricing in around 55bp of Bank of England tightening. With the UK economic calendar becoming more interesting after several relatively quiet weeks, those expectations are subject to change. Labour-market and wage data are due on Tuesday, followed by July’s CPI figures on Wednesday. After back-to-back falls in the previous couple of months, CPI is expected to have climbed back to 2.9% year over year in July compared to 2.6% y/y in June. With GDP overshooting last week, any upside surprises could further support the resurgent GBP, while any dovish surprises could see the GBP/USD give back some of its recent gains.
GBP/USD forecast: technical analysis and levels to watch
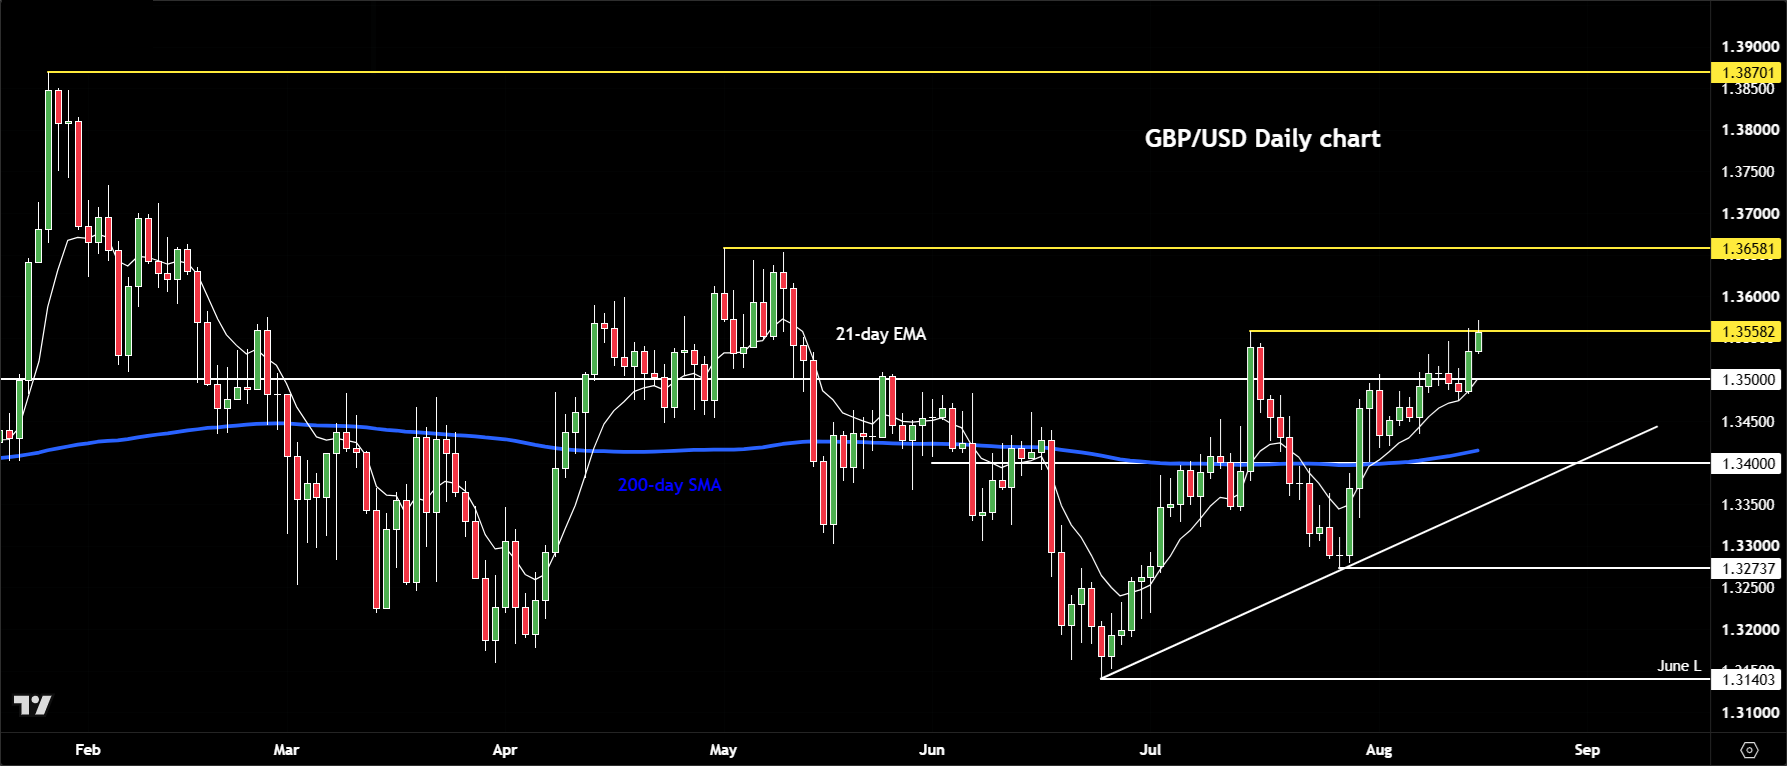
At the time of writing, the GBP/USD was testing its highest levels since mid-May. While that may sound impressive, it is also worth noting that the cable is basically stuck inside a long-term consolidation phase. The near-term momentum has still been more on the bullish side with the pair now back above the 21-day exponential average having spent only a few days below the 200-day average in the last weeks of July. With former resistance levels such as 1.3400 and 1.3500 reclaimed, these will now be the key levels of support to watch on any near-term dips. The early May high of 1.3658 is the most important reference point to keep an eye on should the bullish momentum build here. Above that, the January high is at 1.3870.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Dollar forecast: NFP provides dollar, already supported amid tech sell-off, additional boost
The US dollar has found some mild amid the tech rout in recent days, most visibly against risk sensitive and commodity dollars. Today, we have so far seen a bit of a recovery in global indices from their overnight lows. Investors will be watching the markets to see whether fresh losses will be on the again once Wall Street gets going. Ahead of that, we have just seen the release of the October US non-farm payrolls report – and it was much stronger at 165K than expected.
Nikkei 225 bear market deepens as volatility surges
The Nikkei has entered a technical bear market following a historic plunge. RSI and ATR stretch readings suggest a bounce may be coming, but history carries a warning for dip buyers.


ASX 200 Futures Hold Relatively Firm as Nikkei Plunges After Wall Street Rout
Wall Street's AI-led rout sends Nikkei futures plunging 9%, while ASX 200 futures hold relatively firm despite surging volatility and broader risk aversion.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.