


Japanese Yen Forecast: USD/JPY climbs as yields take charge after Powell’s pivot
USD/JPY remains driven by U.S. yields after Powell signalled rate cuts aren’t guaranteed, keeping the dollar bid and attention fixed on upcoming U.S. data and Japan’s wage and spending figures.
Share this:
- Government shutdown delays key U.S. data, limiting Fed visibility
- ISM services PMI and ADP jobs in focus Wednesday
- Wages data key for Japan’s December BOJ decision
- USD/JPY bullish bias retained
Summary
USD/JPY remains led by U.S. yields, with Powell’s pushback on rate cuts keeping the dollar supported. With key data missing due to the shutdown, Fed commentary and private surveys will set the next move, while bulls hold control above key support.
Powell Pivot Sparks Rates Revival
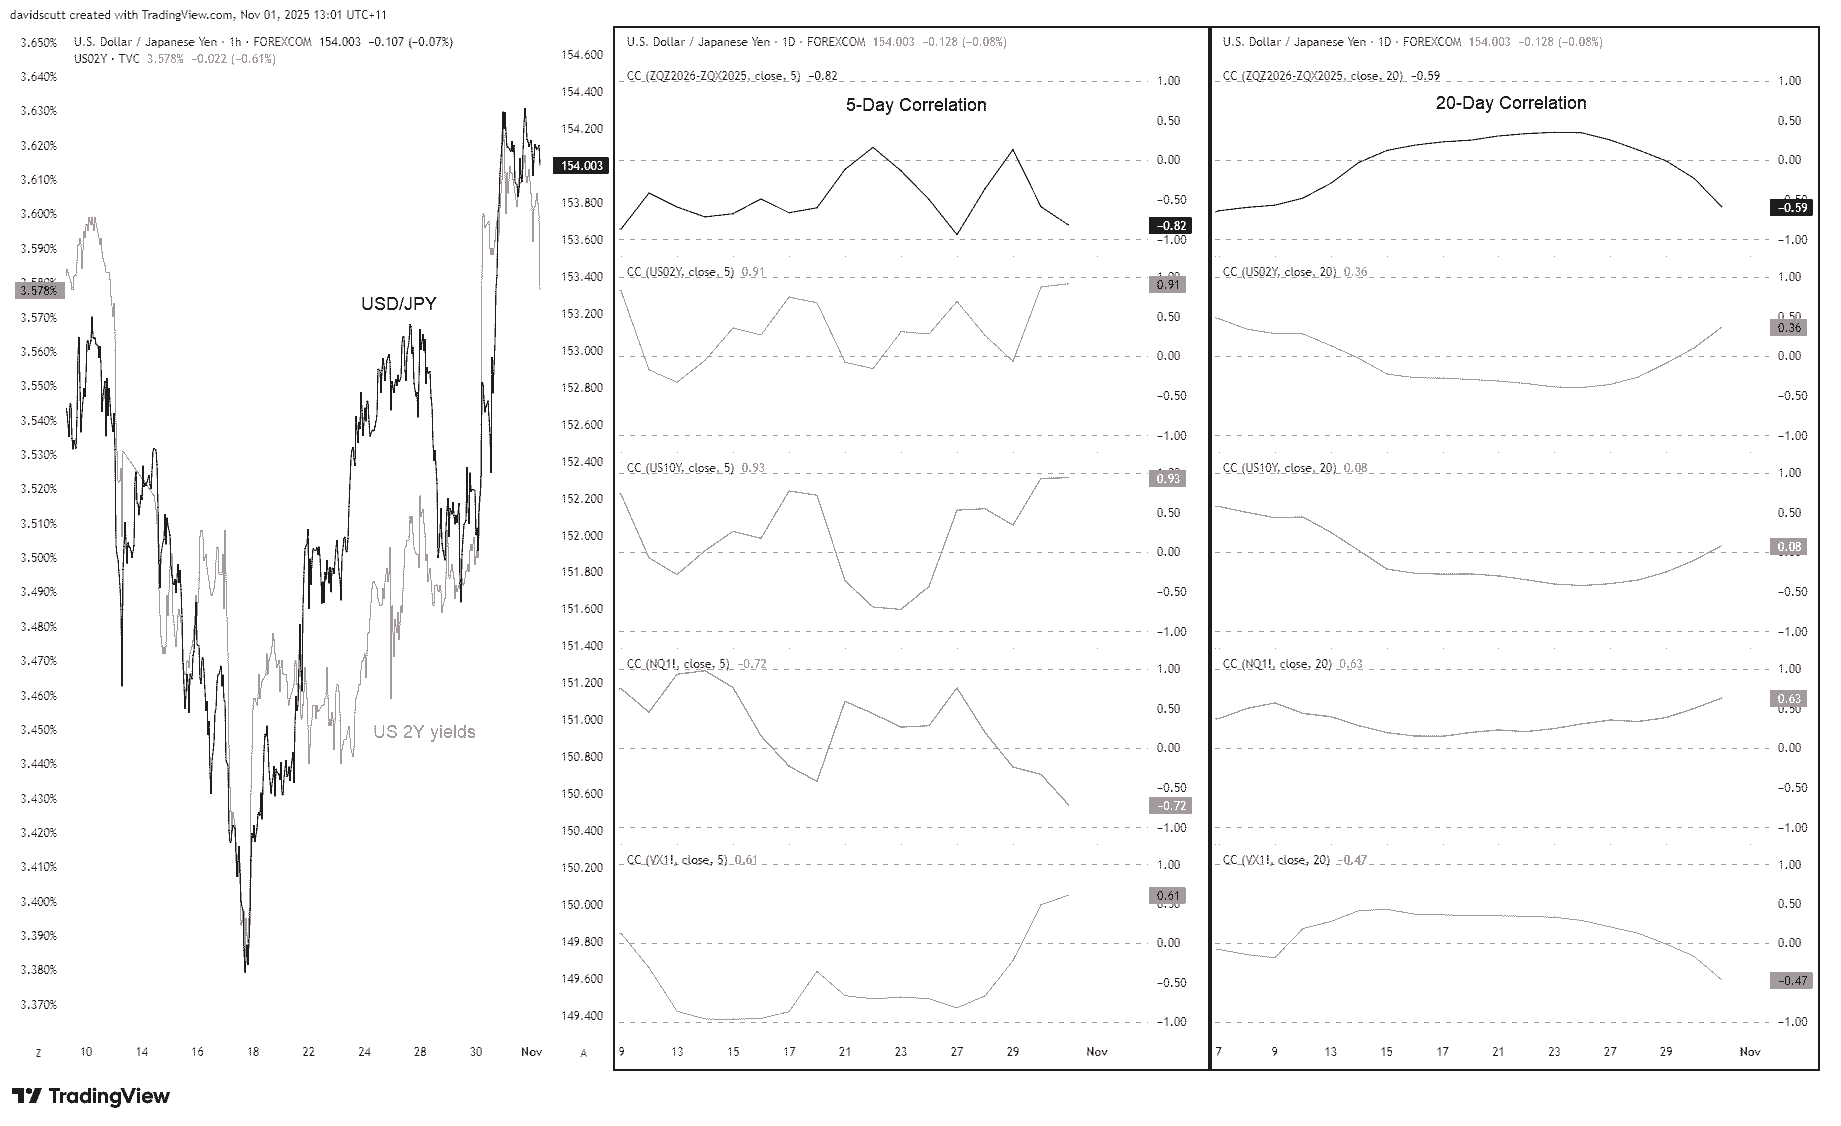
The U.S. interest rate outlook is back in the driver’s seat for USD/JPY after the surprise hawkish shift from Fed chair Jerome Powell following last week’s FOMC decision. The chart below tells the story, with the left-hand pane showing how USD/JPY has been tracking U.S. two-year Treasury yields in recent weeks. It’s clear both have moved in near lockstep, confirmed by the strength of the rolling five-day correlation coefficient in the middle pane. From top to bottom, it shows pricing for Fed rate cuts out to December 2026, two- and ten-year Treasury yields, Nasdaq futures and VIX futures, with the right-hand pane showing monthly correlation scores for the same markets.
Source: TradingView
While the once strong link between USD/JPY and U.S. stock futures or implied volatility has flipped—showing risk appetite has not been driving the pair recently—the relationship with the U.S. rate curve has strengthened sharply, producing correlation readings from -0.82 to as high as 0.93 over the past week, strongest with ten-year yields. The relationship hasn’t been as firm over the past month, but it has been strengthening, placing even greater emphasis on events that could shift the U.S. rate outlook for anyone trading USD/JPY.


ISM, ADP, Refunding Key U.S. Events
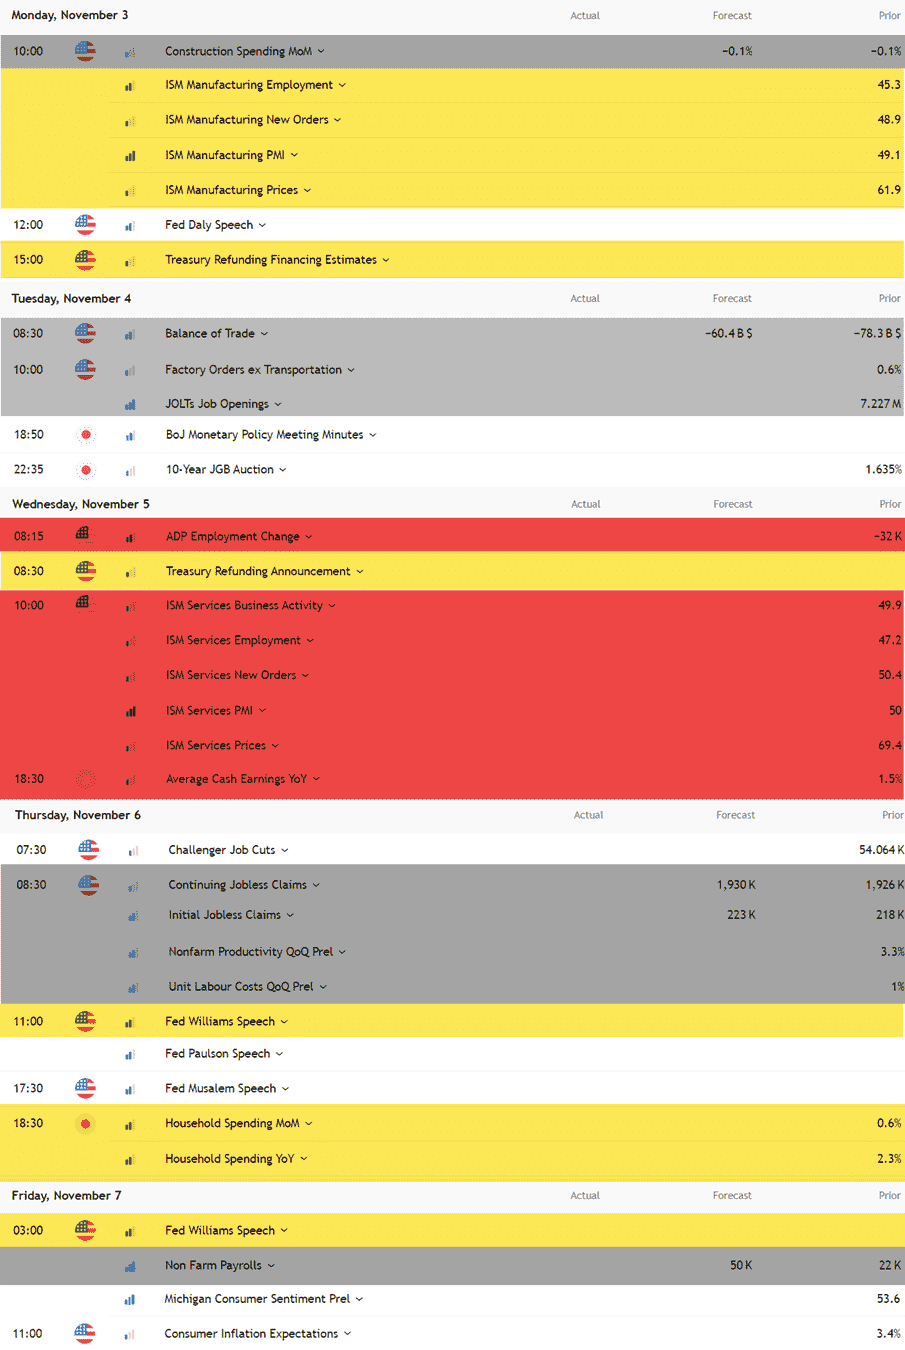
With the U.S. government shutdown still unresolved, markets are again being starved of key data, including a swathe of jobs figures that were due this week such as October non-farm payrolls. In their absence, traders will turn to private surveys and speeches from Fed officials to guide direction. The calendar below has been colour-coded to highlight the most important risk events, with red-shaded items marking those with the highest potential to move USD/JPY.
Source: TradingView
Wednesday looms as the pivotal day, with the ADP National Employment Report and ISM services PMI both in the red category. While some question the reliability of ADP’s signal, it has generally been a decent lead indicator once the official figures are revised. The ISM services report—offering a near real-time view on activity, prices and orders in the largest part of the economy—now carries even greater weight with no official data available.
Events shaded in yellow may still spark volatility, including the ISM manufacturing PMI on Monday. Although manufacturing is a smaller part of the economy, this survey still draws attention, so keep an eye out for any sudden shifts in demand or prices. The Treasury’s quarterly refunding announcements on Monday and Wednesday also deserve close monitoring, given they include borrowing estimates for the current and next quarter along with the intended maturity mix of debt issuance. These details have influenced yields before, and with USD/JPY now so closely tied to the U.S. curve, this release is important.
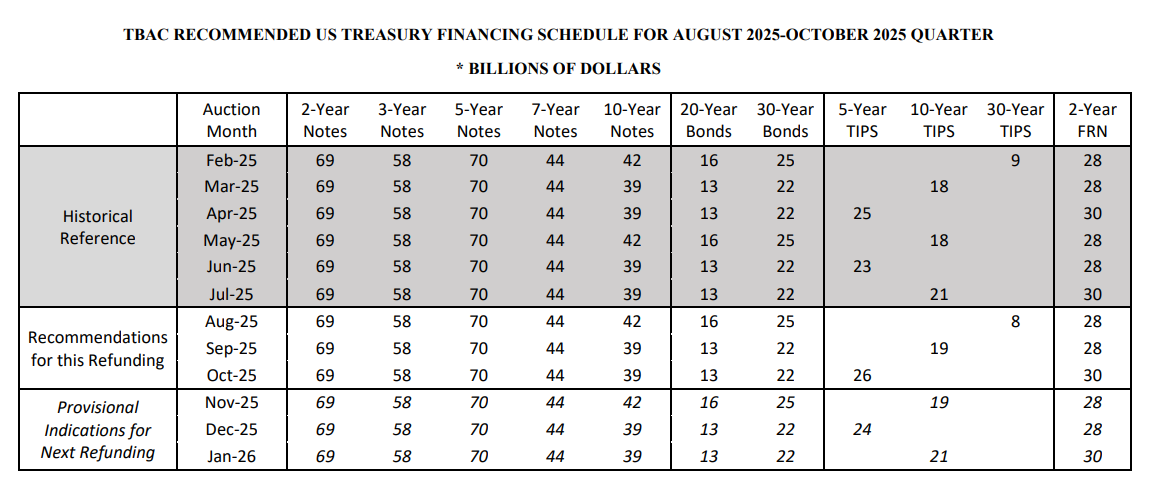
When Treasury last estimated borrowing needs for Q4, the figure stood at $590 billion. Keep that in mind with the shutdown ongoing. Details on issuance amounts and maturities arrive Wednesday. It seems unlikely Treasury will term out debt issuance given yields remain elevated—especially with the Fed’s quantitative tightening set to end in early December, when proceeds from maturing holdings will be reinvested into short-term debt. Expect a continued flood of Treasury bill issuance at the front of the curve. Details on prior debt issuance are found in the graphic below.
Source: U.S. Treasury
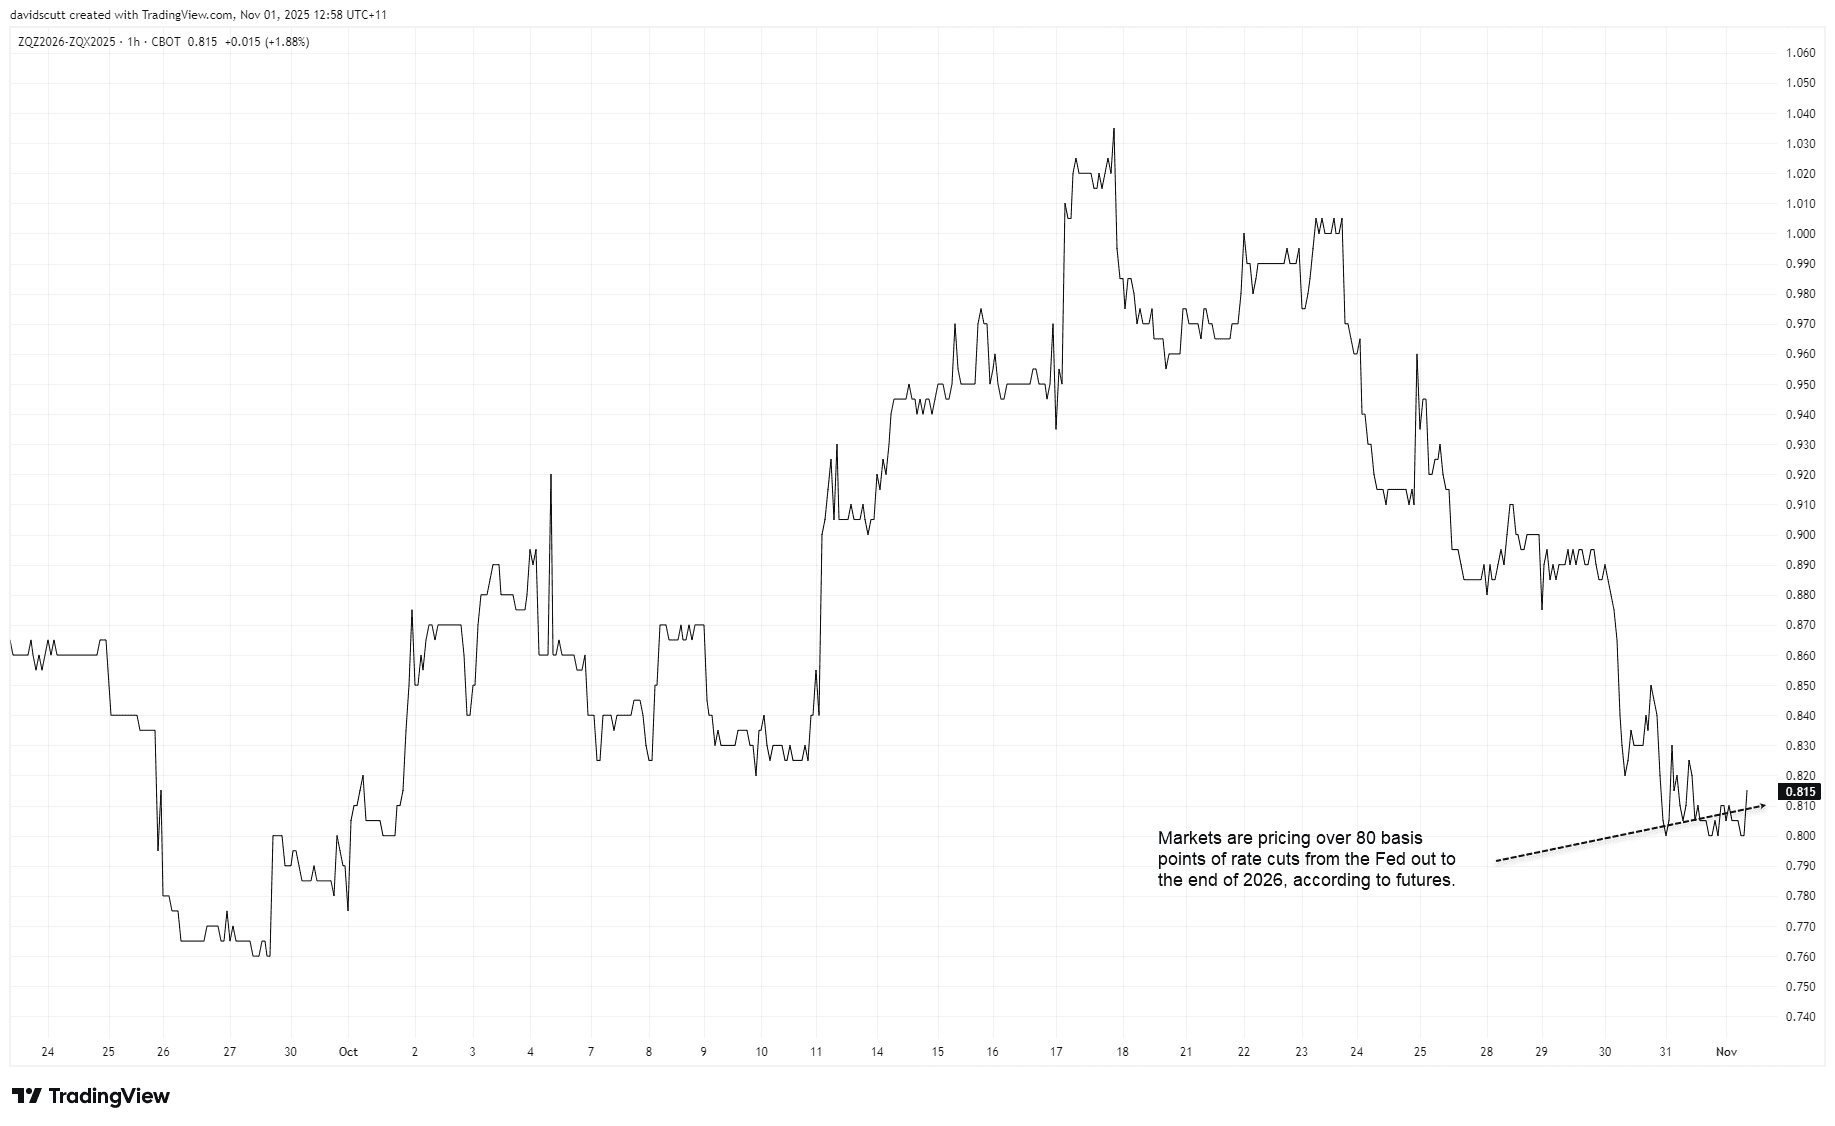
Beyond data and refunding updates, keep an ear out for comments from Fed officials, including influential New York president John Williams later in the week. Powell’s assertion that a December rate cut was “far from” a foregone conclusion suggests several FOMC members were not far off joining Kansas City’s Jeffrey Schmid in voting to keep rates unchanged in October. Any hint that policymakers are reluctant to deliver the more than 80 basis points of cuts priced by markets for next year could see yields lift across the curve—particularly if echoed by multiple members.
Source: TradingView
Japan Wages Data in Focus
In Japan, a few releases also warrant attention even if it’s the U.S. rate outlook that’s been steering USD/JPY. Wages data due Thursday will be key, with any sign of strengthening likely to raise the odds of a BOJ hike in December, especially after last week’s hotter Tokyo inflation print. Household spending data on Friday will also be watched closely, as the BOJ looks for evidence that domestic demand is improving, reducing spare capacity and supporting wage growth. As the largest component of Japan’s economy, consumption remains a vital piece of the puzzle.
USD/JPY: Bulls in Control
Source: TradingView
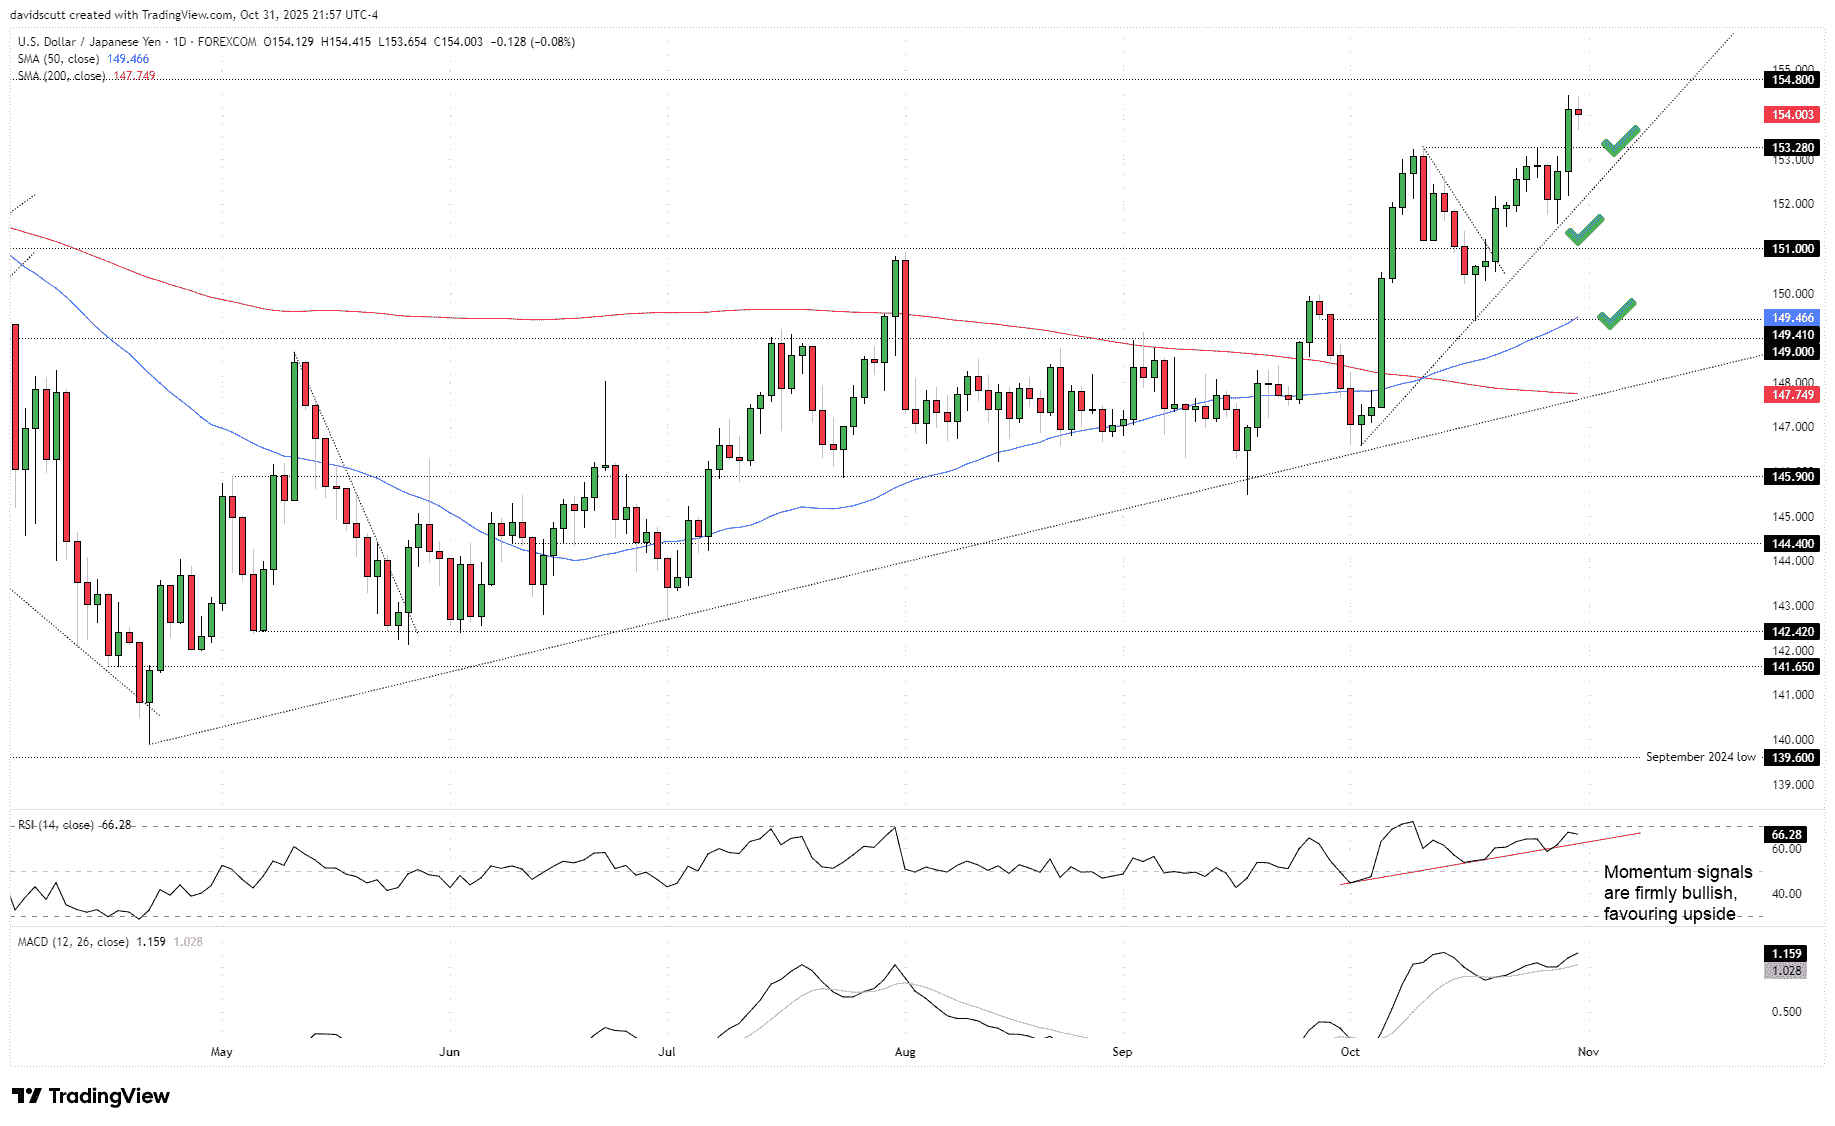
Sitting in an established uptrend with momentum indicators continuing to generate bullish signals, the preference remains to continue buying dips and bullish breaks in USD/JPY as we approach the new week.
There’s not much to dislike for bulls on the daily chart, with the pair breaking out above 153.28 resistance late last week, helped by dovish commentary from BOJ Governor Ueda. That level may now flip to provide support. Having twice bounced off the uptrend running from the October 2 lows, that trendline has been validated as support, providing two potential zones for bulls to establish fresh long positions should the price pull back towards either.
With the pair now firmly above the 200-day moving average and its 50-day equivalent sloping higher, the case remains stronger for upside than downside. The RSI (14) continues to trend higher above 50, pointing to building topside pressure, while MACD confirmed the signal with a bullish crossover late last month. None of these signals rules out near-term downside, but the broader message remains bullish for now.
Resistance levels sit at 154.45, 154.80, 156.50 and 158.88, with support at 153.28, the October uptrend and 151.00 below.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?
GBP/USD, GBP/AUD: Sterling Rally Faces a BoE Reality Check
Sterling faces a reality check as the BoE prepares to hike rates. GBP/USD and GBP/AUD approach resistance, leaving bulls vulnerable to dovish guidance.

Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.