


Japanese Yen Outlook: Firmer CPI Fails to Lift JPY
Japan CPI strengthened the case for a September BOJ hike, yet the yen remains weak as traders weigh intervention, yields and higher oil prices.
Share this:
Japan’s latest CPI report strengthened the case for another BOJ rate hike in September, yet the yen weakened across the FX majors following the release. With a hike already largely priced in, traders appear more focused on whether the BOJ accelerates tightening, while intervention risk, US yields and higher oil prices add to an increasingly complicated backdrop for JPY.
View related analysis:
View related analysis:
Japanese Yen Weakens Despite Firmer CPI and BOJ Hike Bets
Japan Inflation Keeps BOJ September Hike in Play
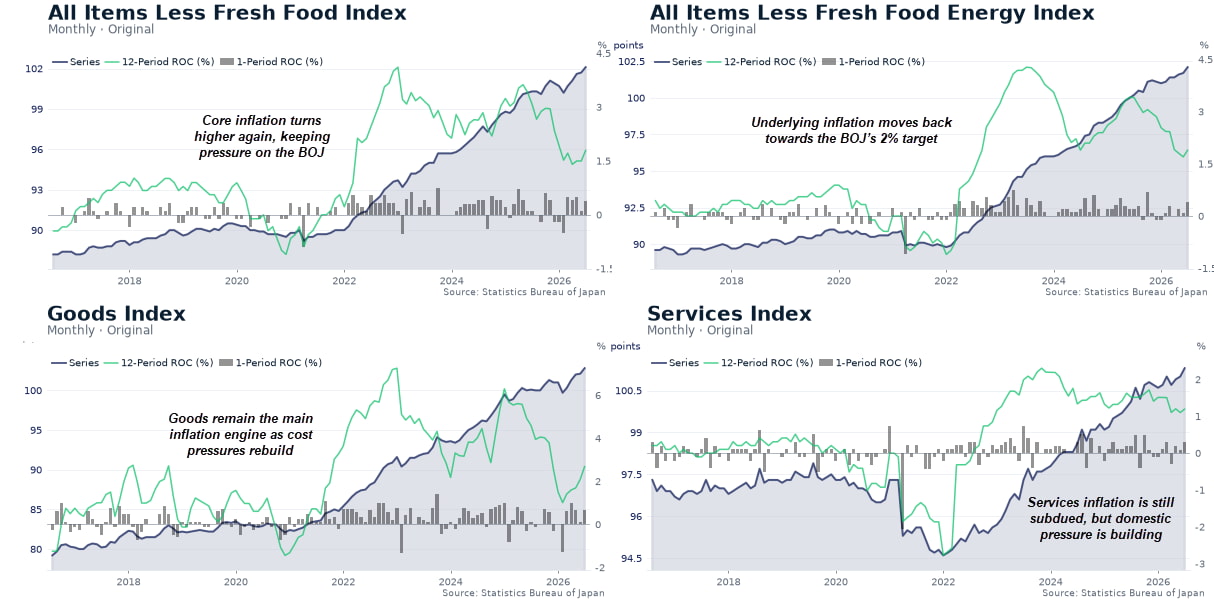
Japan’s latest inflation data strengthened the case for another Bank of Japan rate hike in September, with core CPI excluding fresh food rising 1.8% year on year in July from 1.6%, while the measure excluding both fresh food and energy accelerated to 1.9%.
The breakdown shows goods prices are still doing much of the heavy lifting, rising 2.7% as the weak yen, higher commodity prices and imported costs feed through to consumers. Services inflation also edged higher to 1.2%, which is more important for the BOJ as it points to firms gradually passing higher labour costs on to consumers.
Source: Statistics Bureau of Japan, Reuters
- Core CPI rose 1.8% YoY in July, up from 1.6% in June and in line with expectations.
- Underlying CPI excluding fresh food and energy accelerated to 1.9%, moving closer to the BOJ’s 2% target.
- Goods inflation led at 2.7%, showing imported costs, the weak yen and higher commodity prices are still doing much of the work.
- Services inflation edged up to 1.2%, a modest but important sign that domestic wage pressures are gradually feeding into prices.
BOJ September Hike Becomes the Base Case
A September hike to 1.25% is increasingly becoming the base case, while the bigger question for yen traders is whether persistent inflation and yen weakness force the BOJ to accelerate its tightening cycle beyond September.
While a September hike may seem like a bullish cue for the yen, the BOJ’s gradual tightening alone may not be enough to back a stronger currency. Besides, the bigger shift has already come from joint US-Japan intervention, which has made it considerably more dangerous for traders to aggressively rebuild yen shorts. With Washington signalling it could support Japan again, further BOJ tightening would add another layer of support rather than carry the burden alone.
Yen Shrugs Off Firmer CPI as BOJ Hike Bets Build
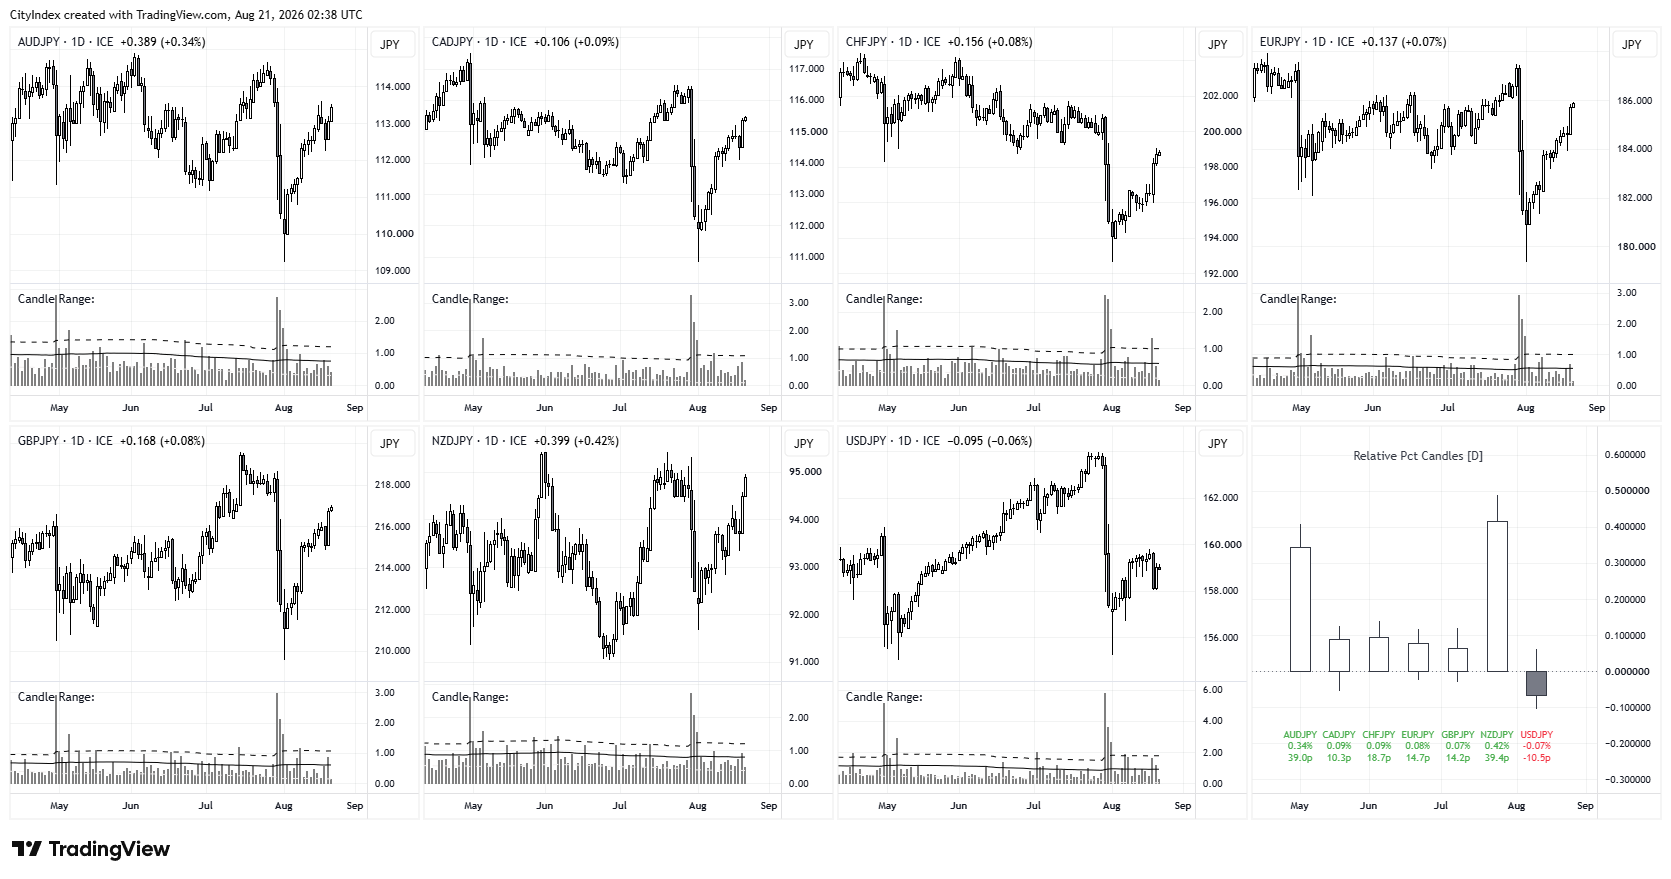
The Japanese yen was a touch lower across the board after the latest CPI figures were released, suggesting the data did little to materially change a policy outlook where a September hike is already largely priced in.
But the fact that the yen continues to weaken despite the US and Japan joining forces on intervention suggests yen bears may be rolling the dice — or goading the powers that be back into action. GBP/JPY, EUR/JPY, CHF/JPY, CAD/JPY and NZD/JPY sit at three-week highs, while AUD/JPY remains beneath Monday’s shooting star high.
USD/JPY fell sharply on Wednesday after the US Treasury stepped in to support the bond market as the 30-year yield broke above 5.3%. Yet bond traders are putting up a bit of a fight, with renewed selling sending the 30-year yield back above 5.2% on Thursday and helping USD/JPY recoup around two-thirds of Wednesday’s losses.
Source: ICE, TradingView
Higher Oil and JGB Yields Complicate the Yen Outlook
Higher oil prices are adding another complication for yen traders. Crude jumped around $2 overnight as Middle East tensions intensified, helping push Japanese bond yields higher as inflation concerns resurfaced. The 10-year JGB yield rose 3bp to 2.875%, while the 30-year climbed 5.5bp to 4.06%. Higher Japanese yields should theoretically lend the yen some support, but rising energy costs are also a headwind for an economy heavily reliant on imported fuel, leaving the currency caught between tighter BOJ expectations and a deteriorating terms-of-trade backdrop.
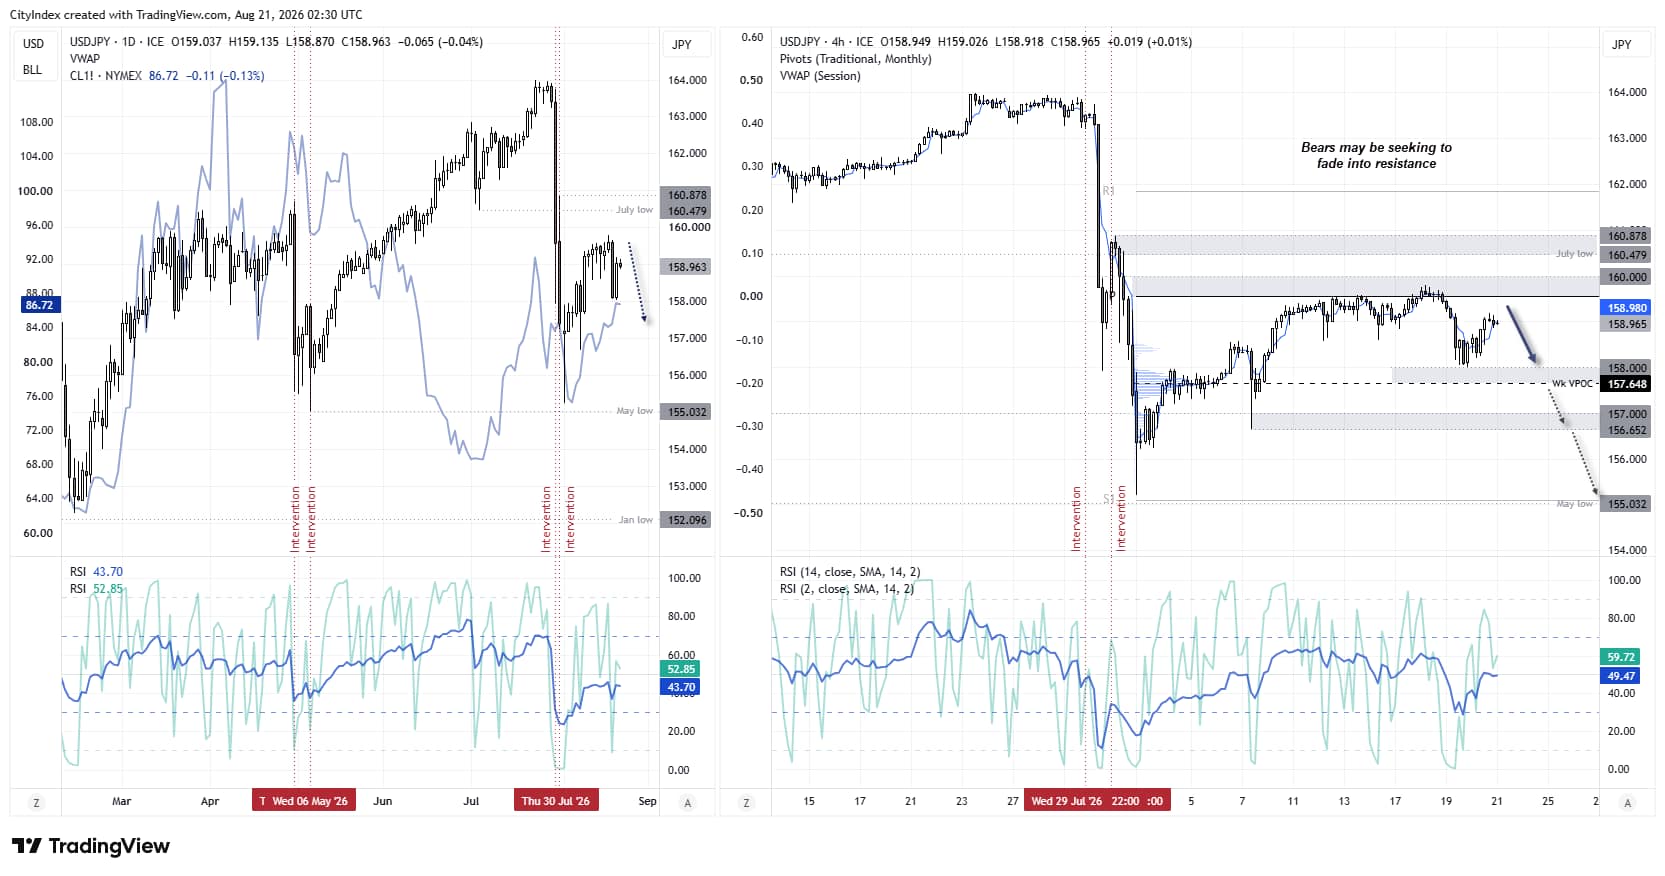
Source: ICE, TradingView
USD/JPY Outlook: Summary
- Japan CPI strengthened the case for a September BOJ hike, but much of that move is already priced in.
- The yen remains weak despite firmer inflation and joint US-Japan intervention, suggesting traders are still willing to test policymakers.
- Higher US yields continue to support USD/JPY, while rising JGB yields provide only limited offset.
- Higher oil prices complicate the picture by lifting Japanese inflation expectations while worsening the terms-of-trade backdrop for the yen.
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Blue wave adds to Nikkei’s AI troubles
The Nikkei 225 has taken another beating as a Democratic sweep adds to concerns about AI investment returns. But after the scale of the earlier declines, how much bad news is already priced in?
AUD/USD Remains Vulnerable Despite US Dollar Weakness Amid Midterms
AUD/USD struggles despite a weaker US dollar and falling Treasury yields, as Democratic sweep expectations fuel volatility and Wall Street risk aversion.
US dollar outlook: Nasdaq breakdown raises stakes for EUR/USD, USD/JPY
A potential Democratic sweep of Congress is adding to the AI trade's headaches, with Nasdaq 100 futures breaking below a major technical level. The implications for the dollar could be significant.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.