



Nasdaq 100 Forecast: “Magnificent Seven” Q2 2025 Earnings Preview
The Nasdaq 100 remains in a bullish channel and could target 24,000 or 25,000 if Big Tech stocks can deliver on earnings expectations.
Share this:
Nasdaq 100 Key Points
- With over $400B in AI and datacenter investments projected this year, the Magnificent Seven continue to drive the digital infrastructure boom…though any cap-ex slowdown could spark a sharp rerating.
- Despite pockets of consumer weakness, especially for Apple and Tesla, enterprise tech spending and digital advertising remain robust, setting the stage for another bifurcated earnings season.
- The Nasdaq 100 remains in a bullish channel and could target 24,000 or 25,000 if Big Tech stocks can deliver on earnings expectations.
Magnificent Seven Earnings Preview – MSFT, AAPL, GOOG, AMZN, NVDA, META, TSLA
Throughout most of the last few years, the “Magnificent Seven” big technology stocks (Microsoft, Apple, Nvidia, Alphabet/Google, Meta/Facebook, and Tesla) broadly moved as a monolithic unit, rising and falling in unison with the (mostly) ups and (fewer) downs of the broader market, albeit to differing extents
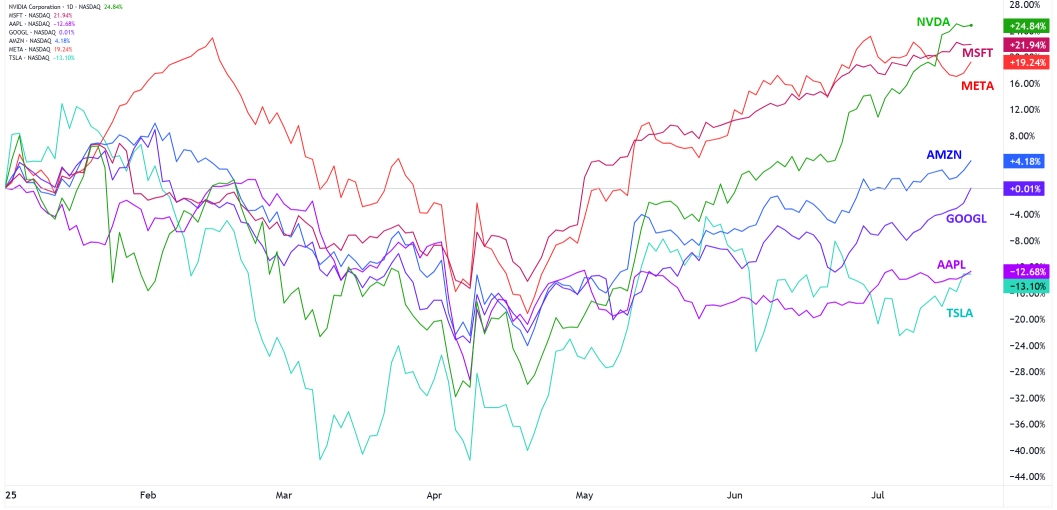
Since flipping the calendar to 2025, the individual differences between these massive entities have become more stark, with growth laggards like Apple and Tesla falling despite generally bullish conditions and standouts like Nvidia and Microsoft gaining more than 20% year-to-date:
 Source: StoneX, TradingView
Each of the Magnificent Seven stocks faces its own set of opportunities and challenges, but some common themes to monitor are the health of the consumer and timing of any interest rate cuts from the Federal Reserve, as well as the impact of AI and growth of augmented/virtual reality devices.
Magnificent 7 Earnings “Cheat Sheet”
|
COMPANY |
Report date / time |
CONSENSUS EPS ESTIMATE* |
Y/Y REVENUE DRIVERS |
TOP ISSUES |
|
Tesla (TSLA) |
Wed 23 Jul after - close |
$0.44 |
-13% unit vols, weaker price/mix |
Auto-gross-margin trough? ˑ Robo-taxi roadmap ˑ China demand & tariffs |
|
Alphabet (GOOGL) |
Wed 23 Jul after - close |
$2.17 |
Search & YouTube ads + low-teens Cloud |
Gen-AI search monetisation ˑ TAC inflation ˑ EU DMA impact |
|
Microsoft (MSFT) |
Wed 30 Jul after - close |
$3.38 |
Azure +13% cc, O365 +11% |
AI-attached Azure growth, Copilot seat uptake, Activision synergies |
|
Meta (META) |
Wed 30 Jul after - close |
$5.84 |
Re-accelerating ad spend (retail & gaming) |
AI-inference cap-ex ($35-40 bn run-rate) ˑ Reels monetisation |
|
Amazon (AMZN) |
Thu 31 Jul after - close |
$1.31 |
AWS +23%, Retail +8% |
Gen-AI services attach, ad-net high-teens growth, fulfilment cost leverage |
|
Apple (AAPL) |
Thu 31 Jul after - close |
$1.42 |
iPhone rebound in China, Services +12% |
Gross-margin slip from discounting, visionOS / “Apple Intelligence” clues |
|
NVIDIA (NVDA) |
Wed 27 Aug after - close |
$1.00 (post-split†) |
Data-centre +80%, gaming normalises |
Supply vs. Blackwell demand; China export licences; buy-back cadence |
*EPS consensus = current Zacks/FactSet or equivalent public-source average unless otherwise noted.
†10-for-1 split effective 9 Jun 2025.
Key Magnificent Seven Themes to Watch This Earnings Season
- AI Infrastructure Tidal Wave
Wall Street’s biggest storyline remains the sheer scale-up in datacenter spending. Bank of America now projects the four “hyperscalers” (Amazon Web Services (AWS), Microsoft Azure, Google Cloud Platform (under Alphabet/Google) and Meta Platforms) will plough about $414 billion into AI and general datacenter cap-ex in 2025, rising to roughly $432 billion in 2026—double the 2023 run-rate. Gartner’s fresh IT-budget survey corroborates the trend, flagging a 42% jump in datacenter outlays next year, far outpacing every other line-item in corporate tech budgets.
With Nvidia still effectively sold-out through its Blackwell cycle and AMD, Broadcom and TSMC signalling back-end bottlenecks well into 2026, any management hints of a “pause” in rack installs could ricochet across the entire Mag-7 narrative.
- Ad Market Resilience Amidst Macroeconomic Wobbles
Advertising demand continues to shrug off the stop-start economy. GroupM estimates that global ad revenue will surpass the $1 trillion mark this year and grow another 7.7% in 2025, with digital formats capturing nearly three-quarters of the total.
The combination of AI-driven targeting tools, retail-media momentum and Shorts/Reels video inventory is letting the platforms raise impressions even as some brands edge budgets lower. Investors will therefore focus less on Q2 prints and more on color around Q4 holiday bookings, where any abrupt pull-back could force the first material guidance resets in six quarters.
- Consumer Wallets vs. Enterprise War Chests
The gap between household and corporate spending power is becoming glaring. In China, a bellwether for discretionary tech demand, iPhone shipments fell 9% year-on-year in Q1 2025, making Apple the only top five vendor to shrink in the world’s second-largest smartphone market.
On the auto side, Tesla’s automotive gross margin has already slid from 16% in early 2024 to about 13.6% in Q4, with UBS warning it could sink near 10% in Q1 2025 as price cuts persist. By contrast, CIOs keep the checkbook open: Gartner forecasts overall IT spending to climb by 7.9% in 2025, propelled largely by AI-optimized infrastructure budgets.
Expect earnings calls to paint a bifurcated picture—consumer-facing names defending volumes and discounting, while enterprise-exposed cloud providers boast healthy double-digit growth.
- Policy & Regulation Watch
The legal and political backdrop is as busy as the P&L sheets. The Department of Justice has moved into the remedies phase of its search-antitrust win against Google, signaling possible structural changes to how the company bundles advertising and search services. In Europe, Apple is appealing a €500 million fine under the Digital Markets Act even as it tweaks App-Store commission rules—investors will parse any further concession language.
Across the Atlantic, a federal judge last week postponed Texas’s $100 billion ad-tech case against Google until a related Virginia verdict is final, potentially pushing headline risk into 2026.
On the trade front, Nvidia is rolling out export-compliant H20 and RTX 6000D GPUs to keep Chinese revenues flowing amid shifting US licensing rules, underscoring how supply-chain workarounds are now part of the earnings script.
Finally, Washington’s 100% tariff on Chinese EV imports remains a wildcard for Tesla and, indirectly, Apple’s China-centric supply chain if retaliatory measures materialize later this year.
Nasdaq 100 Technical Analysis – NDX Daily Chart
Source: TradingView, StoneX
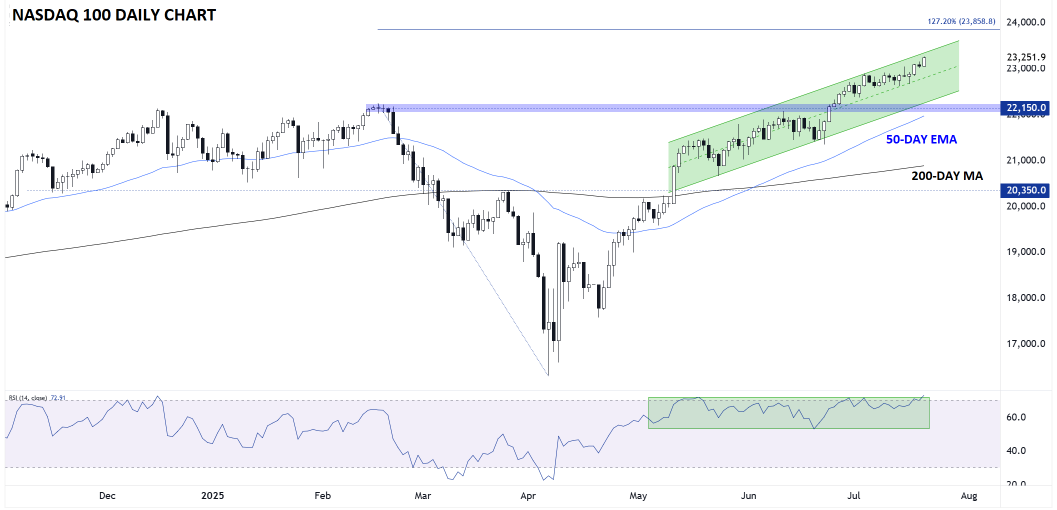
As the chart above shows, the Nasdaq 100 has more than recovered from its Q1 swoon to trade at fresh record highs, despite the mixed performance of the technology behemoths so far this year.
More immediately, the index is trending consistently higher within a bullish channel, keeping the technical bias tilted toward the topside as long as this season’s earnings results at least meet analyst expectations. To the topside, the next level of resistance to watch is the 127% Fibonacci extension of the Q1 drop near 24,000, followed by the round 25,000 handle after that.
However, if weak earnings reports start to accumulate and the index breaks down from its channel to fall below the 50-day EMA, a deeper retracement toward the 200-day MA near 21,000 could be in the cards.
-- Written by Matt Weller, Global Head of Research
Follow Matt on Twitter: @MWellerFX
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.