



NZD/USD Forecast: China tariff shift adds twist to outlook
The US Supreme Court ruling has shifted China’s tariff backdrop just as New Zealand retail spending surprises again. With NZD/USD consolidating near key levels, CNH is back on the radar.
Share this:
- New Zealand retail spending surprises to the upside
- US Supreme Court ruling shifts China tariff backdrop
- CNH back on the watchlist for Kiwi traders
Summary
New Zealand’s household sector continues to impress, even before the economy feels anything close to the full impact of the RBNZ’s 325bps easing cycle. If that resilience proves broader, it keeps the prospect of an earlier policy pivot from the RBNZ firmly in play.
Externally, the US Supreme Court ruling last Friday has complicated the tariff narrative, ultimately lowering China’s average tariff burden despite the announcement of a fresh 15% global levy. Given China’s importance to the New Zealand economy, that shift may carry more constructive implications for the Kiwi than headlines alone suggest.
Discretionary strength signals demand recovery
Source: StatsNZ
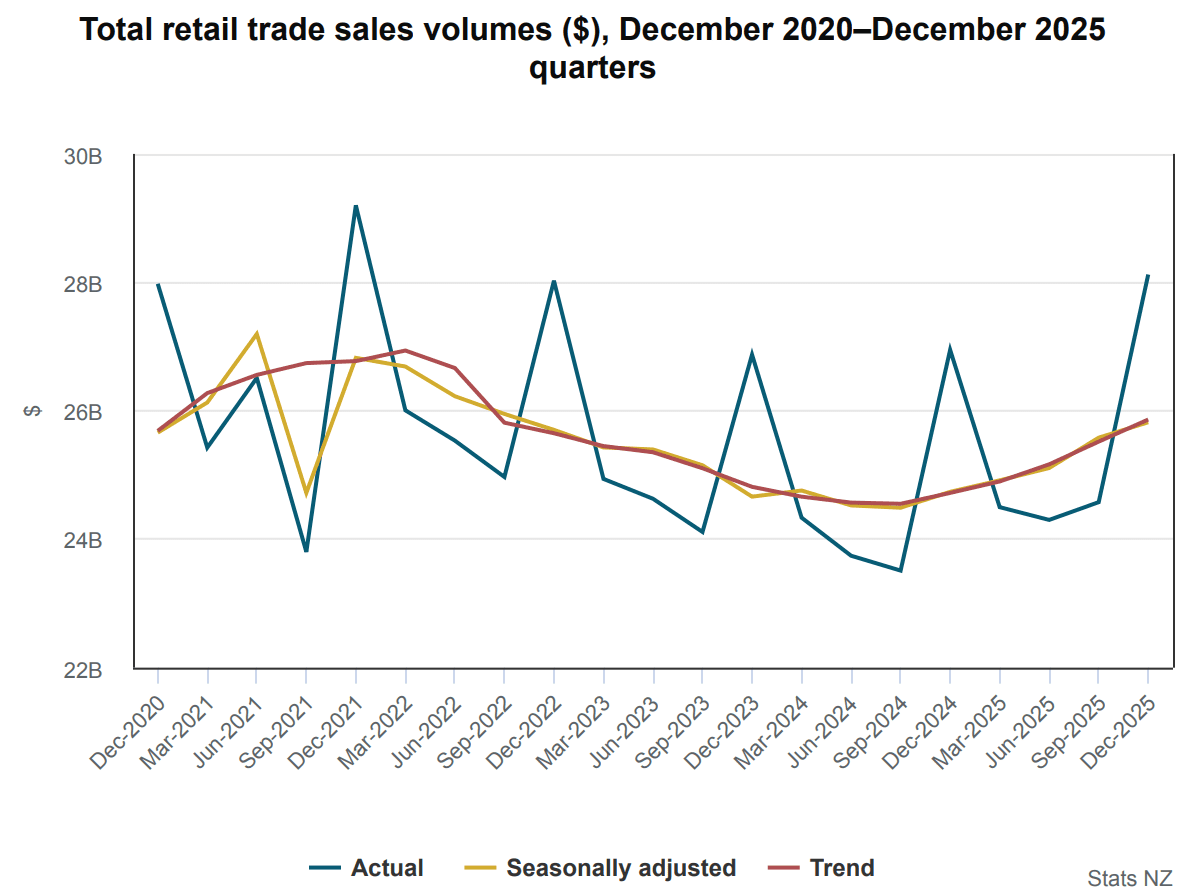
New Zealand retail sales surprised to the upside again in Q4, with volumes rising 0.9% against expectations closer to 0.6%. That marked a fifth consecutive quarter of gains, leaving the volume of goods sold more than 4% higher than a year ago. Nominal spending remained firm too, climbing 1.4% over the quarter and nearly 5% annually, reinforcing that households are buying more, not simply paying higher prices.
The composition of growth tells the more important story. Discretionary categories drove the strength, including electronics, furniture, hardware, clothing and recreational goods, areas typically most responsive to shifts in interest rate dynamics. Hospitality spending also continued to expand.
Earlier RBNZ tightening risks creep back
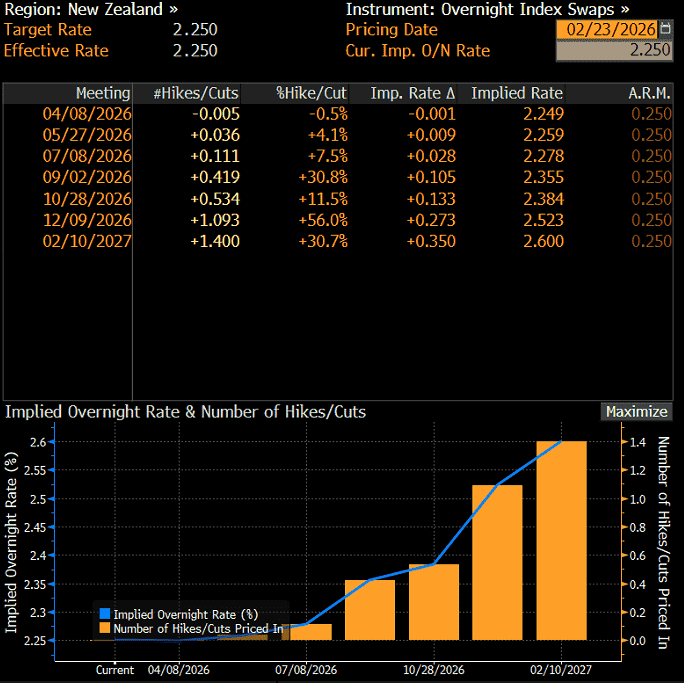
While few would dispute that ample slack remains within New Zealand’s labour market, something that should help contain wage and domestic price pressures near term, the policy outlook becomes less straightforward if household demand continues to strengthen as fixed-rate mortgages progressively roll into a far lower interest rate environment. Should that trend persist, the RBNZ may find itself leaning towards tightening earlier than the Q4 timing flagged in last week’s updated rate track.
Source: Bloomberg
Swaps traders remain reluctant to fully price a hike ahead of the general election in early November. Even so, expectations for an earlier move are quietly building, with October currently priced a little above 50%. That timing sits awkwardly close to the election, leaving September as the more realistic candidate should incoming data continue to surprise on the upside.
China adjustment carries Kiwi implications
Externally, the US Supreme Court ruling last Friday has added an interesting twist to the China narrative. While Donald Trump announced a fresh 15% global tariff over the weekend, the broader effect of the ruling is a reduction in China’s average tariff burden compared to the structure previously in place. Given China remains the world’s largest export engine, even marginal shifts in its trade environment carry global implications.
For New Zealand, that adjustment matters. China is easily the country’s largest trading partner, meaning any stabilisation or improvement in Chinese activity has direct spillover effects for growth, sentiment and the currency. While tariff uncertainty may still inject bouts of volatility into broader risk assets, the underlying impulse from a potentially less restrictive China backdrop may prove less negative for the Kiwi than headlines alone might suggest.
Yuan back on the Kiwi watchlist
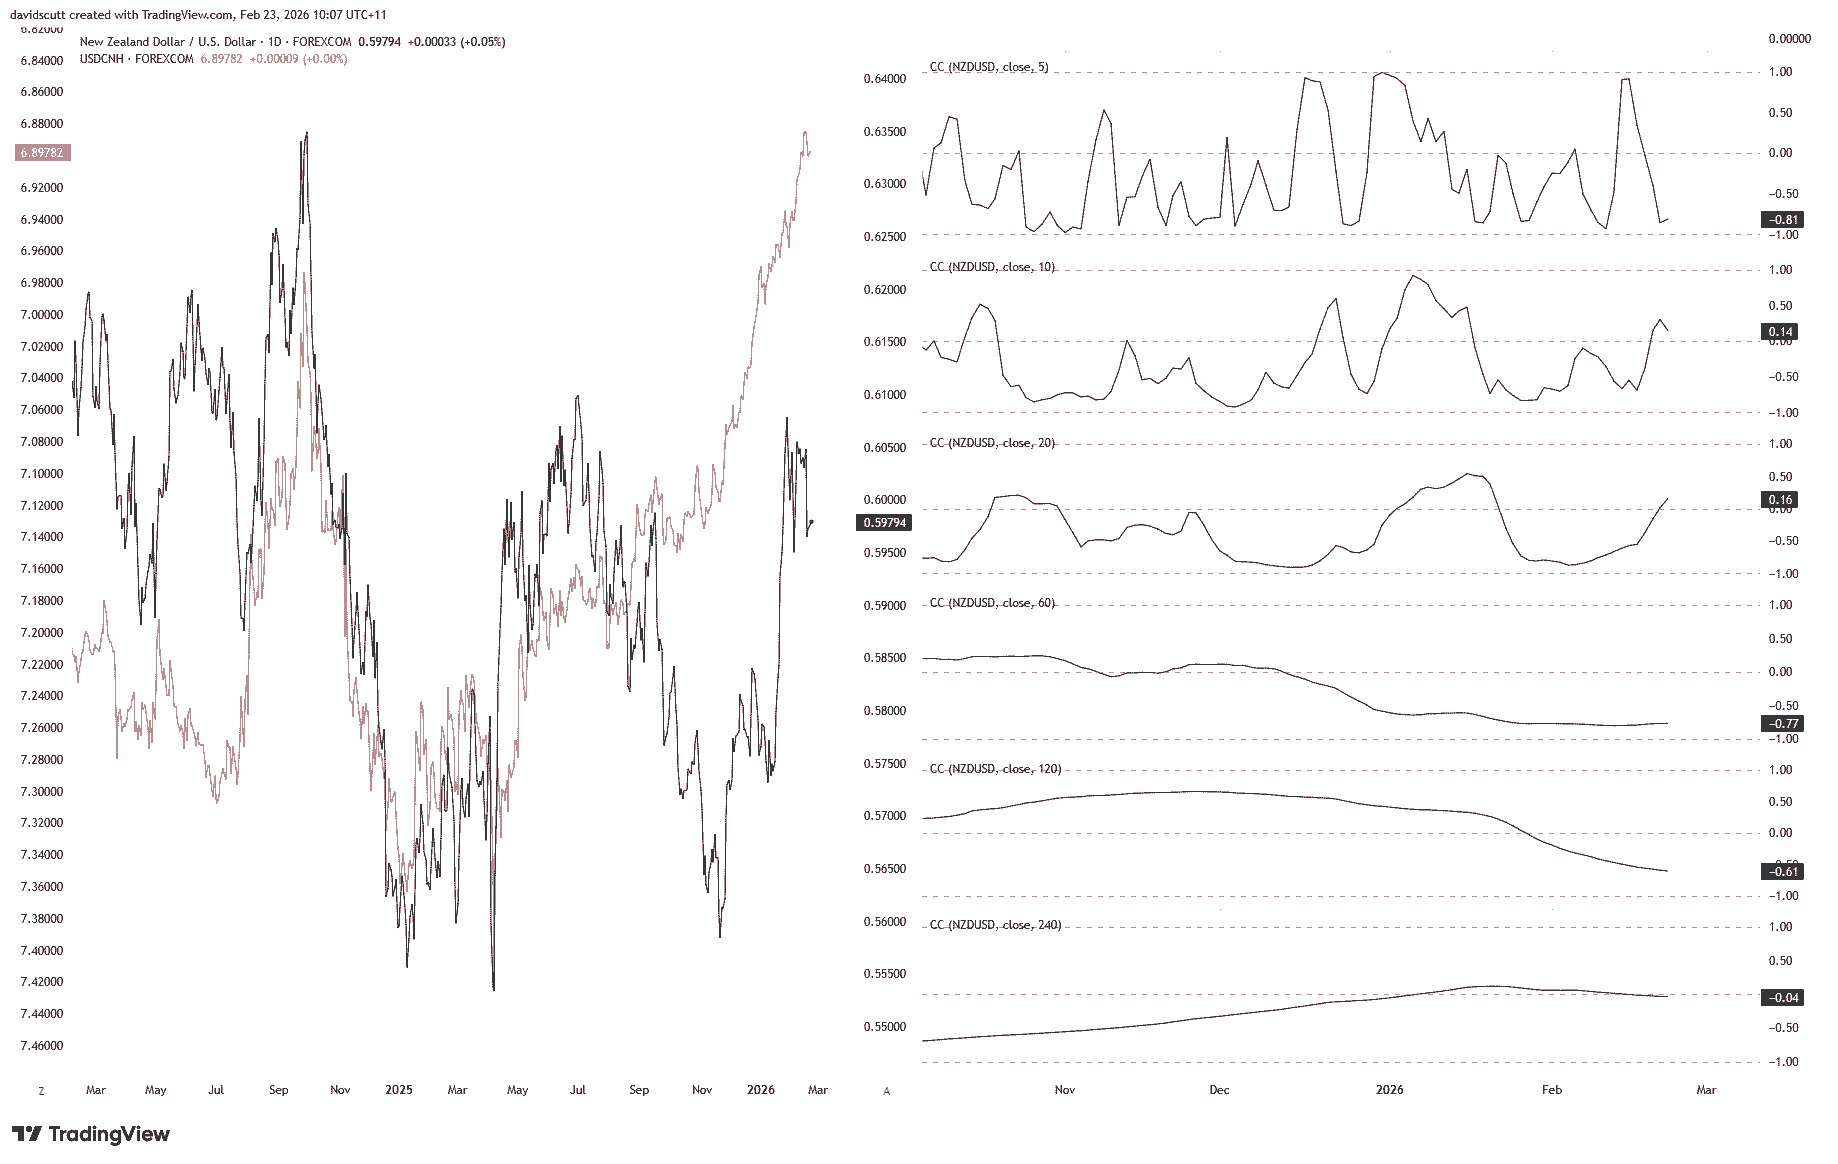
The chart below highlights the shifting relationship between NZD/USD and USD/CNH over time. In the left pane, NZD/USD is shown in black overlaid against USD/CNH in light red, with the scale of the latter inverted to provide a clearer read on relative performance against the US dollar. While the visual co-movement is often apparent, the correlation profile on the right tells a more nuanced story.
Source: TradingView
At times, the relationship tightens meaningfully, with negative correlations emerging that imply both currencies are moving in a similar direction against the dollar. In other periods, however, the linkage fades, offering little reliable signal. For traders, the takeaway is straightforward. Yuan performance deserves a place on the watchlist as a guide to directional risks for the Kiwi, but it should not be treated as a mechanical trading signal.
Kiwi finds buyers on dips
We can see in Asia trade that the US dollar is back on the defensive, extending the selling pressure that emerged late Friday following the tariff ruling. As seen in April last year after Liberation Day, abrupt shifts in US trade policy have again been met with dollar selling, hinting at the risk of renewed capital flows out of USD assets. With prior tariffs ruled illegal, the broader question for markets is why the rest of the world should simply accept the revised measures.
Source: TradingView
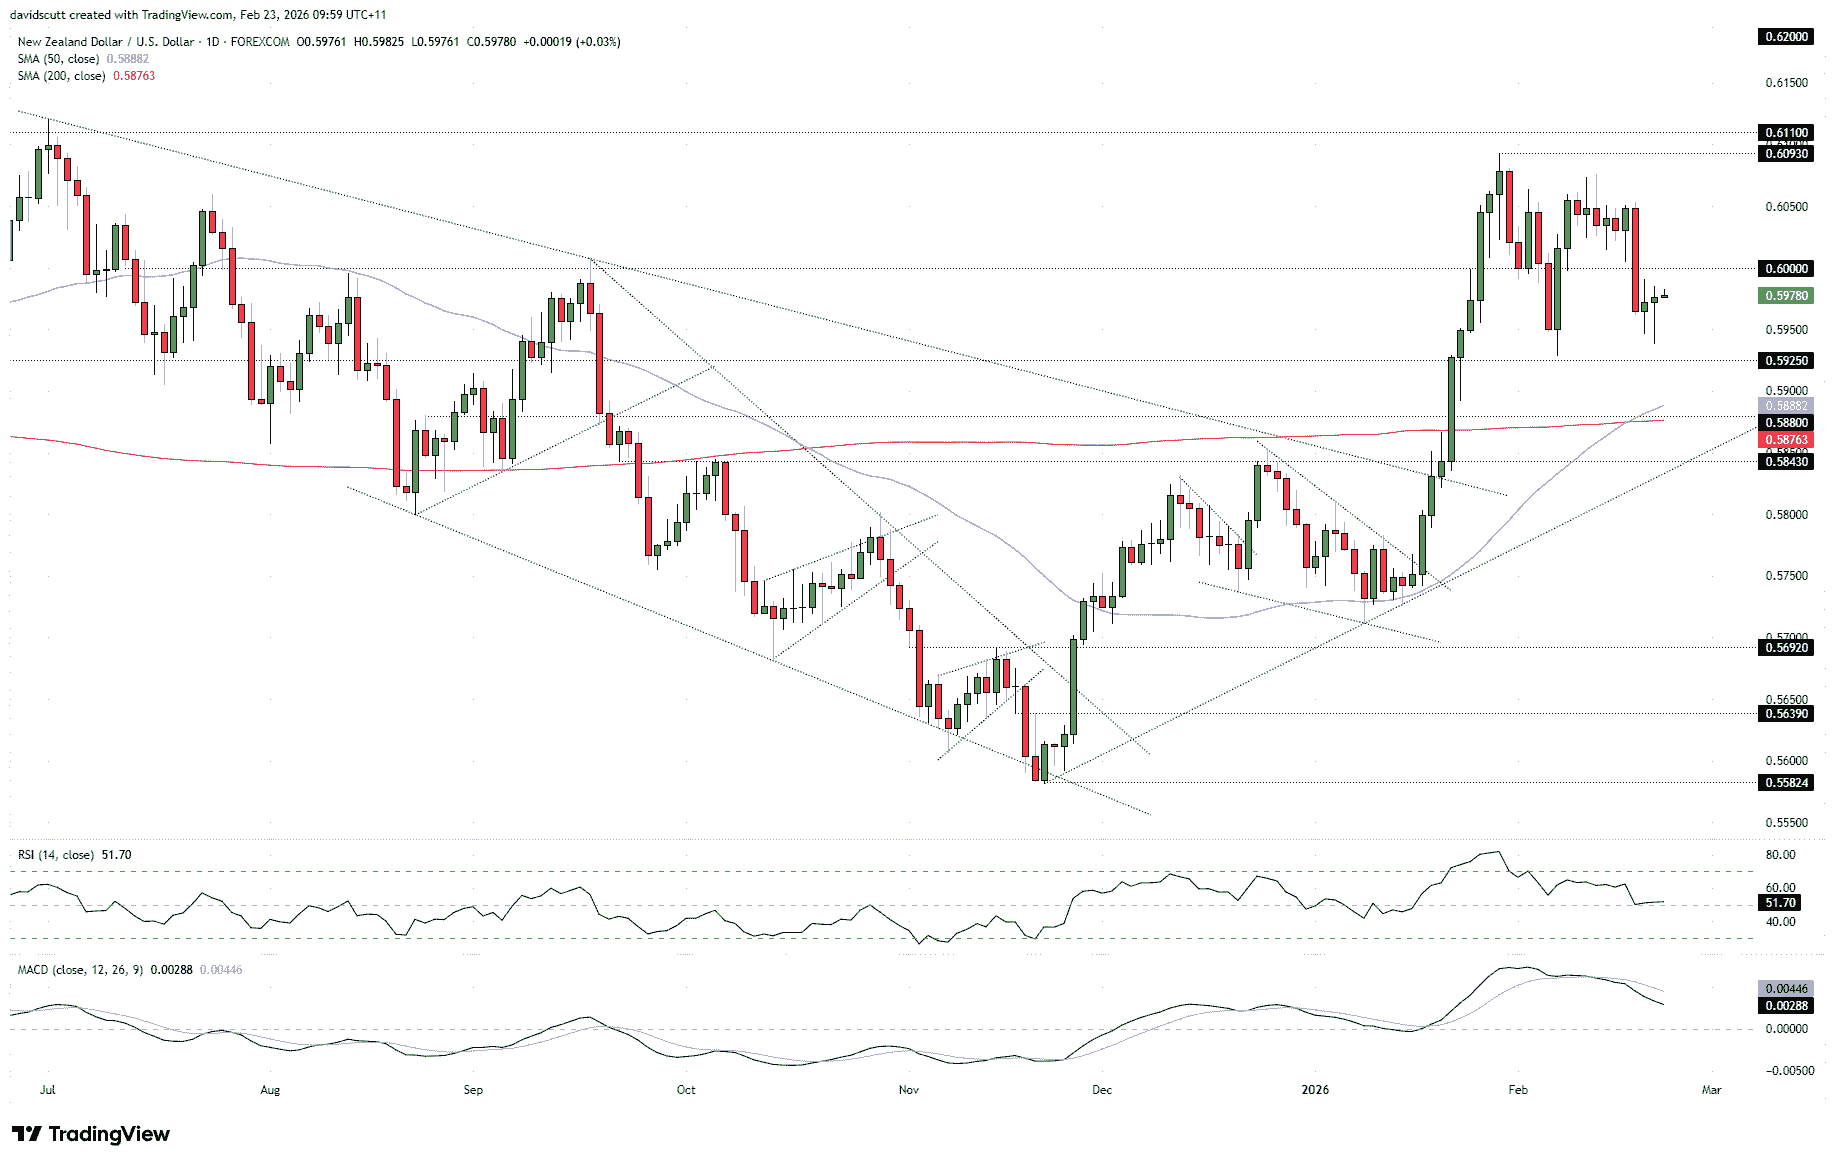
For NZD/USD, having drifted back towards the lower end of its recent sideways range following the RBNZ last week, the balance of risks may now be tilting higher. That view is consistent with the hammer candle printed on Friday, suggesting demand is emerging on dips. On the topside, attention remains on .6000 and .6093, the latter marking the January peak. On the downside, pullbacks beneath .5950 have regularly found buyers, with demand emerging ahead of .5925 support.
Given the increasingly headline-driven backdrop, less weight is being placed on oscillators for directional guidance, though RSI (14) and MACD are largely neutral anyway. Price action continues to resemble consolidation following the bullish breakout earlier this year rather than the start of a deeper retracement. With the pair still holding above both the 50 and 200DMA, the preference remains to buy dips for now. That bias would come under pressure on a sustained break beneath the key moving averages.
Related tags:

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Tankan Backs BOJ Tightening, but Yen Rate Expectations Ease
Japan’s Tankan supports further BOJ tightening, although softer rate expectations could limit support for the Japanese yen.


Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.