
S&P 500 Analysis: Earnings Uncertainty Continues to Weigh on the SPX
The trading week is coming to an end, and a phase of weakness remains evident across the S&P 500 in the short term. Recent price action reflects this dynamic, with SPX losing more than 2.00% over the last two trading sessions, bringing selling pressure back into focus.
Share this:
The trading week is coming to an end, and a phase of weakness remains evident across the S&P 500 in the short term. Recent price action reflects this dynamic, with SPX losing more than 2.00% over the last two trading sessions, bringing selling pressure back into focus.
Part of this weakness stems from recent earnings releases from some of the index's largest constituents, which have failed to generate a sustained sense of confidence among investors. At the same time, expectations that interest rates could remain elevated into year-end continue to weigh on sentiment. Together, these factors have limited risk appetite and could keep a cautious tone in place over the coming sessions.

Are Earnings Disappointing the Market?
This week was marked by earnings releases from several key companies within the S&P 500. Although some reports managed to beat expectations in certain areas, the broader market reaction has been driven more by concerns surrounding capital expenditures and the ability of these investments to translate into sustainable growth over the coming years.
At the beginning of the week, Microsoft reported revenue above $92 billion, exceeding expectations, while adjusted earnings per share came in near $4.90, above the expected $4.70. However, the market remains concerned about the pace of capital spending growth, and the stock has fallen close to 2.00% since the earnings release.
Later, Alphabet (Google) delivered a more visible slowdown. Earnings per share came in near $2.70, below the expected $3.00, while revenue reached approximately $127 billion, slightly below the $128 billion forecast by the market. In addition, continued growth in capital expenditures has raised concerns about the company's growth prospects for 2027. As a result, Alphabet shares have declined roughly 13.00% since reporting earnings.
Another relevant event was Amazon's earnings release, which also failed to meet expectations. The company reported earnings per share of $1.89 compared with forecasts of $1.96, while investors once again focused on the elevated pace of investment during the latest quarter, a dynamic that continues to pressure free cash flow. Since reporting earnings, Amazon shares have declined close to 2.00%.
The common theme across these reports is growing concern around capital expenditures within the technology sector. Investors are increasingly questioning when these large investments, particularly those linked to artificial intelligence and technological expansion, will begin translating into stronger revenue growth and profitability.
This concern is no longer limited to the companies that reported results. Looking at the recent performance of the Top 10 companies in the S&P 500, only Eli Lilly managed to post a gain of more than 3.1%, while the rest of the group recorded negative performance. This suggests that uncertainty is beginning to affect a broader portion of the technology sector and the index as a whole.
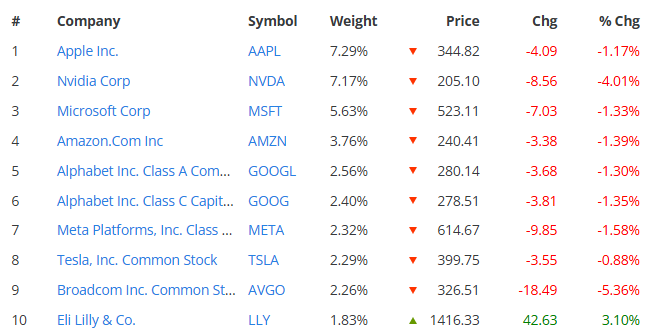
Source: Slickcharts
With all of this in mind, uncertainty has begun to play a more important role within the S&P 500. Concerns surrounding future corporate growth, particularly in light of rising investment spending, have reduced part of the confidence that supported markets in previous months and have limited the ability of major index components to attract consistent demand. As long as these concerns remain present throughout earnings season, selling pressure could continue to be relevant in the sessions ahead.
Is the Federal Reserve Still a Problem?
This week also featured the latest Federal Reserve policy decision. While the central bank left interest rates unchanged, officials reiterated that inflation remains an important concern and that there is still room to maintain a relatively restrictive monetary policy stance.
According to current market probabilities, there remains more than a 70% chance that the Fed could deliver an additional rate increase during the December 9 meeting, taking the benchmark rate toward 4.25%. This suggests that, despite the Fed's relatively cautious tone, the possibility of higher rates before the end of 2026 has not disappeared.
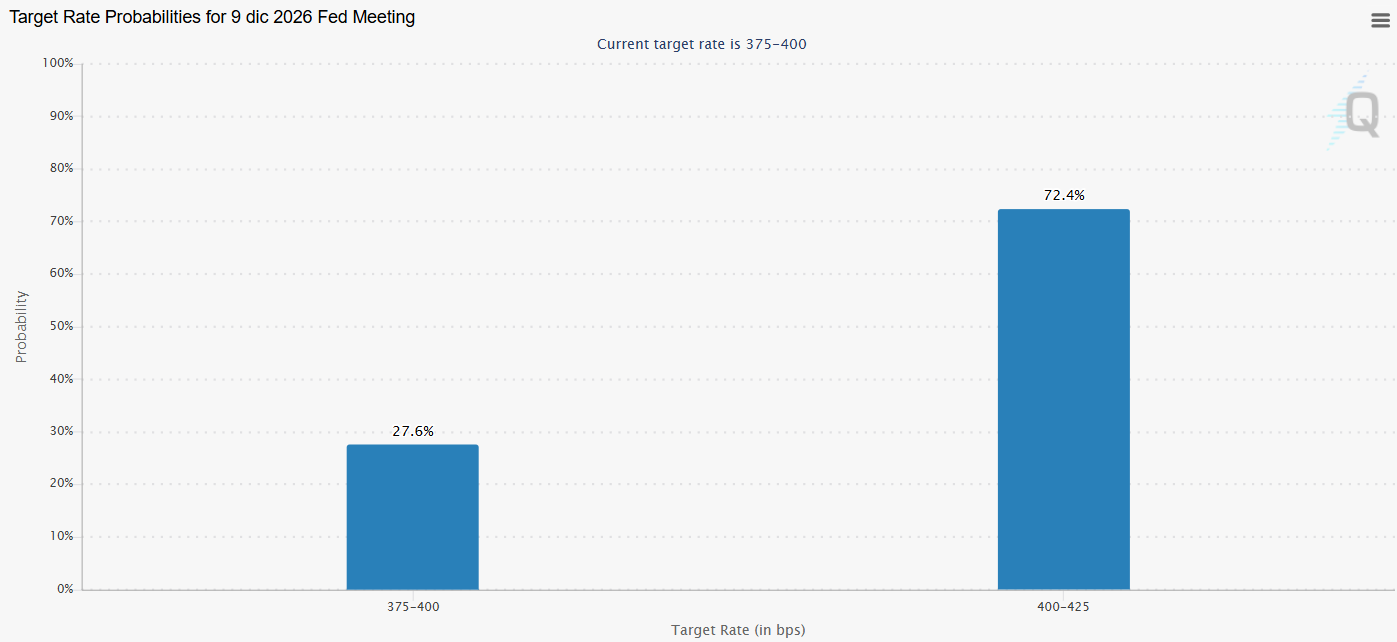
Source: CMEGROUP
This remains important because expectations of higher interest rates continue to represent a challenge for equity markets. A higher-rate environment can reduce liquidity, increase financing costs, and limit both consumer spending and corporate investment activity. It can also weigh on future growth expectations for companies within the index.
For this reason, as long as the market continues to price in the possibility of additional rate increases toward year-end, a cautious tone around risk assets could remain in place. Under this scenario, a Federal Reserve that keeps the door open to a more restrictive policy stance could continue limiting confidence and support a relatively weak environment for the S&P 500 over the longer term.
S&P 500 Technical Forecast
Source: StoneX, Tradingview
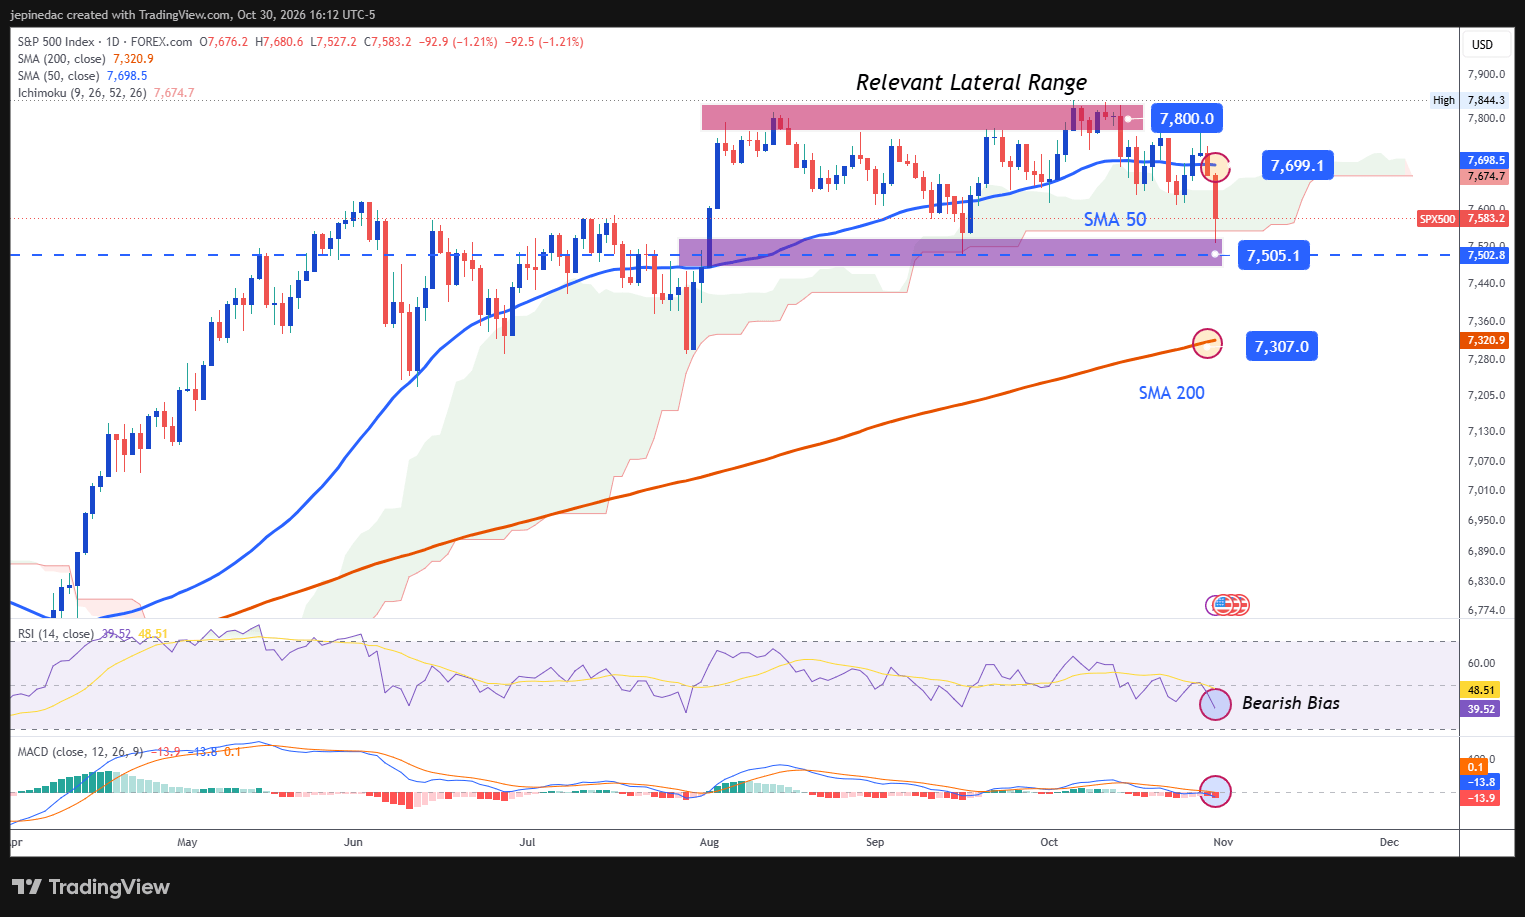
- Weakness begins to gain traction: Although the S&P 500 had been developing within a relatively stable trading range over recent weeks, the latest selling pressure has pushed the index closer to the lower boundary of that structure. If price action begins to break through key support levels, this could create room for a more established bearish phase in the weeks ahead.
- MACD: The MACD histogram continues to trade below the 0 neutral line, suggesting that selling pressure has begun to dominate short-term moving averages. As long as this behavior remains in place, the bearish bias could continue gaining relevance.
- RSI: The RSI also reflects weakness, as the indicator remains below the 50 neutral level. This suggests that selling momentum has once again become dominant and supports the possibility that downside pressure could remain relevant in the near term.
Key Levels:
- 7,800 points – Key Resistance: An all-time high area that represents the most important upside barrier on the chart. A return toward this level could reduce the relevance of the recent bearish move and restore confidence in the longer-term bullish structure observed in previous months.
- 7,700 points – Near-Term Barrier: A key equilibrium zone that aligns with the 50-period moving average. Price action returning toward this level could once again highlight a lack of direction and reinforce the trading range that currently dominates the chart.
- 7,500 points – Key Support: An important inflection zone that also develops below the Ichimoku Cloud, making it the most relevant downside barrier on the chart. Sustained price action below this level could confirm a more meaningful structural shift and open the door to a more consistent bearish trend in the weeks ahead.
Written by Julian Pineda, CFA, CMT – Market Analyst
Follow him on: @julianpineda25
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Analysis: Earnings Uncertainty Continues to Weigh on the SPX
The trading week is coming to an end, and a phase of weakness remains evident across the S&P 500 in the short term. Recent price action reflects this dynamic, with SPX losing more than 2.00% over the last two trading sessions, bringing selling pressure back into focus.
Nasdaq 100, S&P 500 Smashed as AI Bubble Fears Run Risk Aversion
It’s been a rocky few weeks for stocks starting with a bearish engulf in NVDA a few weeks ago and then the same formation in the S&P 500 two weeks ago. Sellers have since chewed through supports and fear is starting to spread, but is this the beginning of the end for the AI rally?
ASX 200 Outlook: Retailers Signal Consumer Strain Ahead of RBA
ASX 200 futures approach 9,000 despite a sharp retail selloff. Weakening consumer demand and elevated inflation complicate the outlook ahead of the RBA.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.