


S&P 500 forecast: US stocks hold near records with all focus on oil prices
US equity futures were little changed in the first half of Friday’s session after the S&P 500 closed at another record high in the previous session
Share this:
US equity futures were little changed in the first half of Friday’s session after the S&P 500 closed at another record high in the previous session. This week’s inflation data did little to disturb that calm. Neither the CPI nor the PPI report produced the sort of surprise that might have forced a meaningful repricing of interest-rate expectations. With trading volumes typically lighter in August, volatility has consequently remained subdued. That could potentially persist through the remainder of the month. But there is one increasingly obvious source of risk: oil. A renewed surge in crude prices could quickly challenge the market’s benign view of inflation and interest rates.
Inflation gives the Fed some breathing room
The latest data released this week have broadly reinforced the case for the Federal Reserve to leave rates unchanged at its September meeting. Consumer inflation was in line with expectations, while producer prices were somewhat softer than forecast.
Treasury yields fell modestly following the figures, although the move was hardly dramatic. More importantly, there was little in the data to suggest that inflation is accelerating across the economy.
That has allowed investors to maintain their relatively dovish interpretation of the Fed’s next move. Markets are now assigning around a 40% probability to a 25 basis point rate increase in September, down sharply from roughly 55% a week earlier.
The risk, however, is that this confidence proves premature.
Jackson Hole could reset expectations
The next significant test will come at the Federal Reserve’s annual Jackson Hole symposium later this month. With only one further CPI report and one employment report scheduled before the September FOMC meeting, policymakers will have limited fresh information with which to assess the economy.
That places greater emphasis on the tone of the debate at Jackson Hole. Any indication that policymakers remain concerned about persistent inflation could unsettle markets, particularly given how much of the recent easing in rate expectations is already reflected in asset prices.
Meanwhile, there is little on today’s US calendar likely to change the narrative. July retail sales are expected to rise by just 0.1% month-on-month, while the University of Michigan surveys are forecast to show limited movement.
Neither release is likely to matter unless the numbers materially overshoot or undershoot expectations.
All focus is on oil prices
The more immediate market risk may lie outside the economic calendar. Attention has increasingly shifted back towards the Middle East. Crude fell yesterday, providing some relief to bond markets, but the broader supply risk has not gone away. With no meaningful progress towards reviving the previous US-Iran agreement, the situation around the Strait of Hormuz remains a potentially significant threat to energy markets. Comments from US Treasury Secretary Scott Bessent, who said Washington would pursue unprecedented measures against Iran as part of its maximum-pressure campaign, add to the uncertainty.
The market may be underestimating inflation risk
The crucial point for investors is that the recent moderation in inflation expectations has coincided with a substantial rise in oil prices. Crude gained around 20% in July, and the longer those higher prices persist, the greater the risk that they begin to feed into headline inflation and, eventually, broader price expectations. If oil prices remain contained, there is little reason for investors to abandon the current soft-landing narrative. But another sustained move higher in crude could force a rapid reassessment of the Fed outlook.
Technical S&P 500 forecast and levels to watch
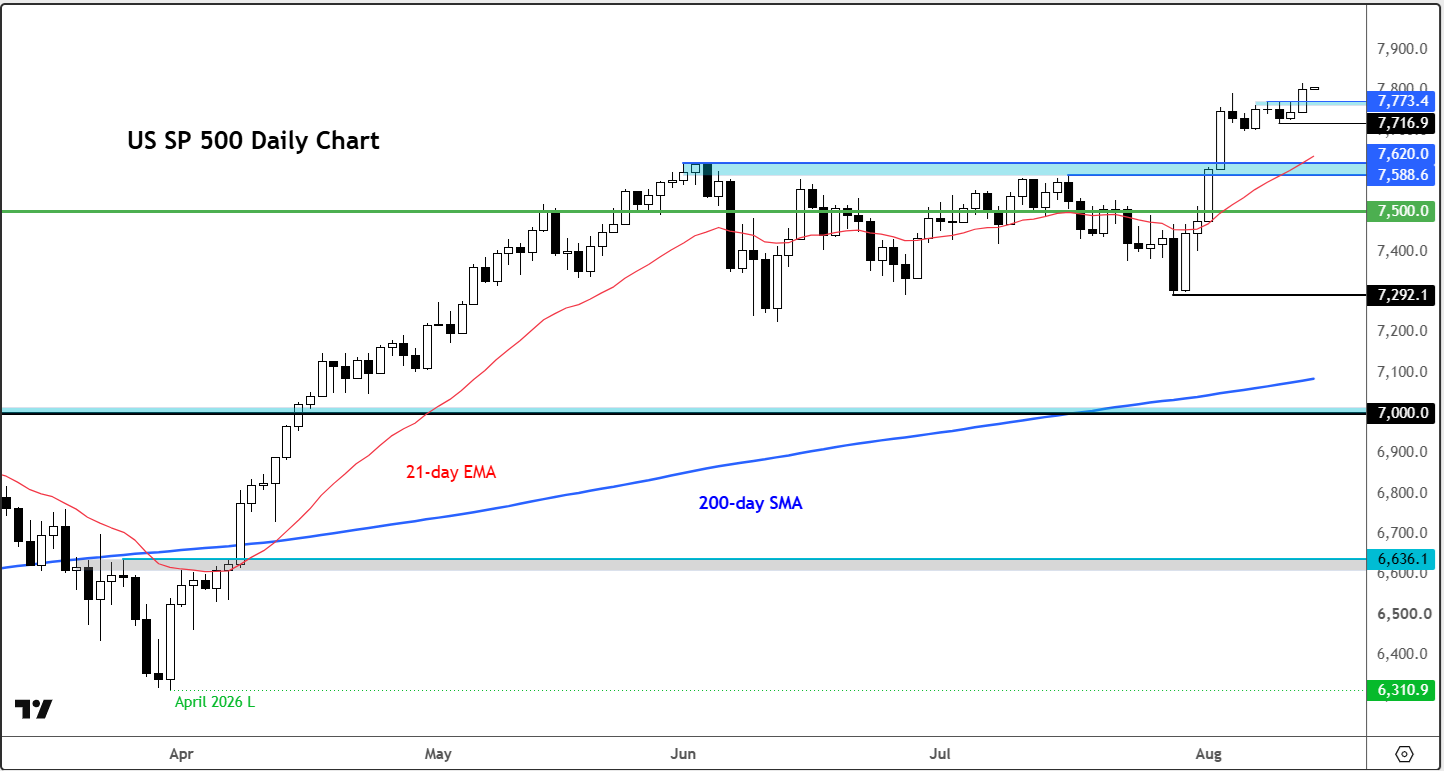
From a technical analysis point of view, the S&P 500 is continuing to grind higher which means the path of least resistance is to the upside. Short-term support is seen around 7,770ish, an area that was previously resistance until yesterday’s breakout. If this level fails to hold from above then this could lead to a bit of a pullback. Key support is now the previous highs around 7588-7620 area, followed by 7,500.
For now, equities are taking the more benign view. The S&P 500 is at record levels, volatility is subdued and rate-hike expectations have fallen sharply. The question is whether the calm is justified — or simply a reflection of a summer market that has yet to confront its next major catalyst.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.

USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.


USD/CHF Reverses as Swiss Franc Surges amid Bond Carnage
USD/CHF reverses from channel resistance as bond volatility surges and broad Swiss franc strength points to a possible carry-trade unwind.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.