



US dollar forecast: USD/JPY surged on BoJ while Crude Oil rebounds to boost USD
Heading into the week ahead, the macro calendar is quieter. But for as long oil remains supported, the US dollar forecast will remain bullish. Not only will oil prices be important for determining the direction for the dollar and USD/JPY, but bond yields too, and by extension, risk appetite.
Share this:
The US dollar remained largely supported heading into the final hours of an action-packed week. The Fed was hawkish, the dollar rallied then sold off, then bounced back again. Then the focus shifted to the Bank of Japan. Many were expecting it to hike and hike it did, but the 7-2 vote and distinctly unhurried guidance were enough to knock the yen lower. This caused the yen pairs to rally across the board, as the Japanese currency slumped. Heading into the week ahead, the macro calendar is quieter. But for as long oil remains supported, the US dollar forecast will remain bullish. Not only will oil prices be important for determining the direction for the dollar, but bond yields too, and by extension, risk appetite.
USD/JPY surges to BoJ delivers a dovish hike
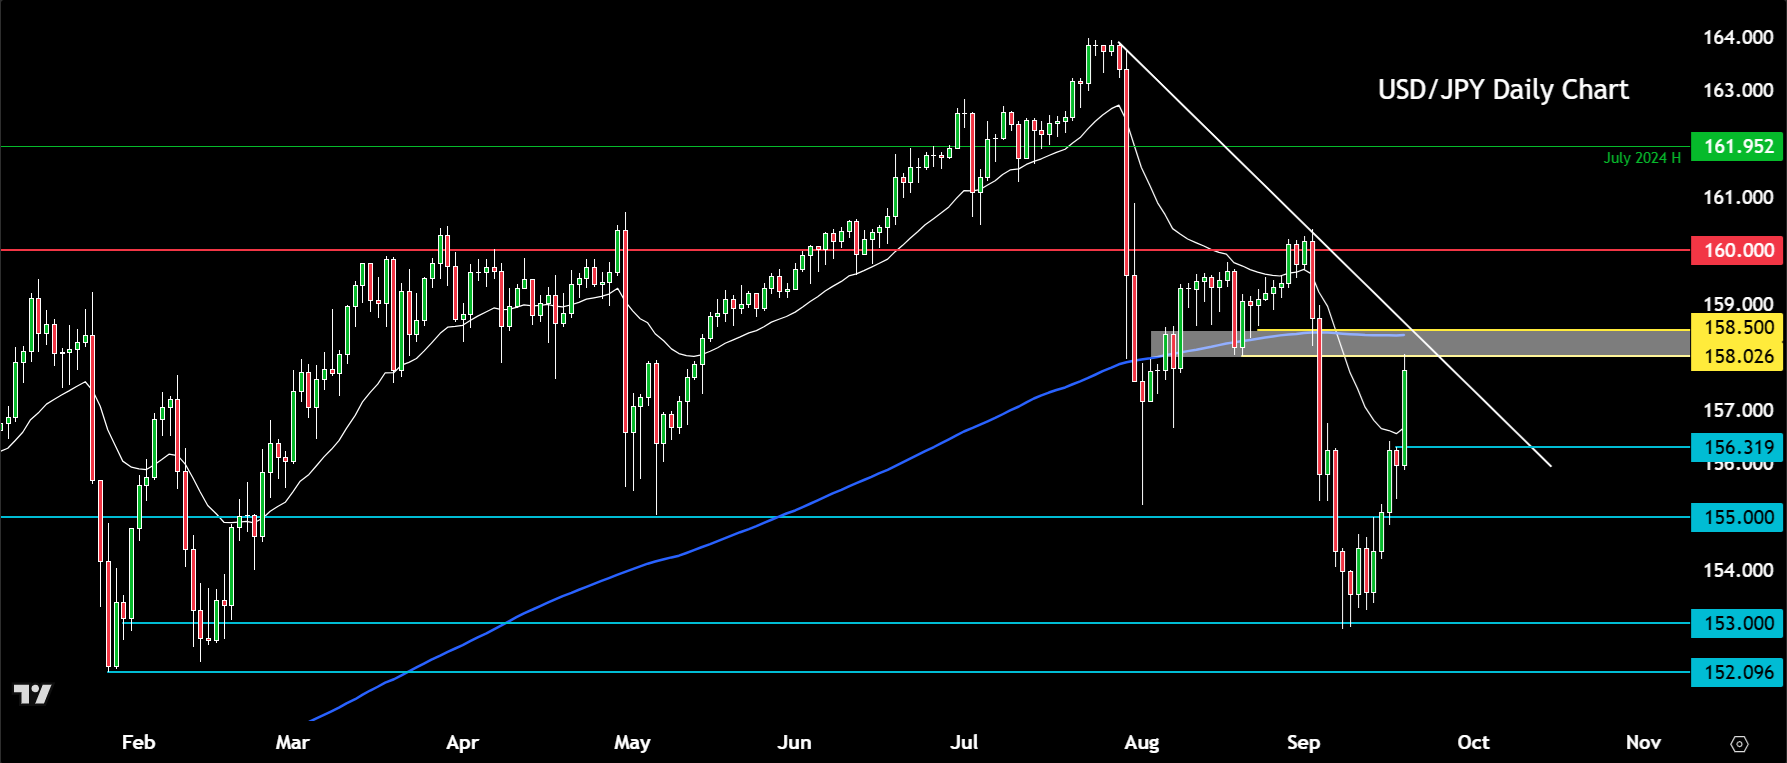
The BoJ raised rates by 25 basis points, as expected. What caught the market’s attention was the 7-2 vote and the absence of any real sense of urgency in the statement. That sent the USD/JPY surging over 1% to climb above 158.00 handle. The pair was testing the KEY area of resistance between 158.00 to 158.50 here:
Underlying inflation is approaching 2%, medium- and longer-term inflation expectations are rising, while higher input costs and wages are feeding through into prices. Yet policymakers still appear reluctant to give markets much confidence that another hike is imminent. That may be because of concerns about the economic impact of the oil shock.
For now, the pressure remains on the currency and if the USDJPY breaks through that above-mentioned resistance then a revisit of the 160.00 could be on the cards again. Support comes in at 156.30 to around 157.00.
Oil is becoming the market’s main focus
We have three major central bank rate decisions all taking place in early European session on Thursday. Apart from those, there is not much in the way of significantly important data in the week ahead. This will mean most of the focus will remain on oil prices.
The retreat in crude has taken some of the sting out of the dollar’s post-FOMC advance. But on Friday, oil prices were bouncing back off their lows with traders unwilling to bet against oil heading into the weekend.
There has been some speculation that Tuesday’s reported meeting between Donald Trump and Gulf states on the sidelines of the UN General Assembly could shed some light on the region’s next steps. Reports also suggest Trump is nearing a decision on whether to escalate military operations or pursue an end to the conflict.
For now, however, neither development looks sufficient to take Brent below the key $100 a barrel support level:
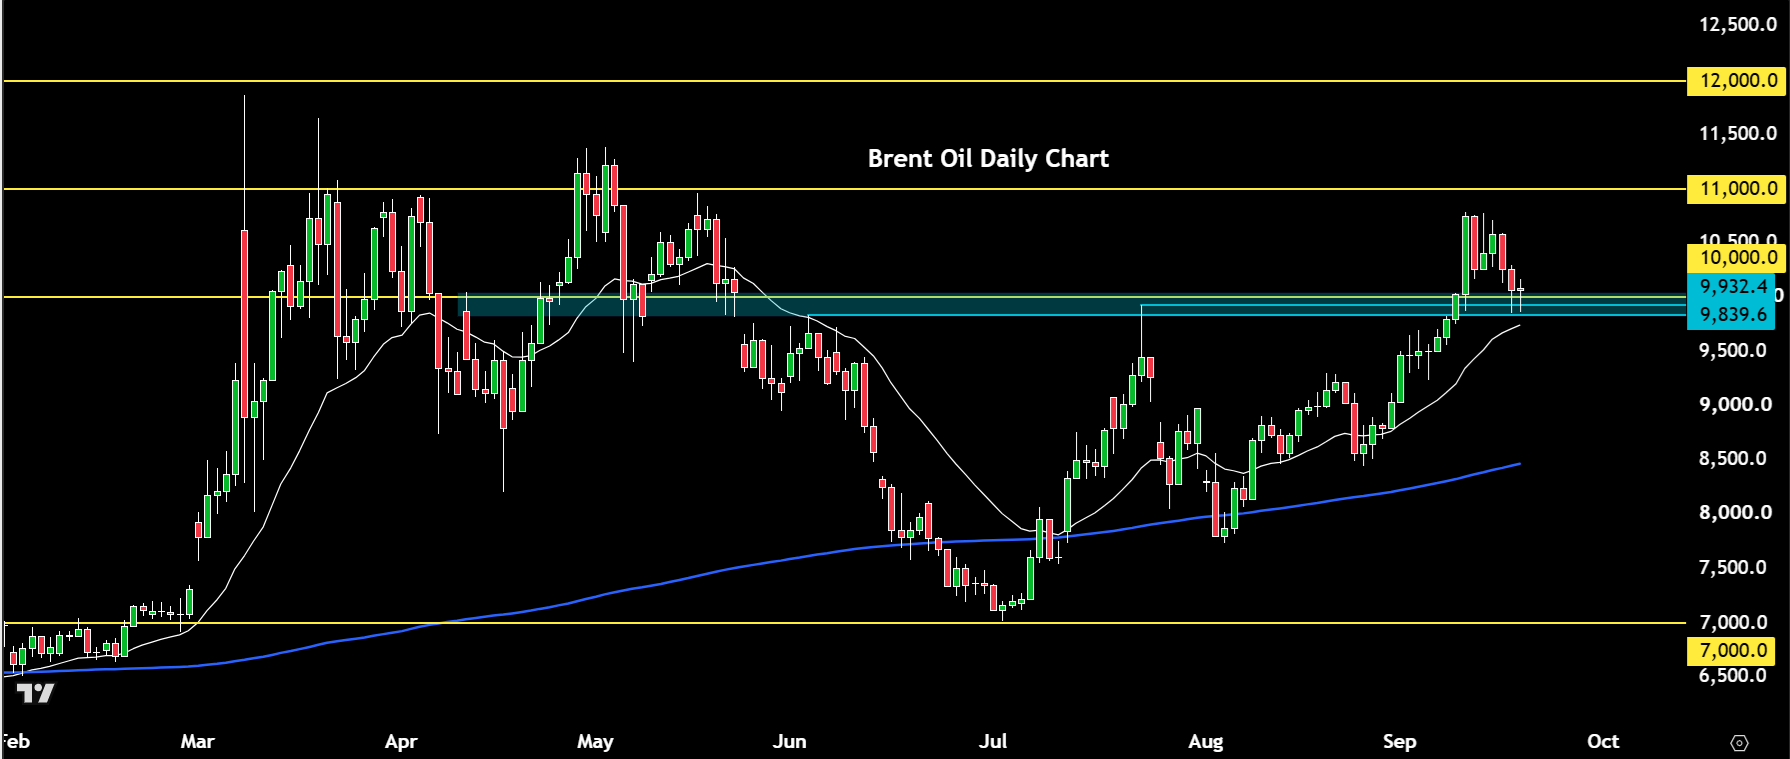
This area had been significant resistance in the past, and it is now turning into support. If oil prices go sharply higher again from here, then that could provide renewed support for the dollar against the yen, euro and other oil-importing nations.
After Wednesday’s Fed meeting, markets are starting to price in another hike in October. Those expectations could rise if the data and energy prices justify it. A sustained oil shock would therefore be dollar-positive through several channels: higher inflation expectations, higher Treasury yields and a more cautious risk environment.
Looking ahead: Swiss National Bank, Riksbank and Norges Bank
The US data calendar offers little resistance to the above narrative. That leaves crude increasingly in the driving seat. For selected pairs, we do have some important data and central bank rate decisions to look forward to, though. The Swiss National Bank, Riksbank and Norges Bank will deliver their respective rate decisions in early European trade on Thursday.
SNB: For the Swiss National Bank, the guidance is arguably more important than the headline rate decision. The central bank is fully expected to hold rates unchanged at this meeting at zero, with the next hike not seen until at least mid-2026 or early 2027. If the SNB is dovish then this could further extend the recent USD/CHF rally given the recent rate rise in the US and the potential for more hikes.
Riksbank: The Riksbank will be watched particularly closely after the Swedish krona’s sharp depreciation. The move is becoming large enough to test policymakers’ tolerance, although markets are still not looking for a hike until November.
Norges Bank: Norway’s central bank is expected to tighten next week. Even so, the NOK rally looks increasingly stretched unless crude provides another meaningful leg higher. But with the nation’s fiscal discipline being among the best in the world, the currency is likely to continue finding support on the dips.

Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?
Gold Reclaims $4,000, Bulls Eye Reversal with Seasonality Tailwind
Gold futures rebound above $4,000 as falling US yields, improving sentiment and bullish seasonality raise hopes of a significant reversal.

GBP/USD, GBP/AUD: Sterling Rally Faces a BoE Reality Check
Sterling faces a reality check as the BoE prepares to hike rates. GBP/USD and GBP/AUD approach resistance, leaving bulls vulnerable to dovish guidance.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.